1.
Company limited by shares
The most common form of BVI business company. There are no minimum capital requirements, and the company has a flexible share structure, with limited liability for shareholders and directors.

For companies conducting business outside the BVI, there is no corporate income tax, capital gains tax, dividend tax or other taxes.
The BVI are not included in lists of non-cooperative jurisdictions maintained by the EU, FATF and OECD.
The registers of directors and shareholders are not publicly available.
BVI corporate legislation is based on the principles of English common law, providing legal predictability and recognition of the jurisdiction.
Once the compliance procedures have been completed, a company can generally be registered within 1–2 business days.
The BVI remain one of the most recognised and widely used jurisdictions for international corporate structuring, holding companies and investment projects.
BVI companies are widely used as holding and investment structures and may also be used as listing vehicles on major global stock exchanges.
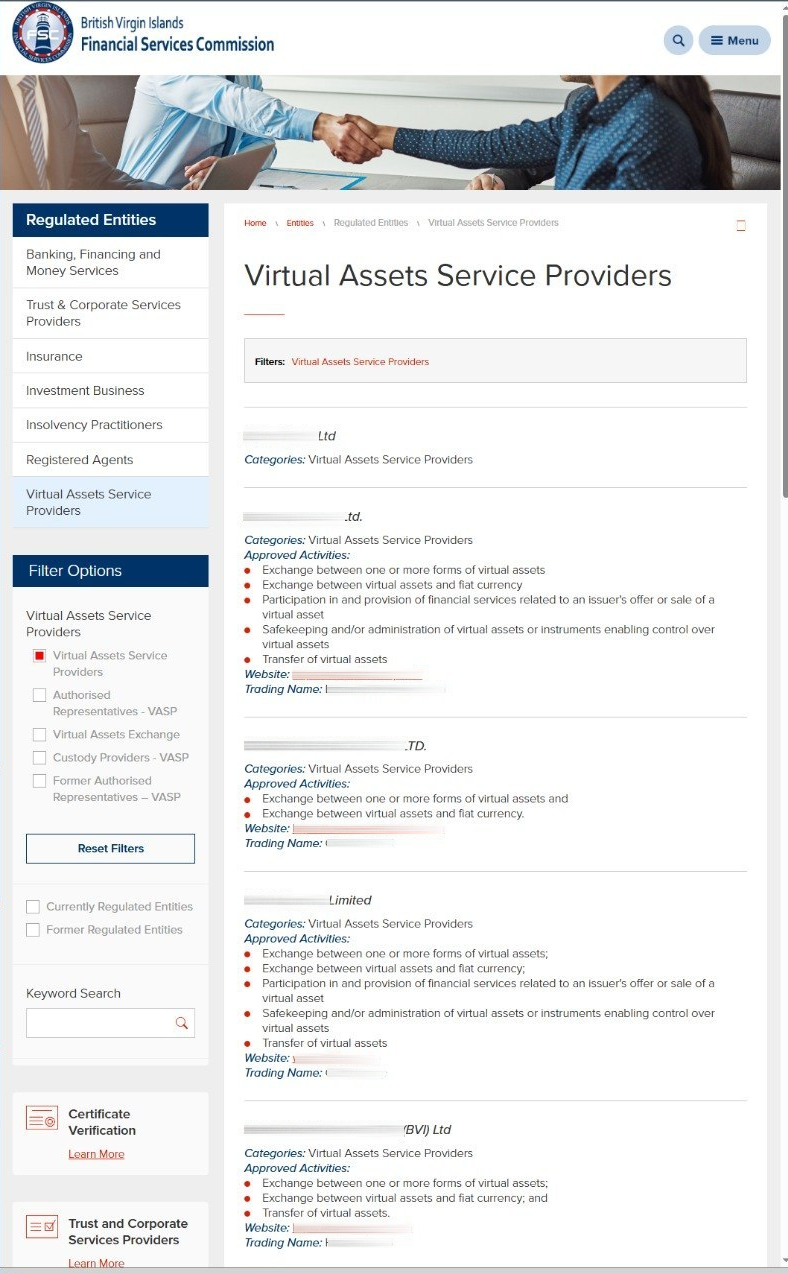
The BVI are widely chosen as a jurisdiction for crypto projects, crypto funds and fintech companies. A licensing regime for virtual asset service providers (VASP) is in place for regulated cryptocurrency activities.
Certain types of activities are subject to economic substance requirements in the BVI.
The BVI comply with international tax transparency standards, including OECD and EU requirements, and the use of “completely anonymous” corporate structures is no longer possible.
The BVI participate in the Common Reporting Standard (CRS) automatic exchange of financial information system, under which information may be exchanged with the tax authorities of the countries of the beneficiaries’ tax residence.
A company is required to keep accounting and financial records at its registered office and to prepare and submit an Annual Financial Return to its Registered Agent.
Designed for specific types of activities (e.g. securitisation transactions) and may not conduct business outside its designated scope (SPV).
A single company with segregated portfolios of assets and liabilities (SPC). Used for funds, insurance and ring-fenced structures.
British Virgin Islands Financial Services Commission
The availability of a proposed company name can be checked free of charge through the Companies Registry search system. The search will return results for existing companies with the requested name.
The first director must be appointed by the Registered Agent within 15 days of the company’s incorporation. The company’s initial shares are issued by resolution of the first director. Accordingly, the company does not commence its activities until a director has been appointed and at least one share has been issued.
A director may not be appointed without signing a written consent to his or her appointment.
If a company has no formally appointed directors, BVI legislation provides that any person who actually manages the company’s business or directs and supervises its management may be deemed to be a director.
In such circumstances, even a person who has not been formally appointed as a director may be treated as a director and be subject to all duties and liabilities imposed by law.
Subsequently, directors are appointed either by the directors themselves, if this is permitted by the company’s memorandum or articles, or by the shareholders. The directors’ particulars are disclosed to the Registered Agent and filed with the Registry only by the company’s Registered Agent.
A sole director who is also the sole member of the company may appoint a reserve director to act in the event of his or her death. If a company has no directors, the law provides that any person who manages, or directs or supervises the management of, the company’s business and affairs will be deemed to be a director and will be subject to the corresponding liabilities.
A director may be an individual aged 18 or over or a corporate entity, provided that the person is not disqualified from acting as a director under the Insolvency Act or the company’s constitutional documents.
The company’s register of directors must contain the following information, in accordance with Section 118B of the BVI Business Companies Act:
1. Where the director is an individual:
2. Where the director is a corporate entity:
The company must file a copy of its register of directors with the Companies Registry within 15 days of the appointment of the first directors or the date of redomiciliation. Any changes to the register of directors must be filed with the Registry within 30 days of the changes being made.
The Registrar must provide a copy of the register of directors to the company itself and its Registered Agent, as well as to competent and law enforcement authorities when lawfully exercising their functions.
In addition, the Registrar must provide any other person, upon request, with a list of directors contained in the company’s register of directors filed with the Registrar.
The company must maintain a register of members containing the following information:
If the company has a member acting as a nominee shareholder, the company must file with the Registrar details of the shareholder who appointed the nominee.
A copy of the register of members must be filed with the Companies Registry within 30 days of the company’s incorporation or continuation into the BVI.
The Registrar may provide a copy of the register of members only to the company itself, its Registered Agent, and competent and law enforcement authorities when lawfully exercising their functions.
The company may resolve to file a copy of the register of members and make it available for public inspection. This practice is common in financial transactions where shares in the company are provided as security.
Under the BVI Business Companies and Limited Partnerships (Beneficial Ownership) Regulations, 2024, all companies must file beneficial ownership information with the Companies Registry within 30 days of incorporation or of any change to the relevant information.
The information is filed through the VIRRGIN system by the Registered Agent, who is responsible for obtaining the relevant information and verifying each ultimate beneficial owner in accordance with applicable AML/CFT requirements.
Nil filings are not permitted.
The following information must be provided for each beneficial owner: full name, date and place of birth, residential address, gender, nationality, occupation, and nature of ownership or control.
Where a beneficial owner acts through a legal entity, information on that legal entity must also be disclosed, including its name, registration number and date, registered or principal office address, country of registration, legal form and governing law, registry number, and nature of ownership or control.
The following persons are subject to mandatory disclosure if they directly or indirectly:
If no shareholder meets the 10% threshold, the beneficial owner is identified based on the “mind and control” criterion, i.e. the person who actually makes key decisions.
Confidentiality and Access to Beneficial Ownership Information
The Register of Beneficial Owners is not publicly accessible. Access to or disclosure of information is governed by the BVI Data Protection Act, 2021. At the same time, the access threshold is set at 25%, meaning that the VIRRGIN system does not automatically display information on beneficial owners holding less than a 25% interest, while the filing threshold remains 10%.
The information may be accessed by:
From 1 April 2026, any applicant who can demonstrate a “legitimate interest” (for example, to prevent or detect money laundering or terrorist financing where there are reasonable grounds for suspicion) may request information from the BVI Beneficial Ownership Register upon payment of a USD 75 fee. The Registrar notifies the affected company, which has five days to file a brief objection and a further five days to submit a fully reasoned objection supported by evidence.
Grounds for objecting to disclosure under the “legitimate interest” regime may include a risk of harm or threats to the safety of the beneficial owner or their family, the age or capacity of the beneficial owner, conflict with the public interest, professional confidentiality, or exceptional circumstances requiring confidentiality. Objections must be reasoned and supported by evidence, such as medical, police or legal documents.
Where a request is granted, only a limited set of information is disclosed and solely for the stated purpose. Unlawful use of the information may result in sanctions and restrictions on access.
Unauthorised use or disclosure of beneficial ownership information may result in a fine of up to USD 50,000 and restriction of access to the system for three years.
The Registrar may also request information from a beneficial owner where no response has been received and may temporarily restrict transactions involving an interest or the exercise of rights attached to that interest until the required information is provided.
Information relating to an individual is removed from the Register five years after that person ceases to be a beneficial owner.
A Registered Agent may print a beneficial ownership register only for clients for whom it acts as Registered Agent.
Liability for Non-Compliance
The Registrar may block the filing of documents, the issuance of certificates and may initiate the removal of a company from the Register for failure to pay penalties.
The incorporation documents are filed with the Registry by the Registered Agent. The applicable government registration fees are paid at the same time.
Once the documents have been reviewed, the Registrar assigns the company a unique number, issues a Certificate of Incorporation, and returns to the Registered Agent a copy of the Memorandum and Articles of Association bearing the Registrar’s seal.
⏱ Incorporation time – 24 hours.
For use outside the Virgin Islands, the corporate documents are apostilled. The package usually includes the Certificate of Incorporation, Memorandum and Articles of Association, appointment of the first directors and their resolutions, as well as corporate registers (optional).
If the company intends to engage in activities requiring authorisation, such as banking, insurance, financial services, virtual asset services (VASP) and others, the relevant licences must be obtained.
To commence the company’s actual business operations, a corporate account is opened:
Once the account has been opened, the company can commence full business operations, enter into transactions and make and receive payments from partners and clients.
The legal system of the BVI is based on the principles of English common law and combines local legislation with judicial precedents derived from English law.
The BVI is a British Overseas Territory with its own legislative and judicial system, including a specialised Commercial Court that handles corporate and financial disputes.
The principal legislation governing companies is the BVI Business Companies Act, 2004.
The BVI Business Companies Act abolished the concept of authorised capital (and share capital as such), replacing it with the maximum number of shares that a company is authorised to issue. This is usually set at 50,000 shares, which is the maximum number available for the minimum government fee.
Bearer shares are not permitted.
A BVI company must issue at least one share, with the payment terms determined upon incorporation. Shares may be issued in any currency and may have any par value or no par value.
The company’s shares must be issued promptly after the appointment of the first director, i.e. no later than 15 days from the date of incorporation. Shares are considered issued only once the name of the member has been entered in the company’s register of members.
A company must have a corporate seal, an impression of which must be kept at the office of the company’s Registered Agent.
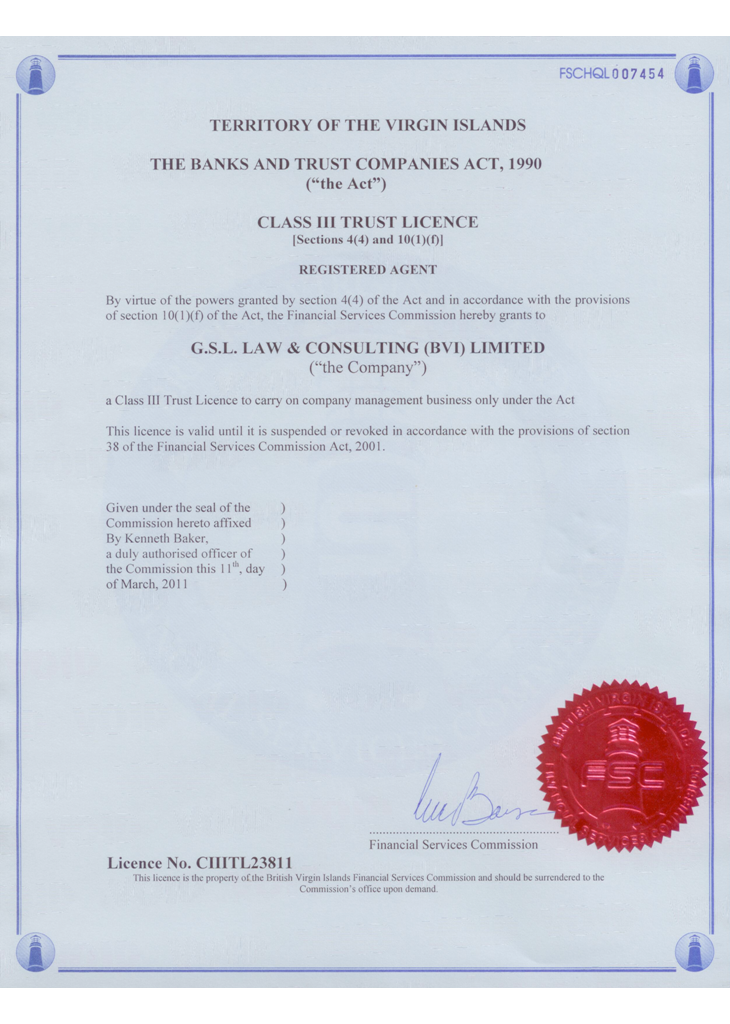
GSL is a licensed Registered Agent in the British Virgin Islands and operates in accordance with the requirements of the Banks and Trust Companies Act and applicable AML/CFT legislation.
A Class III Trust Licence authorises the holder to:
In certain circumstances, having a registered office alone is not sufficient and the company must have a genuine presence in the BVI – economic substance. The Economic Substance Act imposes requirements on BVI companies and partnerships, as well as foreign companies carrying on business in the BVI, where they conduct relevant activities, such as holding, finance and leasing, insurance, banking, headquarters, fund management, shipping or intellectual property business.
Such companies must maintain adequate economic substance in the BVI, including premises, employees and expenditure appropriate to the nature and scale of their activities.
Failure to comply with the economic substance requirements or to provide the required information may result in significant penalties, including fines of up to USD 200,000, or up to USD 400,000 for high-risk IP companies, imprisonment for up to five years, and striking the company off the Register.
Under the Economic Substance (Companies and Limited Partnerships) Act, 2018, as amended in 2021, BVI companies and partnerships carrying on relevant activities are required to maintain adequate economic substance in the BVI.
The legislation was introduced to comply with EU and OECD standards (BEPS Actions 5) and prevent the establishment of companies that generate profits without conducting genuine business activities.
Non-resident companies and partnerships are exempt from the provisions of the law if they are tax residents in another jurisdiction not included on the EU blacklist. Tax residence in another jurisdiction must be supported by documentary evidence.
Where a company carries on a relevant activity, it must comply with the economic substance requirements, which include three key tests:
1. Directed and Managed Test – the company must be directed and managed from the BVI. This includes holding board meetings with a quorum of directors physically present in the BVI and keeping records of decisions relating to the relevant activity in the BVI.
2. Adequacy Test – this assesses whether the company has adequate resources in the BVI, including:
The adequacy of the resources is assessed based on the scale and nature of the activity.
Part-time employees are taken into account proportionately to the amount of time they work. However, occasional work in the BVI by an employee who is normally based outside the BVI is not counted as physical presence in the BVI for economic substance purposes.
3. Core Income Generating Activities (CIGA) Test – this assesses whether the company’s core income-generating activities are carried out in the BVI.
Pure Equity Holding Entities, i.e. companies that solely hold shares and receive dividends or capital gains, are subject to a simplified economic substance regime. For such companies, compliance with basic corporate obligations, together with a minimum level of staffing and premises for managing the assets, is generally sufficient.
Each BVI company must file an annual economic substance declaration through its Registered Agent within six months after the end of its financial period.
If a company does not carry on any relevant activity, it must still file a declaration – a “nil return”.
The declaration includes information on relevant activities, employees and expenditure in the BVI, office addresses, a description of equipment and details of any outsourcing arrangements.
| Violation | Penalty |
| Initial failure to meet economic substance requirements | USD 5,000–20,000 (or USD 50,000 for high-risk IP companies) |
| Subsequent violation | USD 10,000–200,000 (or USD 400,000 for high-risk IP companies) |
| Providing false information or failing to provide information | Up to USD 75,000 and/or imprisonment for up to 5 years |
The International Tax Authority (ITA) may initiate proceedings to liquidate the company.
Relevant activities are activities that are considered to present a risk of artificially shifting profits to low-tax jurisdictions.
Under BVI legislation, the following categories are considered relevant activities:
If a company carries on one or more of these activities, it is subject to the economic substance requirements. A key element is the Core Income Generating Activities (CIGA) Test, which focuses on the core operations that directly generate income. These activities must be carried out in the BVI.
Examples of CIGA for different types of relevant activities include:
The list of CIGA is not exhaustive. The regulator assesses the company’s actual activities and where its income is genuinely generated.
The total cost of incorporation consists of registration fees, annual maintenance fees (payable one year in advance at the time of registration), legalised corporate documents package, and courier delivery to the destination.
for 1 year, Power of Attorney not included
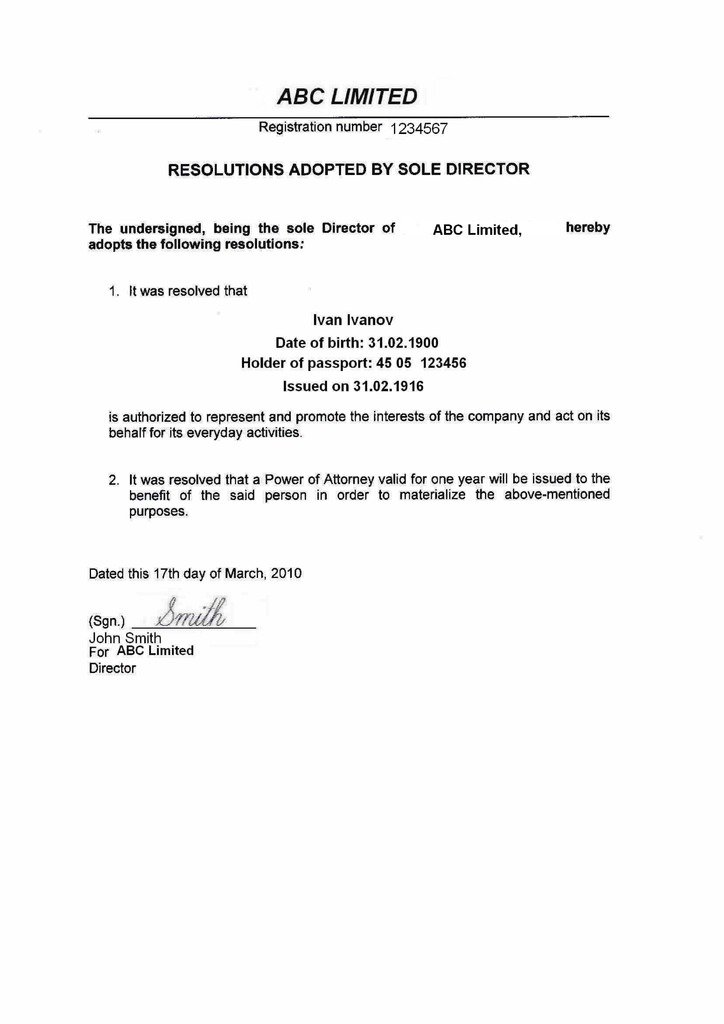
Resolution to issue a Power of Attorney
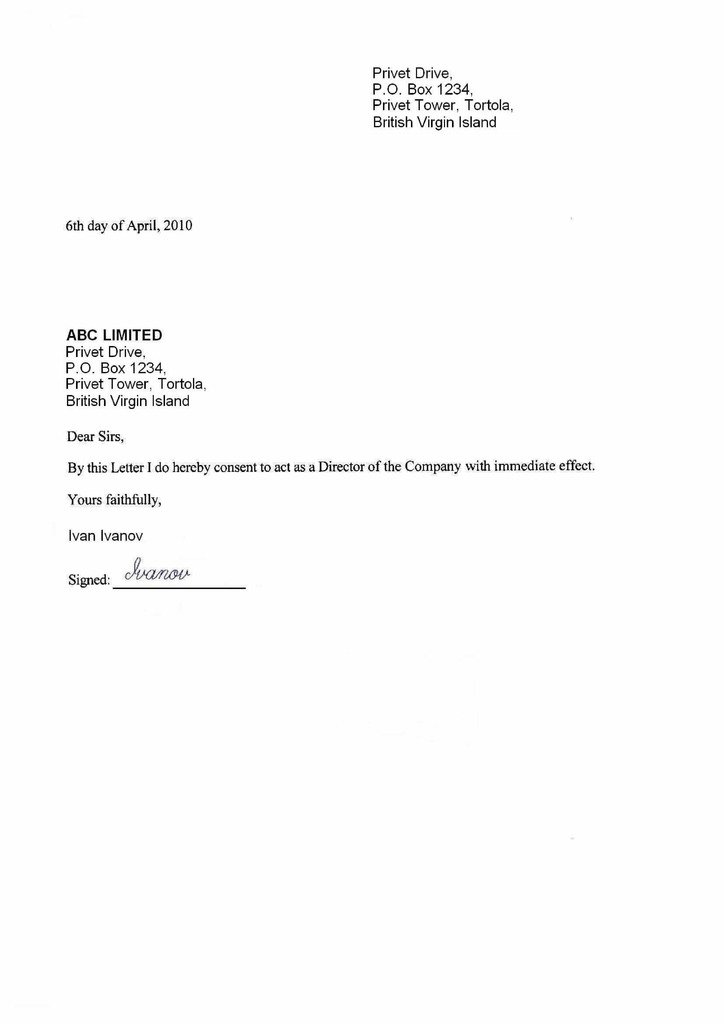
Nominee Director’s Consent Letter
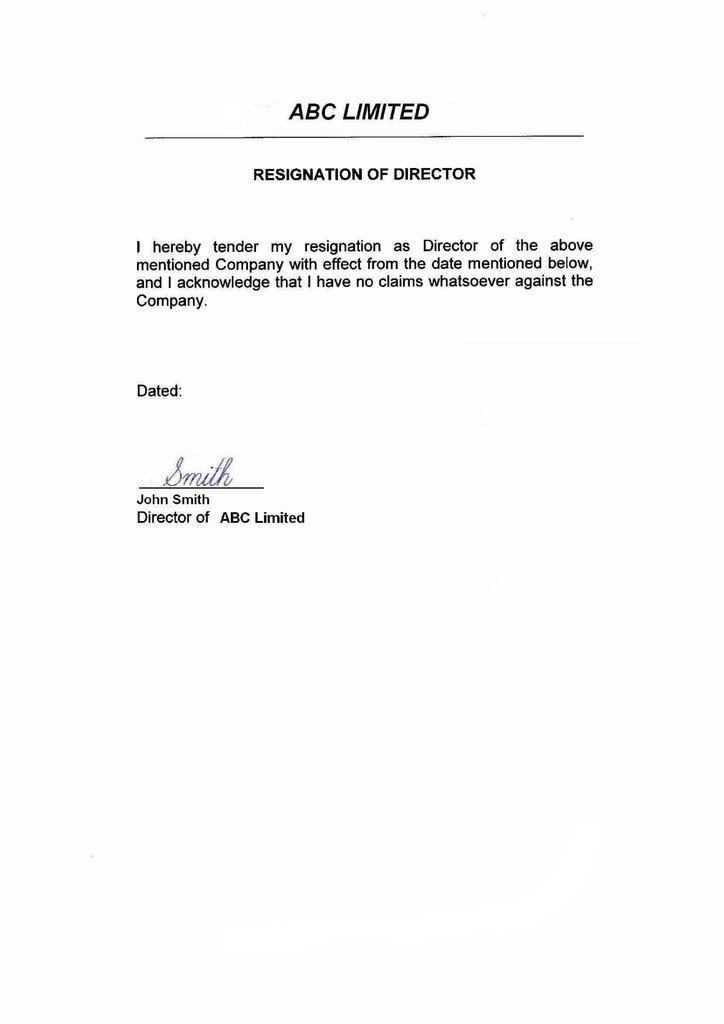
Director Resignation Letter
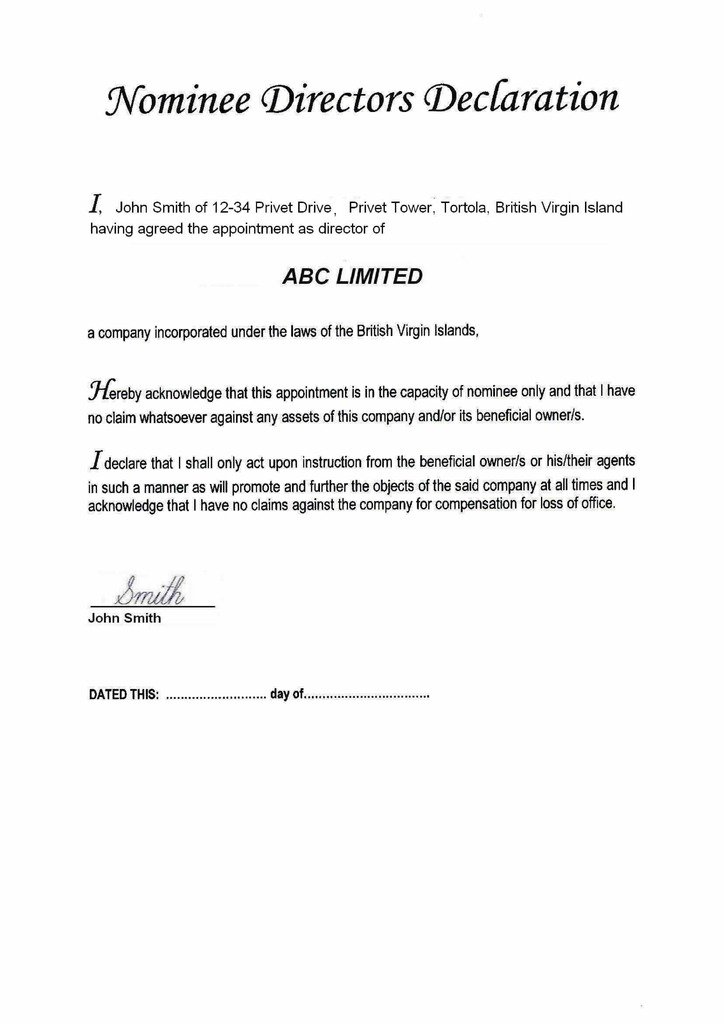
Nominee Director’s Declaration of nominee services
for 1 year
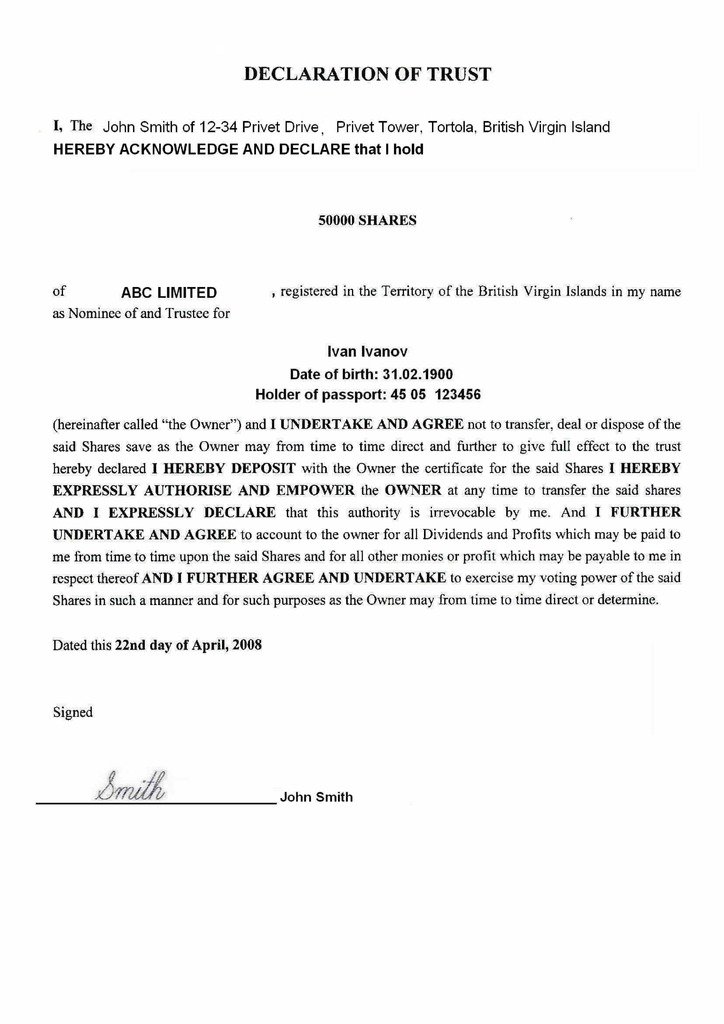
Nominee Shareholder’s Deed of Trust
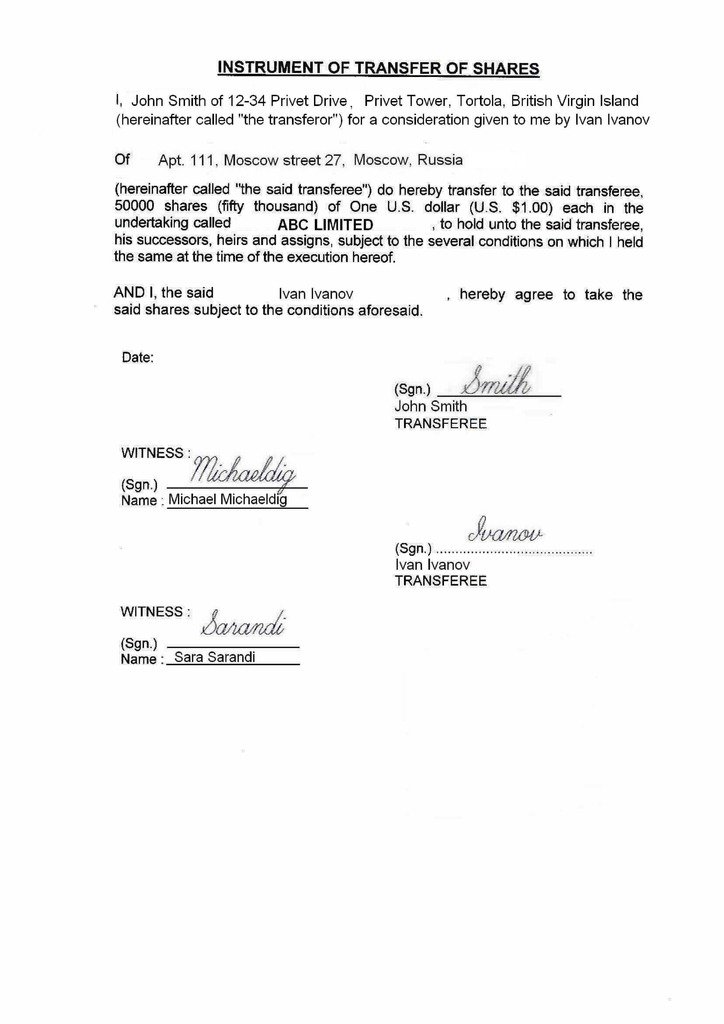
Instrument of Transfer
Payable in cases of: company registration, company renewal, company liquidation, transfer to a new agent, issuance of a Power of Attorney to a new attorney, change of director / shareholder / beneficial owner (except for changes to a nominee director / shareholder), signing of documents
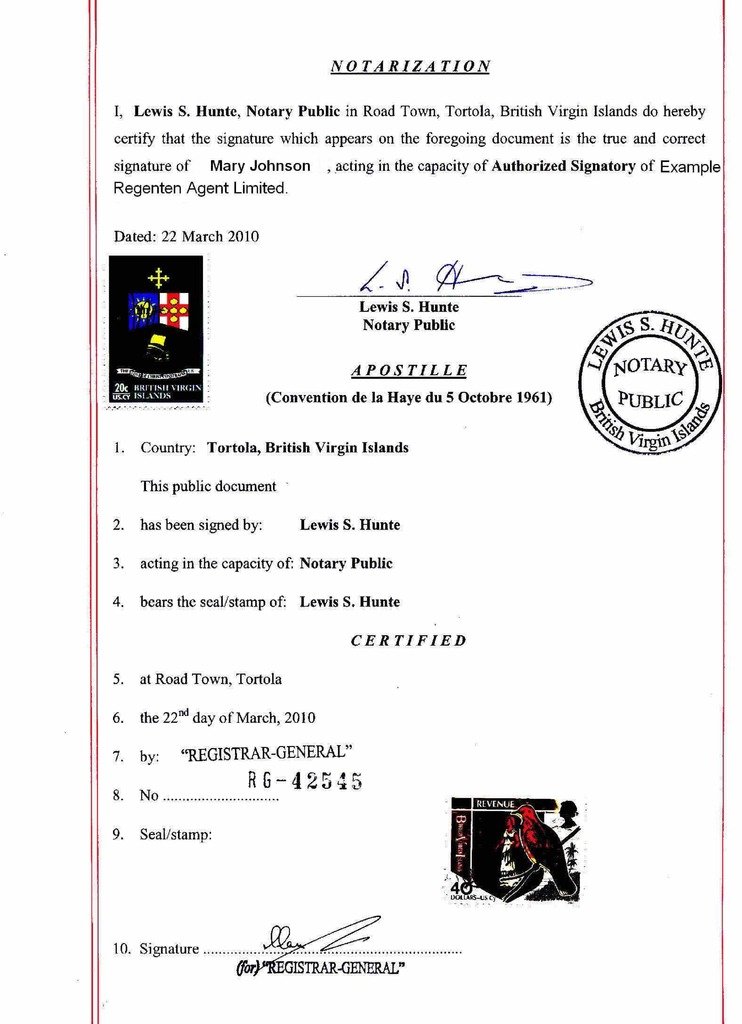
Confirms the authenticity of the corporate documents for use outside the British Virgin Islands.
The copy is certified by a notary, whose signature is authenticated by the BVI Registrar by means of an apostille.
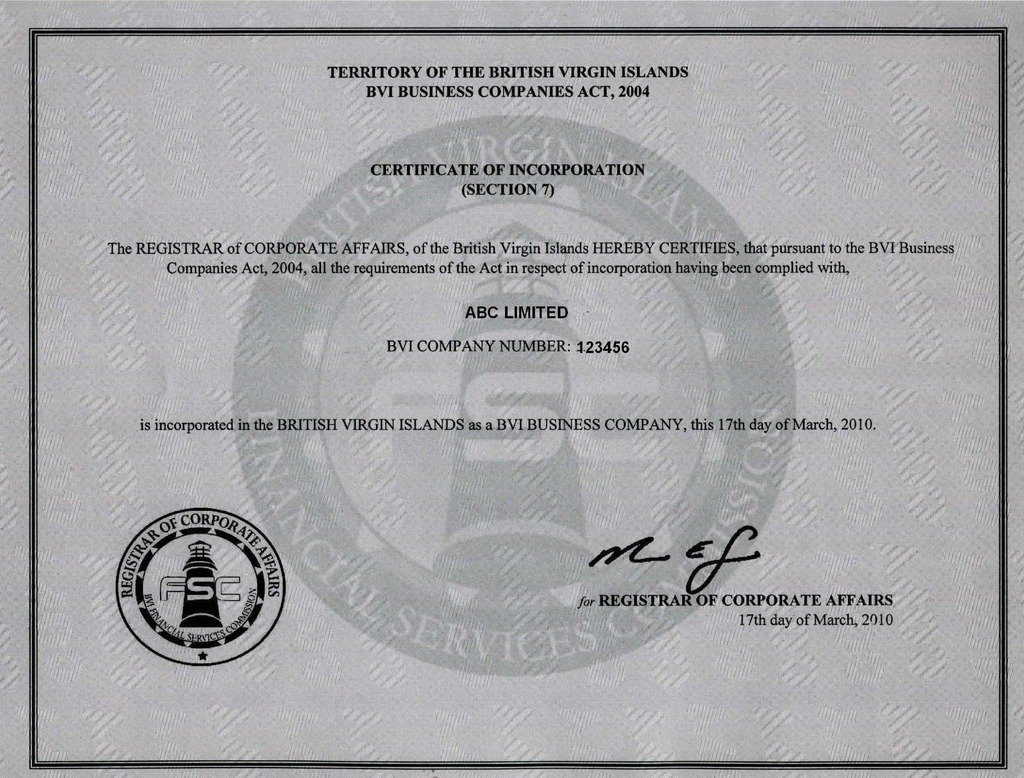
Confirms the incorporation of the company.
Issued by the Registry of Corporate Affairs in accordance with the BVI Business Companies Act, 2004.
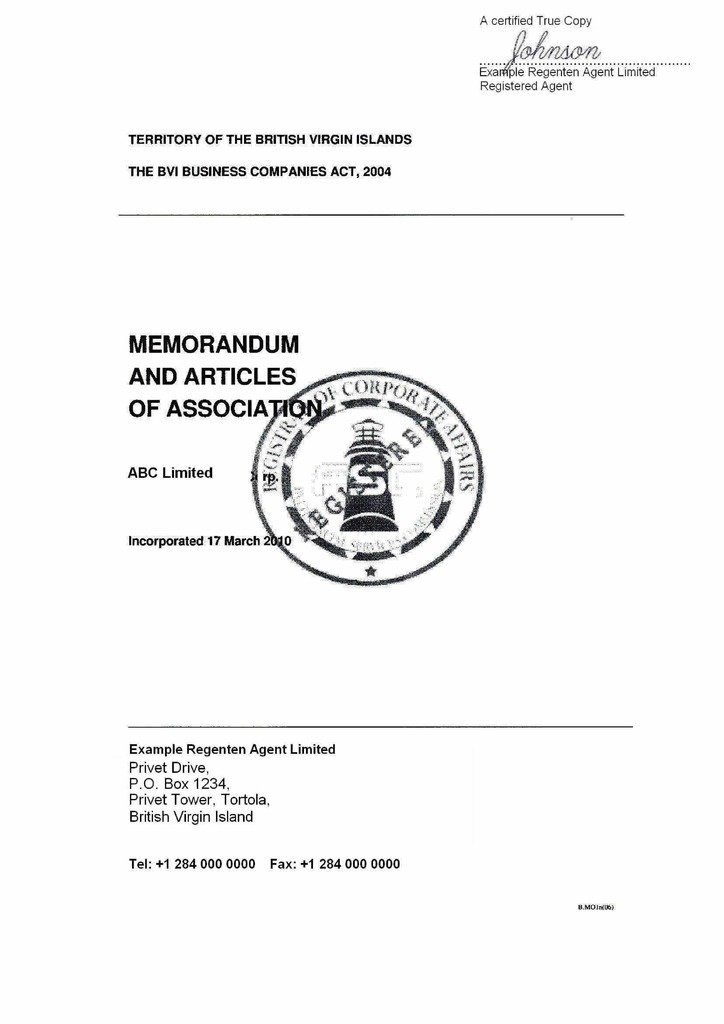
Set out the company’s structure, the rights and obligations of its directors and shareholders, and the procedures for making corporate decisions.
Signed by the incorporator (Registered Agent) and filed with the Registry of Corporate Affairs.
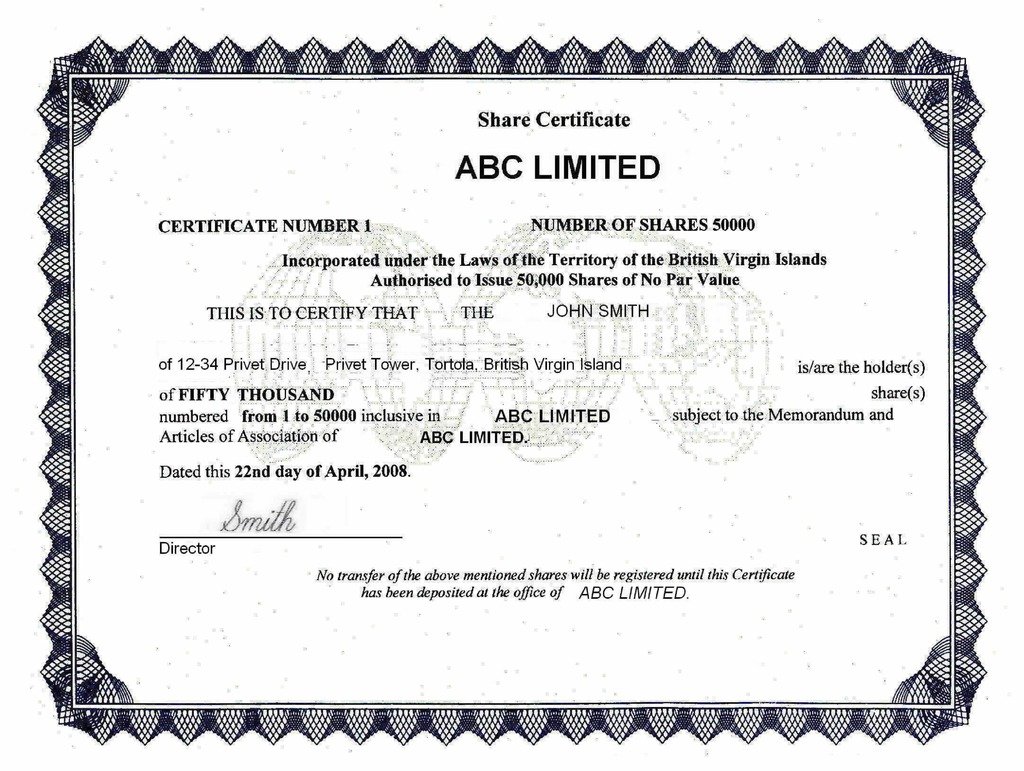
Confirms a shareholder’s ownership of the specified number of shares.
Issued by the company and signed by its directors or authorised persons.
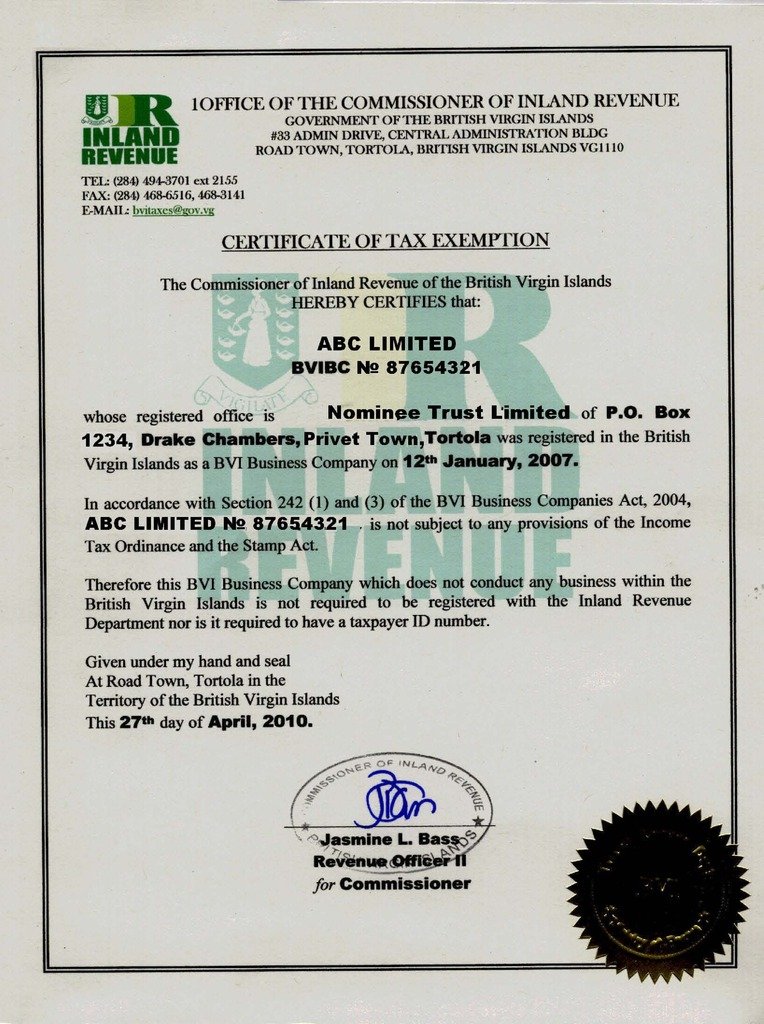
Confirms that the company does not carry on business in the BVI, does not have a tax identification number and is not subject to BVI corporate income tax legislation.
Issued by the BVI Inland Revenue Department.
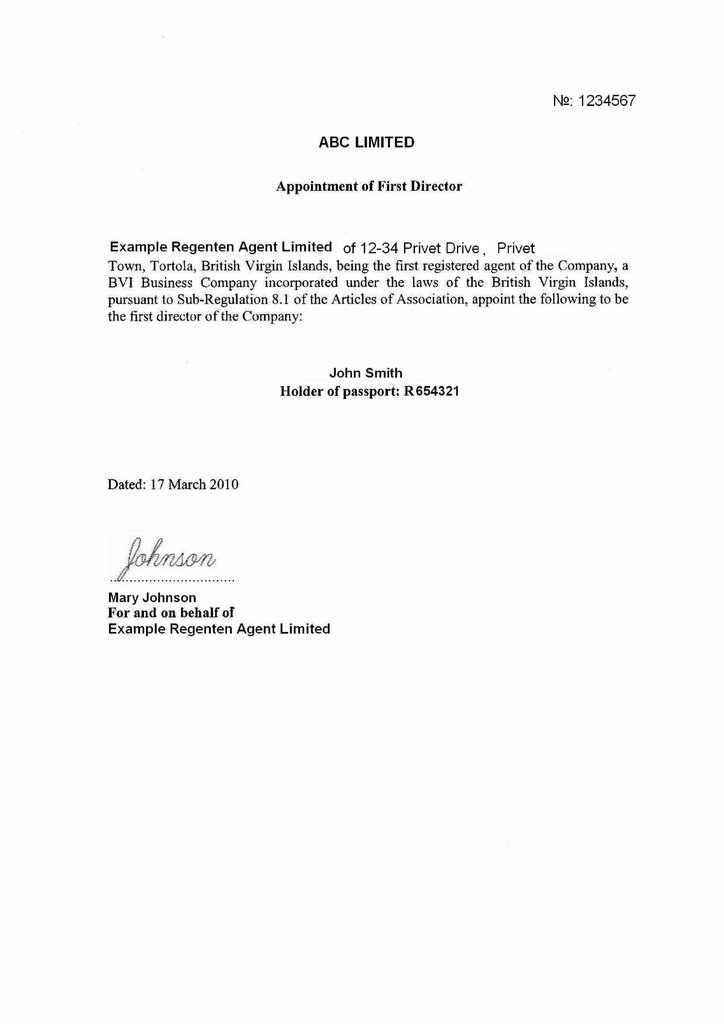
Resolution appointing the first director, executed by the subscribers to the company’s Memorandum and Articles of Association.
Issued under the company’s seal.
A classic tax-neutral jurisdiction with no corporate income tax, VAT, customs duties or exchange controls. It is well suited to structuring supply chains and re-export transactions where the BVI company acts as an intermediary in the trading chain.
For such activities, the company only needs to be renewed annually. No audit of trading activities by local tax authorities is required.
Fast setup, minimal costs of maintaining the structure and full exemption from taxes on income from digital sales, subscriptions and SaaS services. A BVI company can be readily integrated with international payment systems and merchant accounts.
At the same time, VAT rules and tax requirements in the countries where the buyers of your digital products or services are actually located must be taken into account.
A high level of confidentiality, with beneficial ownership information not publicly available, combined with a well-developed system of English case law. No tax is imposed on incoming or outgoing dividends, royalties or capital gains from the sale of subsidiaries.
A BVI company can be used to hold real estate, vessels, aircraft, intellectual property and securities. When carrying on holding activities, the minimum economic substance requirements must be observed.
Regulator: British Virgin Islands Financial Services Commission (FSC)
Legal basis: Virtual Asset Service Providers Act, 2022
Scope of regulation: cryptocurrency exchanges and custodial service providers, including:
Licence fee: from USD 10,000
Licensing period: 6–8 months
BVI companies can open corporate accounts with banks and payment service providers outside the BVI. The choice of financial institution depends on the company’s business structure, the citizenship of its beneficial owners, the countries in which the company conducts business and its expected transaction volumes.
To pass the compliance review, information on the company’s owners, business activities and source of funds is required.
The documentation requirements and application processing times depend on the financial institution selected.
The client develops software for live streaming and online community forums, as well as tools for configuring and managing broadcasts and interacting with viewers.
After considering several jurisdictions proposed based on the client’s criteria, the client decided to incorporate in the BVI.
As the project was an IT startup intended to attract investment, it was necessary to develop bespoke Articles of Association and a Shareholders’ Agreement to regulate relations between the founders and investors.
The constitutional documents provided for the issue of voting and non-voting shares, while the agreement addressed matters such as exit arrangements, pre-emption rights, minority shareholder tag-along rights, matters reserved for shareholder approval and a number of other issues.
A jurisdiction was selected that best met the client’s criteria in terms of confidentiality, zero taxation and minimal accounting requirements.
A company was incorporated with Articles of Association tailored to the client’s specific requirements, and a Shareholders’ Agreement was prepared setting out key matters such as the company’s governance and distribution of profits.
The clients, who had experience investing in the stock market, brought together a pool of major investors willing to place their funds under their management.
Two companies were incorporated in the BVI for the clients.
The first acted as a closed-ended private investment fund structured as a segregated portfolio company, with separate classes of voting and non-voting shares for investors. At the time the project was implemented, such funds did not require a licence, but subsequently similar structures became subject to a recognition procedure with the regulator.
The second company managed the fund’s assets and therefore was required to obtain Approved Investment Manager (AIM) status. GSL prepared the application and all supporting documentation, assisted with communications with the regulator, responded to additional requests and obtained a Certificate of Recognition as an Approved Investment Manager for the management company.
A comprehensive fund structure was established for the clients in one of the internationally recognised fund industry jurisdictions.
A key step was the establishment of the clients’ own management company within a short timeframe, enabling them not only to launch their first project quickly but also to use the company to manage their other funds in the future.
Following the entry into force in the BVI of the Securities and Investment Business Act (SIBA), the client’s forex company became subject to mandatory licensing requirements.
To bring its activities into compliance with the new legislation, the company, with our assistance, submitted an application for a licence.
As part of the application, documents were collected for all directors, shareholders and the compliance officer to demonstrate their education and qualifications sufficient for participation in investment business, as well as the absence of criminal convictions and bankruptcy proceedings.
The application also included a draft Compliance Manual describing client due diligence procedures, a detailed business plan, evidence of adequate capitalisation and financial risk insurance, as well as confirmations from the authorised representative and auditor of their willingness to provide services to the company after the licence was granted.
The client’s company successfully completed the licensing process and obtained a SIBA licence in the required category.
As a result, the client was able to continue providing forex services lawfully from the BVI without the risk of claims, penalties or compulsory closure by the regulator. The structure also became more reliable and attractive to counterparties, investors and business partners, banks and payment service providers.
The client had built a yacht and was considering registering it under the flag of the British Virgin Islands.
The most straightforward way to register the vessel under the jurisdiction’s flag was to register it in the name of the client’s existing BVI company.
The vessel’s name is checked and reserved with the Virgin Islands Shipping Registry, and a local representative is appointed.
A package of forms and supporting documents is submitted, including the application for registration, documents relating to the owning company, a Declaration of Eligibility, evidence of ownership (for a new vessel, a Builder’s Certificate) and a Certificate of Survey and Tonnage issued by an authorised surveyor.
Once the documents have been approved, the Shipping Registry issues a Carving and Marking Note with instructions for marking the vessel and completes the registration upon receipt of photographs showing the applied markings and the form signed by the surveyor.
A radio licence and MMSI number are also obtained from the Registry.
GSL registered the yacht in the name of the client’s company in one of the Caribbean’s most popular jurisdictions for vessel registration.
An important practical advantage of the BVI flag is that the vessel does not need to be physically located in the BVI either to complete or maintain its registration and may be operated anywhere in the world.
In addition, the BVI Shipping Registry’s membership in the Red Ensign Group provides a high level of reputation and international recognition of certificates, as well as access to British consular assistance and the protection of the Royal Navy.
The BVI Business Companies Act allows a foreign company to change its jurisdiction of incorporation and continue its business as a BVI company. This procedure, known as continuation or redomiciliation, does not require the company to be liquidated or a new structure to be established. The company retains its legal personality, while the continuation does not terminate or limit any obligations incurred previously and does not affect the continuity of its business. The company continues to exist as the same legal entity.
Redomiciliation Procedure
After the Certificate of Continuation has been issued, all necessary steps are taken to remove the company from the register of its previous jurisdiction.
BVI legislation allows a company to continue in a foreign jurisdiction without being liquidated, provided that this is not prohibited by its Memorandum and Articles of Association.
The decision to continue in another jurisdiction is made by the company’s directors or members and implemented in accordance with the laws of the receiving jurisdiction.
To commence the continuation procedure, the company must confirm that it is in good standing, is not subject to any regulatory restrictions and has complied with all requirements of the foreign jurisdiction for continuation.
The law establishes a mandatory notification procedure for interested parties. The company must:
Once these requirements have been satisfied, the Registered Agent files a notice with the Registrar in the BVI. The Registrar issues a Certificate of Discontinuance, removes the company from the Register and publishes the relevant notice.
From the date of issue of the Certificate of Discontinuance, the company ceases to be registered in the BVI and continues to exist in the new jurisdiction.
Redomiciliation changes the company’s jurisdiction rather than terminating its existence. Accordingly, the company’s obligations continue with it in the new jurisdiction.
Voluntary liquidation is the most appropriate and controlled way to close a company, as it allows the company to formally wind up its affairs, settle its obligations and obtain a Certificate of Dissolution issued by the Registrar of Corporate Affairs.
Voluntary liquidation is available to companies that have no outstanding obligations to creditors or are able to pay their debts as they fall due.
At the start of the procedure, the company must have ceased carrying on business and be in Good Standing, with all government fees paid.
The liquidation process is carried out with the involvement of a voluntary liquidator, who oversees the company’s winding-up. Since 2023, a voluntary liquidator may only be a BVI resident. The liquidator must have the relevant professional qualifications and experience in company liquidations and must not have been affiliated with the company being liquidated during the preceding two years.
The voluntary liquidation procedure includes the following stages:
The procedure generally takes approximately 2–3 months.
During the liquidation, the liquidator must collect the company’s accounting and corporate records and deliver them to the Registered Agent. The Registered Agent is required to retain these documents for at least five years.
Once the voluntary liquidation has been completed, the company is considered finally dissolved and may only be restored by court order and solely for the purpose of properly completing the liquidation process.
An alternative way to terminate a company’s activities in the BVI is to have the company struck off the Register, followed by automatic dissolution.
A company may be struck off the Register for the following reasons:
Before striking the company off the Register, the Registrar sends the company a notice and allows 90 days to remedy the breaches. If the breaches are not remedied, the company is struck off the Register and is immediately deemed dissolved, with no transitional period as was previously the case.
A company may be restored within five years from the date of strike-off, generally without court proceedings, and will be deemed to have continued in existence without interruption. Restoration may also be initiated by the company’s creditors.
Following strike-off, the company loses its legal capacity, and its assets vest in the Crown as bona vacantia.
However, strike-off is not a “clean” liquidation. In practice, voluntary liquidation is more commonly used as a more controlled method of closing a company, as strike-off involves the following risks:
Strike-off may be an acceptable option for a company that has never carried on business, has no assets and has no outstanding obligations.
BVI legislation provides for the restoration of a company after it has been struck off the Register.
Following restoration, the company is deemed not to have ceased to exist, and its existence continues as if it had never been struck off the Register.
An application to the court for restoration of a company that has been struck off and automatically dissolved may be made within five years from the date of publication of the notice of strike-off by:
The court will grant the application if it considers restoration just and equitable for the purpose of commencing, continuing or concluding legal proceedings by or against the company, making an application for the return of company property that has vested in the Crown as bona vacantia, or in other circumstances where restoration is warranted having regard to the particular circumstances of the case.
The restoration procedure includes the following stages:
1. Preparation of an application to the court for restoration of the company.
2. Preparation of an affidavit explaining the reasons for the company’s strike-off and the purposes of its restoration.
3. Notification of the application to:
4. Consideration of the application by the court and issuance of an order.
In some cases (for example, involving significant assets), the application may be heard by the Commercial Division of the High Court of the BVO.
5. Filing a certified copy of the court order with the Registry of Corporate Affairs.
6. Restoration of the company to the Register and issuance of a Certificate of Restoration.
Following restoration, the company must appoint a Registered Agent and bring itself into compliance with the applicable BVI legal requirements, including filing the required corporate registers, complying with economic substance requirements and paying all applicable government fees and penalties.
BVI companies are not subject to mandatory statutory audits and are not required to file financial statements with government authorities. However, a company must maintain accounting records and submit an Annual Financial Return (simplified financial reporting) to its Registered Agent each year.
For banks, investors and compliance with CFC (Controlled Foreign Company) rules, financial statements prepared in accordance with IFRS and an audit report may be required.
Failure to comply with accounting record retention requirements or the requirement to file the Annual Financial Return may result in penalties of up to USD 75,000 and the company being struck off the Register.
The British Virgin Islands are a classic tax-neutral jurisdiction: companies are generally not subject to taxes on profits, capital or distributions, regardless of the source of income.
The tax burden is largely limited to administrative fees and certain local taxes.
The BVI participate in international tax information exchange standards.
The cost of setting up a company in the British Virgin Islands depends on the type of company being incorporated and the nature of its business activities. The minimum service package costs USD 2,090 and includes company incorporation, Registered Agent and registered office services for one year, payment of all required government fees and charges, and an apostilled set of constitutional documents.
Yes. The British Virgin Islands (BVI) are generally considered an offshore jurisdiction. Offshore jurisdictions such as the BVI offer various tax and legal advantages to businesses, including low or zero taxation, confidentiality and privacy, and a business-friendly environment. However, in recent years, the BVI and other offshore jurisdictions have come under increased scrutiny from governments and international organisations. It is therefore important to carefully consider the potential risks and benefits before incorporating a company there.
The name of a limited liability company must include an indication of its legal form, such as “Limited”, “Corporation”, “Incorporated”, “Societe Anonyme” or “Sociedad Anonima”, or one of the permitted abbreviations, including “Corp.”, “Ltd.”, “Inc.” or “S.A.”.
The name of an unlimited company must end with “Unlimited” or “Unltd”.
The names of companies with other legal forms must also reflect their respective status. For example, a restricted purposes company may include “SPV” in its name, while a segregated portfolio company must include the words “Segregated Portfolio Company” or the abbreviation “SPC”.
Yes. BVI legislation allows a company to be incorporated without a unique commercial name. In this case, the company’s name is automatically generated and consists of the words “BVI Company Number”, followed by the company’s registration number and the standard corporate ending “Limited” or “Ltd.”
For example: BVI Company Number 2318792 Ltd.
This approach may be used where the company name is not important or where the company is established as a technical or holding structure.
When determining whether two company names are identical, the Registrar disregards the mandatory corporate ending, punctuation, the use of the definite article “the” or the indefinite articles “a” and “an” as the first word of the name, whether a word is used in the singular or plural, and the use of the word “company” or the abbreviation “co.”
For example, the following names would be considered identical:
Cute Potato Limited
Cute Potato Inc.
The Cute Potato Ltd.
Cute Potato Company Limited
If the name proposed for a company is similar to a name already appearing in the Register, the Registrar determines whether its use could cause confusion or be misleading.
The BVI Business Companies Act establishes the minimum information that must be included in a company’s constitutional documents.
The Memorandum of Association must include:
If the company is authorised to issue shares, the Memorandum must also specify:
The Articles of Association govern the company’s internal management. The Act establishes only one mandatory requirement in this respect: for a company authorised to issue shares, the Articles must provide for the issue of share certificates and specify the terms and conditions on which they are issued.
The remaining provisions of the Articles may generally be determined by the incorporators, taking into account the company’s structure and business objectives.
A proposed BVI company name must not infringe registered trade marks. However, the Registrar does not check the proposed name against the trade mark register. Responsibility for carrying out a preliminary check rests with the applicant or the company itself.
If a company infringes a trade mark or service mark registered in the BVI, the owner of the mark may bring legal proceedings against the company.
Yes. In most cases, the Memorandum and Articles of Association may be amended by a resolution of the company’s members. However, the constitutional documents may contain special entrenching provisions under the Act that restrict the procedure for making amendments.
For example, certain provisions may be made unalterable, may require a higher voting threshold for amendment, or may be subject to additional conditions.
In certain circumstances, the power to amend the constitutional documents may be granted to the directors if this is expressly provided for in the Memorandum.
However, directors may not restrict the members’ statutory right to amend the constitutional documents or impose voting requirements that are more stringent than those permitted by law.
Any amendments to the Memorandum or Articles must be filed with the BVI Registry and take effect only upon registration.
Where numerous amendments have been made, the company may also file restated constitutional documents consolidating the original text and all registered amendments.
BVI legislation does not recognise the concept of a “nominee director” who merely holds the office formally without participating in the company’s management.
Any person appointed as a director assumes the full range of duties and responsibilities imposed on directors under the BVI Business Companies Act, regardless of whether they act independently or on another person’s instructions.
Accordingly, there is no such thing as a “nominal” director appointed solely to sign documents.
A director may be held liable for breaches of the law and must ensure that the company is able to meet its obligations to creditors as they fall due. If a company becomes insolvent – for example, because it is unable to pay its debts or its liabilities exceed its assets – the directors may become subject to the provisions of the Insolvency Act, including civil and criminal liability, liability for losses and, in certain circumstances, disqualification from acting as a director in the future.
A beneficial owner of a BVI company is generally an individual who directly or indirectly owns 10% or more of the shares or voting rights in the company.
However, a person may also be recognised as a beneficial owner even without such an ownership interest if they exercise control over the company, for example, by having the right to appoint or remove directors or otherwise exercising control over the company’s management decisions.
If no beneficial owner can be identified, the individual holding the position of senior managing official is identified as the beneficial owner.
If a company considers itself tax resident in another jurisdiction and therefore outside the scope of the BVI economic substance requirements, it must provide documentary evidence of its tax residence.
This may include, for example, a tax residence certificate, together with the relevant information submitted through the Registered Agent.
The company must genuinely be subject to the tax regime of the jurisdiction in question; merely having a registered address there is not sufficient. In addition, the jurisdiction of tax residence must not be included on the EU list of non-cooperative jurisdictions for tax purposes.
If the company cannot substantiate its tax residence, it will be treated as subject to the BVI economic substance requirements and the corresponding obligations.
All BVI companies are required to report information relating to economic substance, although the content of the filing depends on the company’s activities.
Each company submits the relevant information annually through its Registered Agent. There are three main scenarios:
Even if a company is “passive” or does not conduct business activities, it is still required to make the relevant annual economic substance filing (Annual Economic Substance (ES) Declaration).
A company’s current status is confirmed by its Certificate of Good Standing. It is issued by the Registrar and confirms that the company remains registered, has paid the required annual fees and has complied with its principal statutory requirements, including mandatory filing obligations.
The Certificate of Good Standing is commonly used as evidence of a company’s existence and current status for banks, counterparties and transactions.
The BVI beneficial ownership register is not publicly available to third parties. Access to beneficial ownership information is restricted to:
Access is provided through the VIRRGIN system and is subject to statutory restrictions.
Counterparties, banks and other private persons cannot directly inspect the beneficial ownership register. Access may be obtained only through the relevant official procedures and requests by authorised authorities.
No. You cannot obtain BVI citizenship by making an investment or incorporating a company in the British Virgin Islands. The BVI do not have a citizenship-by-investment programme.
However, foreign individuals and legal entities may apply for residency in the BVI. Residency may provide certain tax and legal benefits, but it does not confer a right to BVI citizenship.