Preparing and filing dormant accounts, and conducting an audit
(accounts for dormant companies)
Price
1350 EUR

Important: The invoices may include 19% VAT on the fees for the services rendered.
Accounting & Bookkeeping
Mandatory, source documents must be kept at least 6 years
Financial Statements Preparation
Annually
Accounting Standards
International Financial Reporting Standards (IFRS)
Consolidated Financial Statements
If there are subsidiaries
Dormant Reporting Option
Yes, but with statutory audit
Filing Financial Statements with the Registry
Yes, as an attachment to the Annual Report (Form HE32)
Filing Financial Statements with the Tax Authority
No, filing a tax return is equivalent to submitting financial statements
Statutory Audit
Yes, for all companies
Dormant Status
Does not affect obligations to prepare and submit financial statements and tax returns
Corporate Tax Return
Annually, until 31 March of the second year following the tax year (for tax periods from 2026 onwards, until 31 January of the second year following the tax year)
Annual Return (HE32)
Annually to the Registrar of Companies within 28 days of the annual general meeting
Employer’s Return (TD7)
Monthly (plus annual reconciliation), if there are employees
Throughout its financial year, a company is required to maintain accounting records, recording income and expenses, bank account transactions, contracts, loans, investments, and other operations. This data forms the basis for drawing up statements and for subsequent audits.
Cyprus companies are required by 31 July of each financial year to assess their estimated profits for the current year, calculate advance corporate income tax and submit a provisional return.
Based on the provisional return, the advance tax is usually paid in two equal instalments – by 31 July and by 31 December.
In fact, companies are given one more month after the due date (i.e. 31 August and 31 January respectively) to pay the provisional tax without penalty.
If desired, the company can file the return once and pay the entire advance amount at once.
After the end of the financial year, a set of financial statements is drafted in accordance with International Financial Reporting Standards (IFRS).
The financial statements are submitted to a licensed Cyprus auditor (member of the Institute of Certified Public Accountants of Cyprus – ICPAC) for statutory audit.
The auditor checks accounting records, source documentation and draws up an auditor’s report.
A tax return is prepared based on the financial statements. It must be submitted to the Tax Department within 12 months after the end of the accounting period, i.e., before 31 December of the year following the financial year (for electronic filing, this period is extended by 3 months, to 15 months). The tax return must be certified – and in fact, is prepared – by the company’s auditor.
Changes to tax legislation which came into force on 1 January 2026 set a new deadline for companies to both file a tax return and pay tax – until 31 January of the second year following the tax year (i.e. after a maximum of 13 months).
If the advance tax amount stated in the provisional tax return:
Consequently, if no provisional tax return is filed, a penalty equal to 10% of the final tax liability will be imposed when the annual tax return is submitted.
If the applicable portion of the advance tax is not paid by the deadlines specified above, interest will be charged on the unpaid amount at the rate which is subject to annual adjustment.
In addition to tax filings, a company is required to submit the following to the Registrar of Companies:
If a company has employees, it must also submit the following to the Tax Department as an employer:
These filings are not directly related to the audit but are mandatory elements of corporate compliance.
The calculator provides an estimate of the cost of accounting and audit services for a company.
The cost depends on the company’s turnover, the number of invoices and transactions, the format in which supporting documents are provided, and the scope of services required.
The audit is conducted by an auditor certified in Cyprus.
Accounting in Cyprus is based on source documentation that substantiates the actual execution of transactions. Such documentation includes contracts, invoices, certificates of work performed, delivery notes, bank statements, payment orders, and other documents verifying the company’s transactions.
Accounting records must reflect:
Accounting records must enable to:
The responsibility to maintain accounting records rests with company directors. It is their duty to take ‘reasonable measures’ to organise and establish this process. Failure to maintain accounting records, keeping records non-compliant with the requirements, or failing to fulfil the obligation to retain records constitutes a criminal offence (if the director is found guilty), punishable by imprisonment for up to 1 year and/or a fine of up to CYP 1,000. However, in their defence, a director may argue that they had ‘reasonable grounds’ to believe that a competent and reliable person such as an external accountant was responsible for ensuring compliance with these requirements and was capable of properly performing this duty.
Under Cyprus law, the responsibility for preparing financial statements lies with the company’s directors. The directors must ensure that a full set of financial statements is prepared annually for each financial year, in accordance with International Financial Reporting Standards.
This duty is a statutory requirement and cannot be delegated to third parties, even if the statements are effectively prepared by accountants or external specialists.
The financial statements of Cyprus companies are drawn up in accordance with the existing International Financial Reporting Standards (IFRS), which have been adopted by more than 120 countries.
The objective of IFRS is to ensure the comparability of financial statements across companies from different countries, providing international investors and creditors with an accurate and transparent view of a company’s financial position, financial performance, and cash flows. IFRS are based on principles rather than rigid, formal rules, prioritising substance over form, and are designed to reflect the true economic essence of transactions, rather than merely their legal form.
A Cyprus company financials must provide a ‘true and fair view’ of its position. This is achieved through the diligent application of IFRS. If compliance with IFRS alone is insufficient to provide a true and fair view, additional information must be disclosed in the notes to the financial statements.
Presenting or publishing financial statements that fail to give a true and fair view of a company’s financial position constitutes a violation, and a director who fails to take all reasonable steps to ensure compliance with these requirements may be liable, on conviction, to 1-year imprisonment and/or a fine of up to CYP 10,000.
In February 2026, amendments to the Companies Law were published, introducing a specialised simplified Financial Reporting Standard for Small Entities (FRS for SEs).
The standard was developed by the Institute of Certified Public Accountants of Cyprus (ICPAC) in accordance with the EU Accounting Directive 2013/34/EU. Its purpose is to reduce the administrative burden that full compliance with IFRS imposes on small businesses, while ensuring that regulatory requirements and transparency are maintained.
Although the regulatory framework has been established, the standard currently awaits final approval by the Minister of Finance. The implementation timeline will be announced at a later date.
The use of the simplified reporting standard is voluntary. It may be applied only by small companies, i.e., companies that, as of the balance sheet date, meet at least two of the following three criteria:
The simplified reporting regime may also be used by small groups of companies, provided they meet similar size thresholds on a consolidated basis.
Regardless of the size of a company or group of companies, this reporting standard does not apply to public-interest entities, companies listed on stock exchanges outside the EU, banks, insurance companies, or large regulated firms.
Financial statements in Cyprus are prepared in euro (EUR) – the official currency, as Cyprus is a member of the eurozone. Companies generally use the euro as their functional and reporting currency, in compliance with International Financial Reporting Standards (IFRS) and local corporate law. Foreign currencies are converted into euro for reporting purposes.
If a company’s functional currency is not the euro, it must disclose the reasons for this; it may also be required to present its final financial statements in euro or to disclose the conversion method used.
Although companies are permitted to use a currency other than the euro as their functional currency, it is standard practice to submit all mandatory filings to the Registrar of Companies in euro.
The first financial period begins on the company’s incorporation date and may last for a maximum of 18 months. It is common practice to set the end date as 31 December – the end of the calendar year, in order to align the financial reporting period with the tax reporting period for corporate income tax, which is the calendar year.
Therefore, in practice, if a company is incorporated:
All subsequent accounting periods span 12 months and coincide with the calendar year.
An overview of the company’s activities.
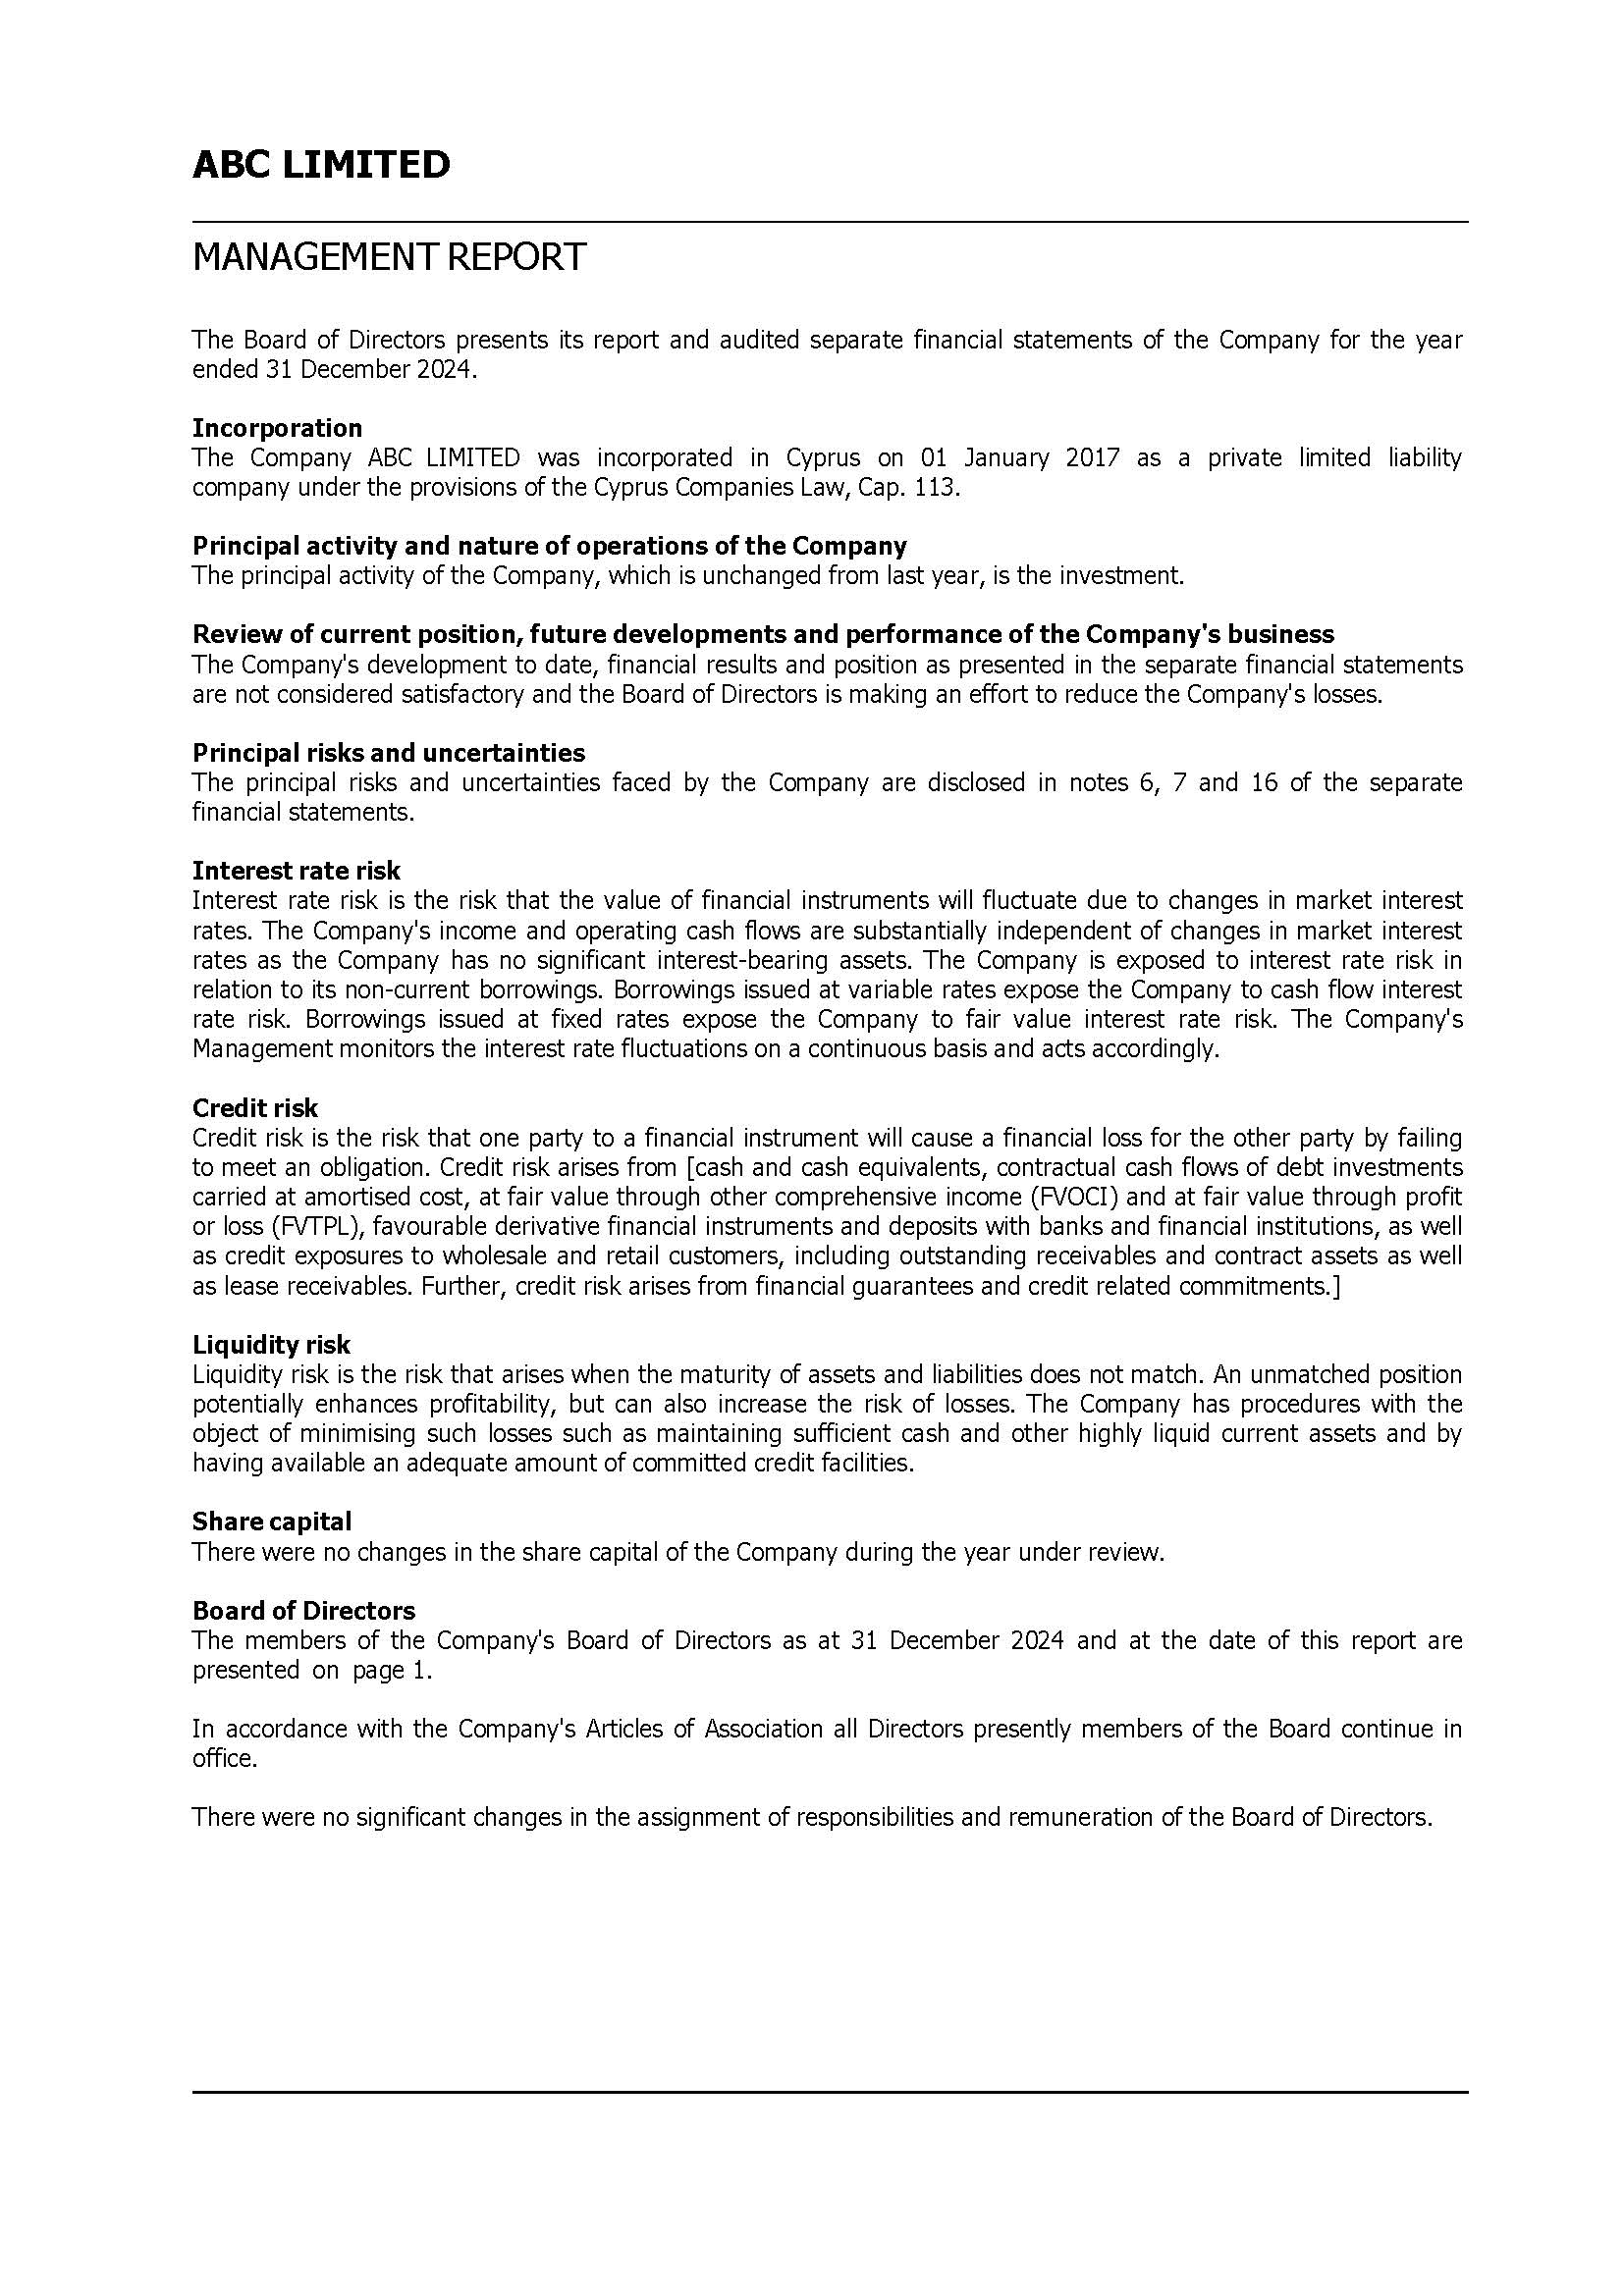
Confirms that the financial statements provide a true and fair view of the company’s financial position.
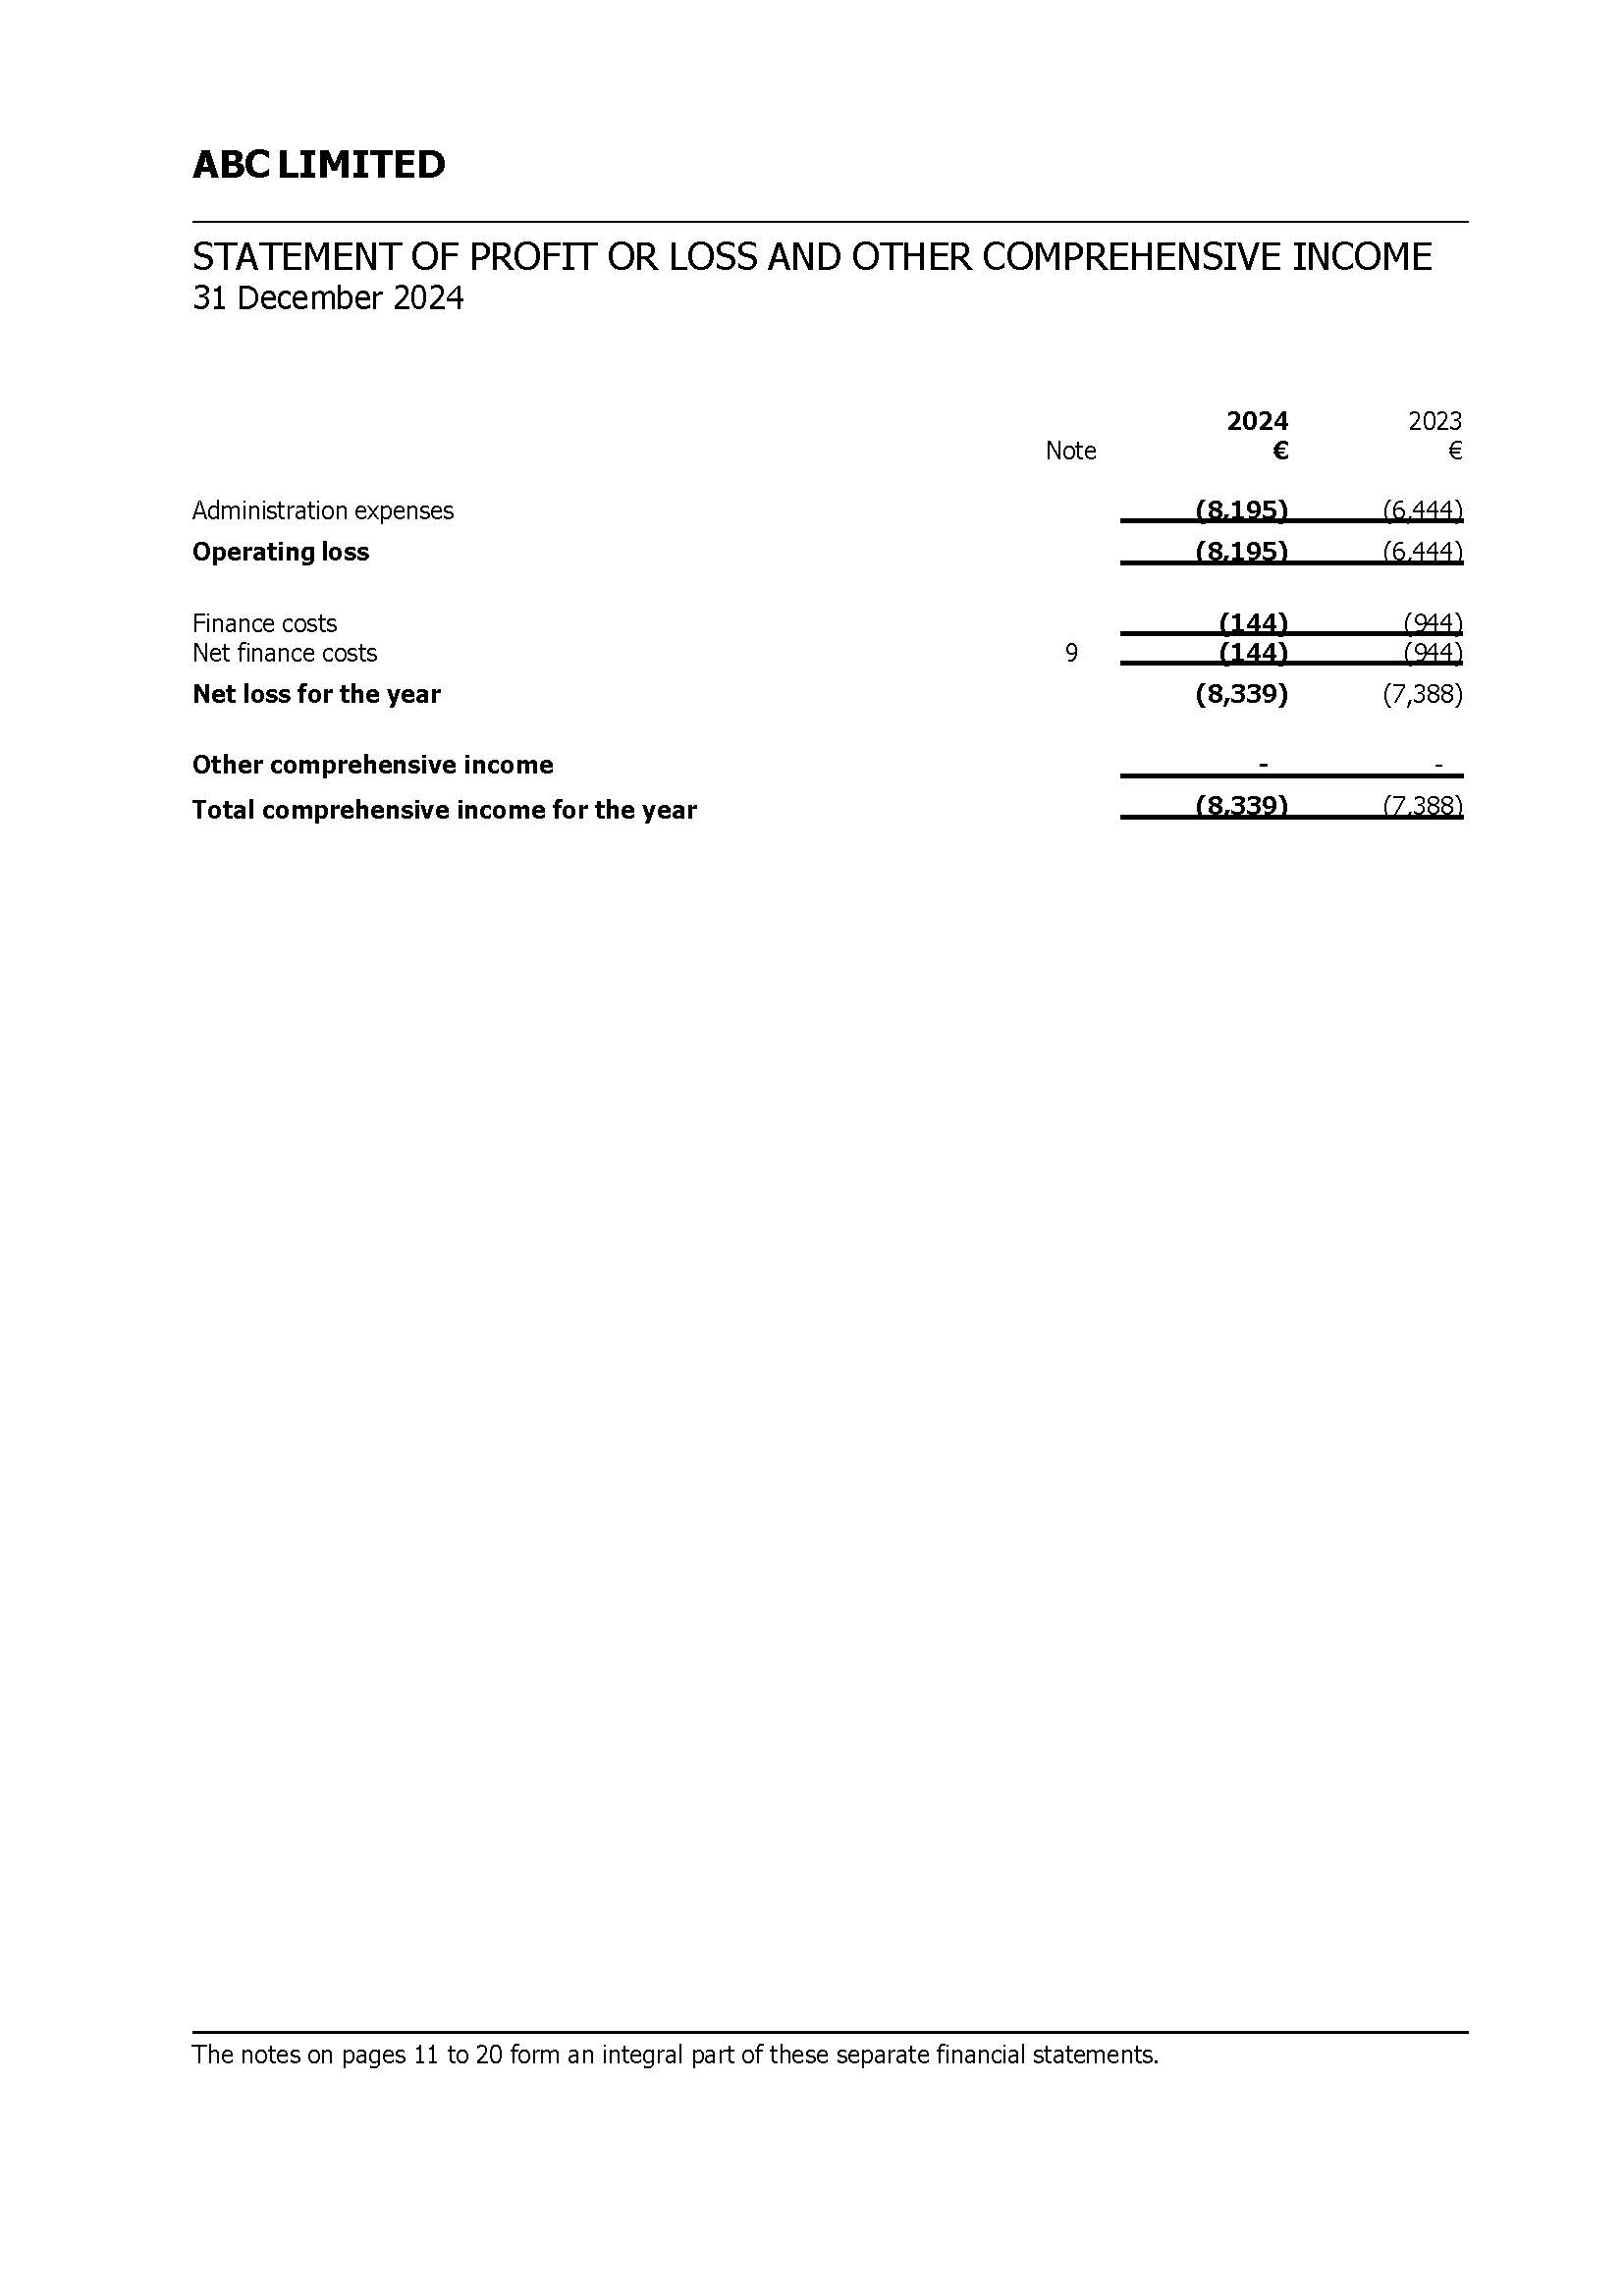
Provides a summary of income, expenses, and net profit or loss in the accounting period.
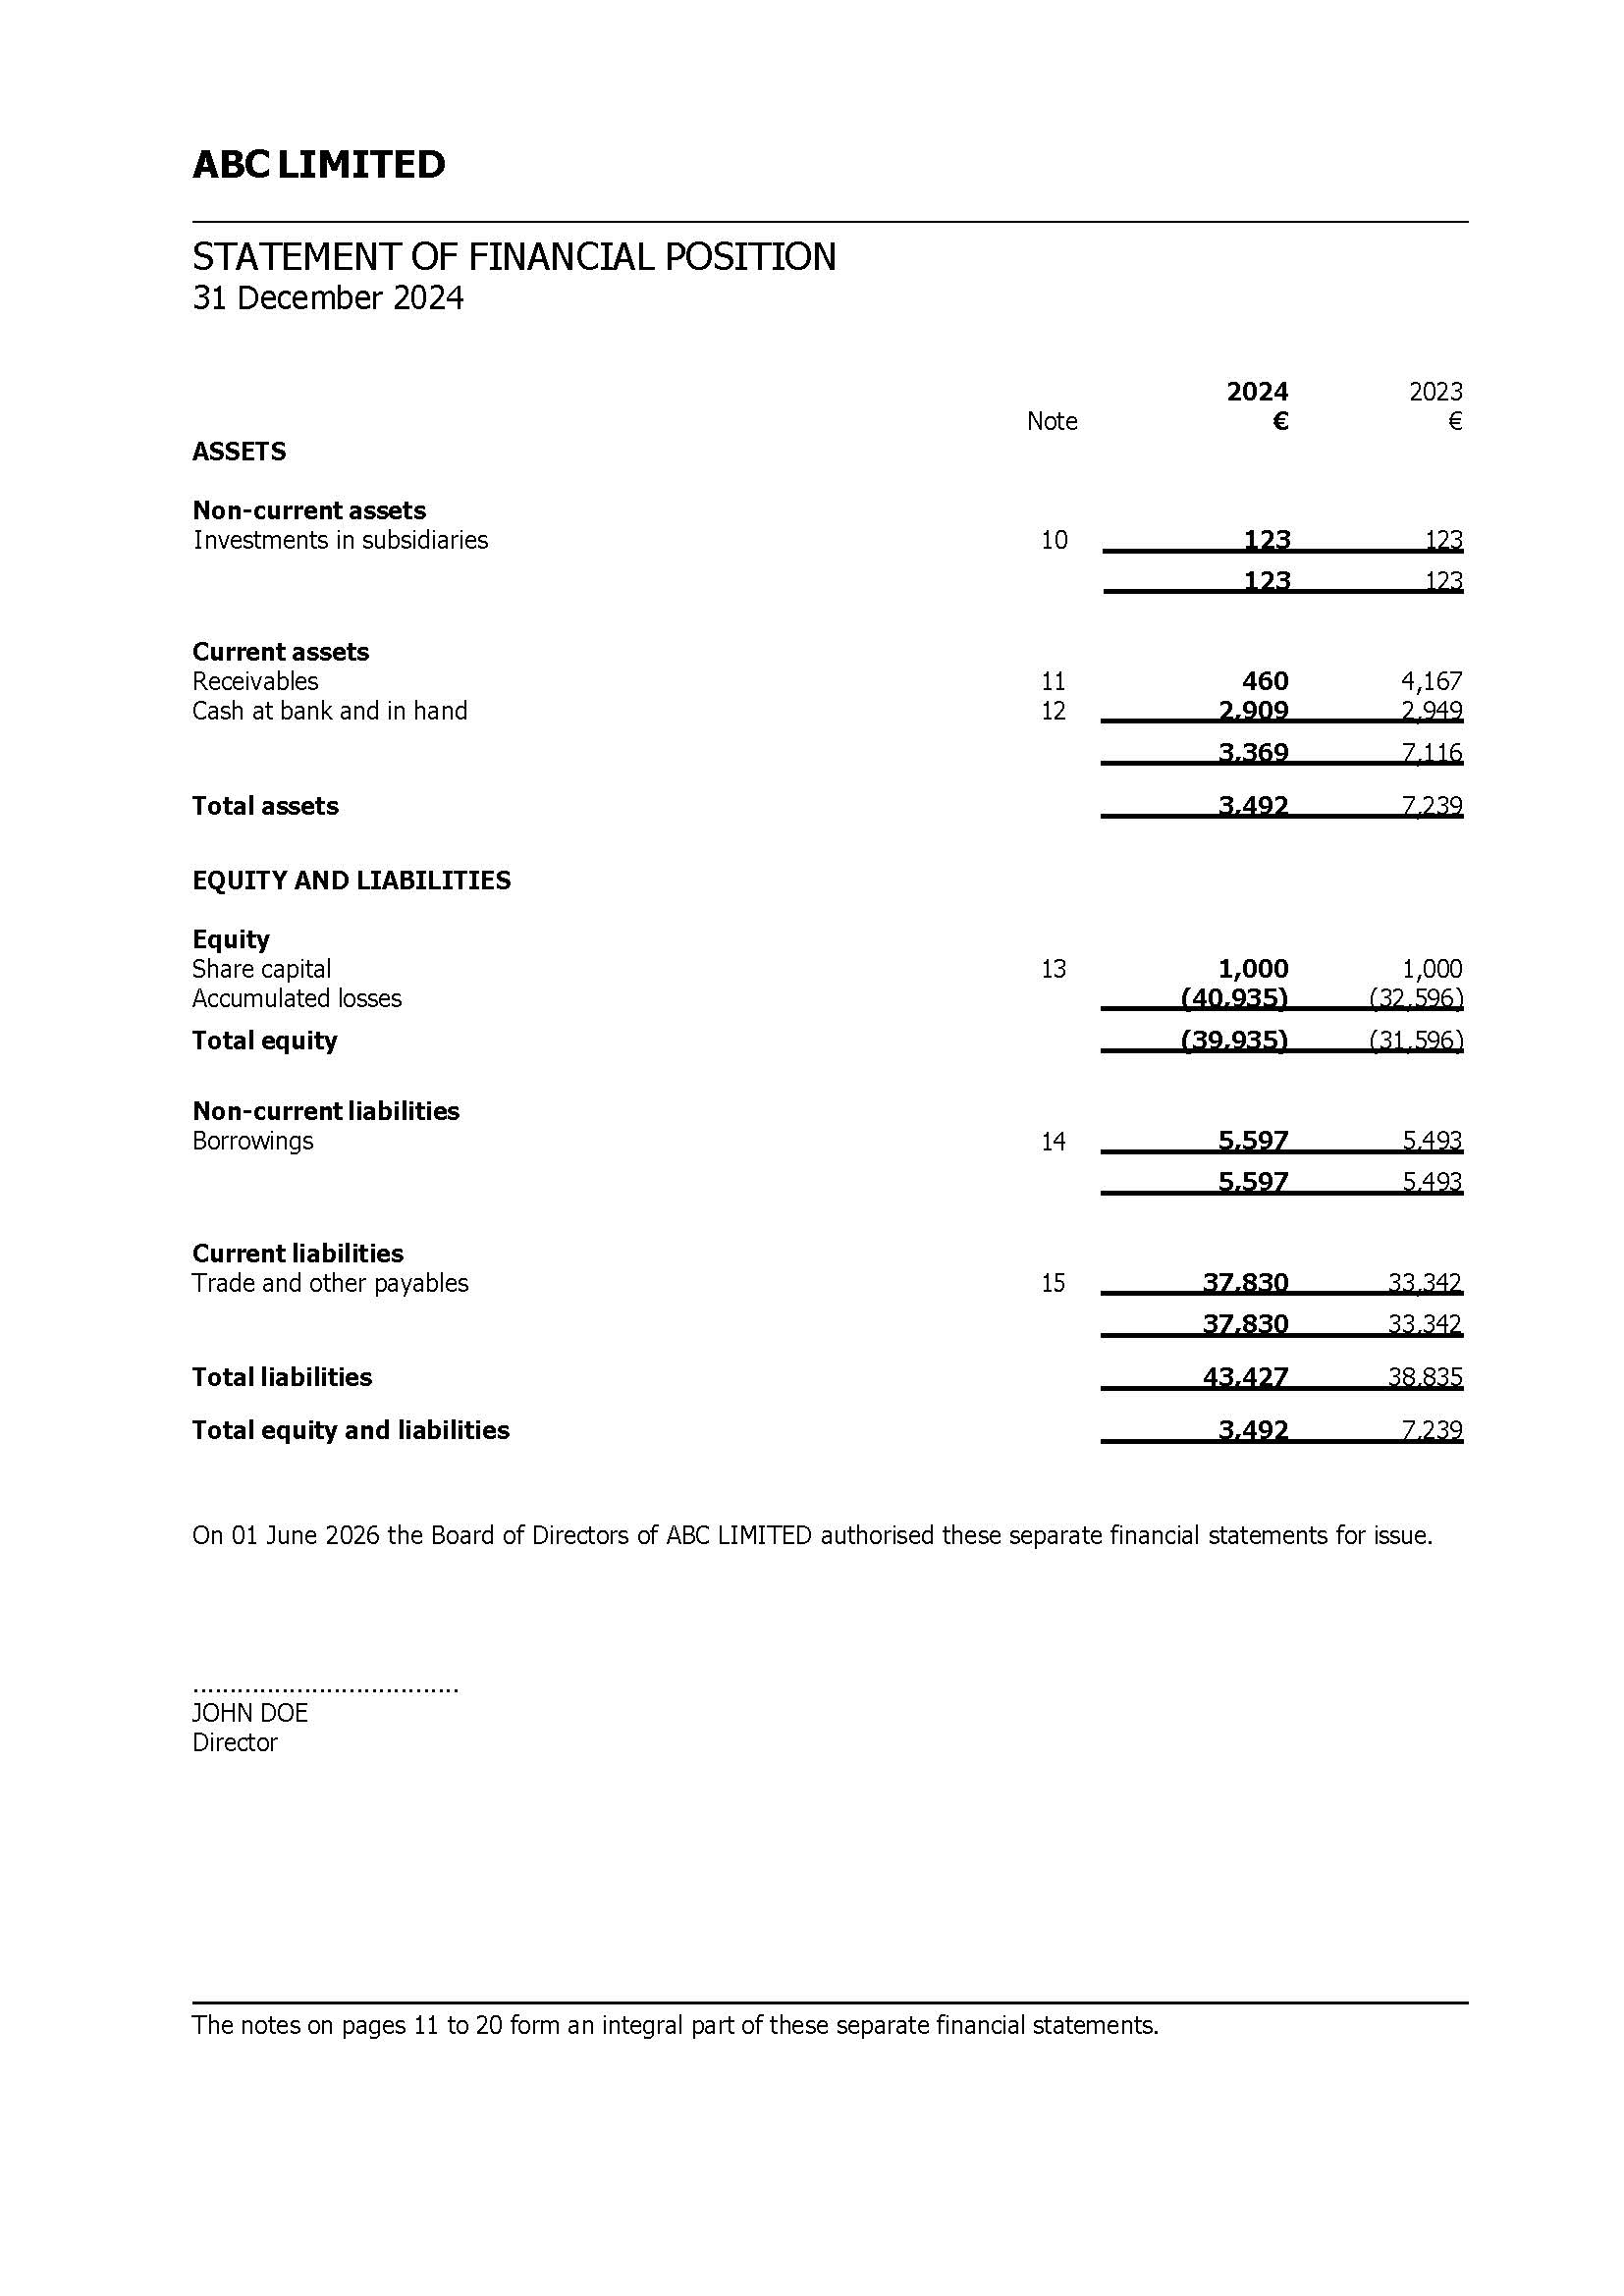
Effectively a balance sheet. Provides detailed information on assets, liabilities, and equity as of the year-end.
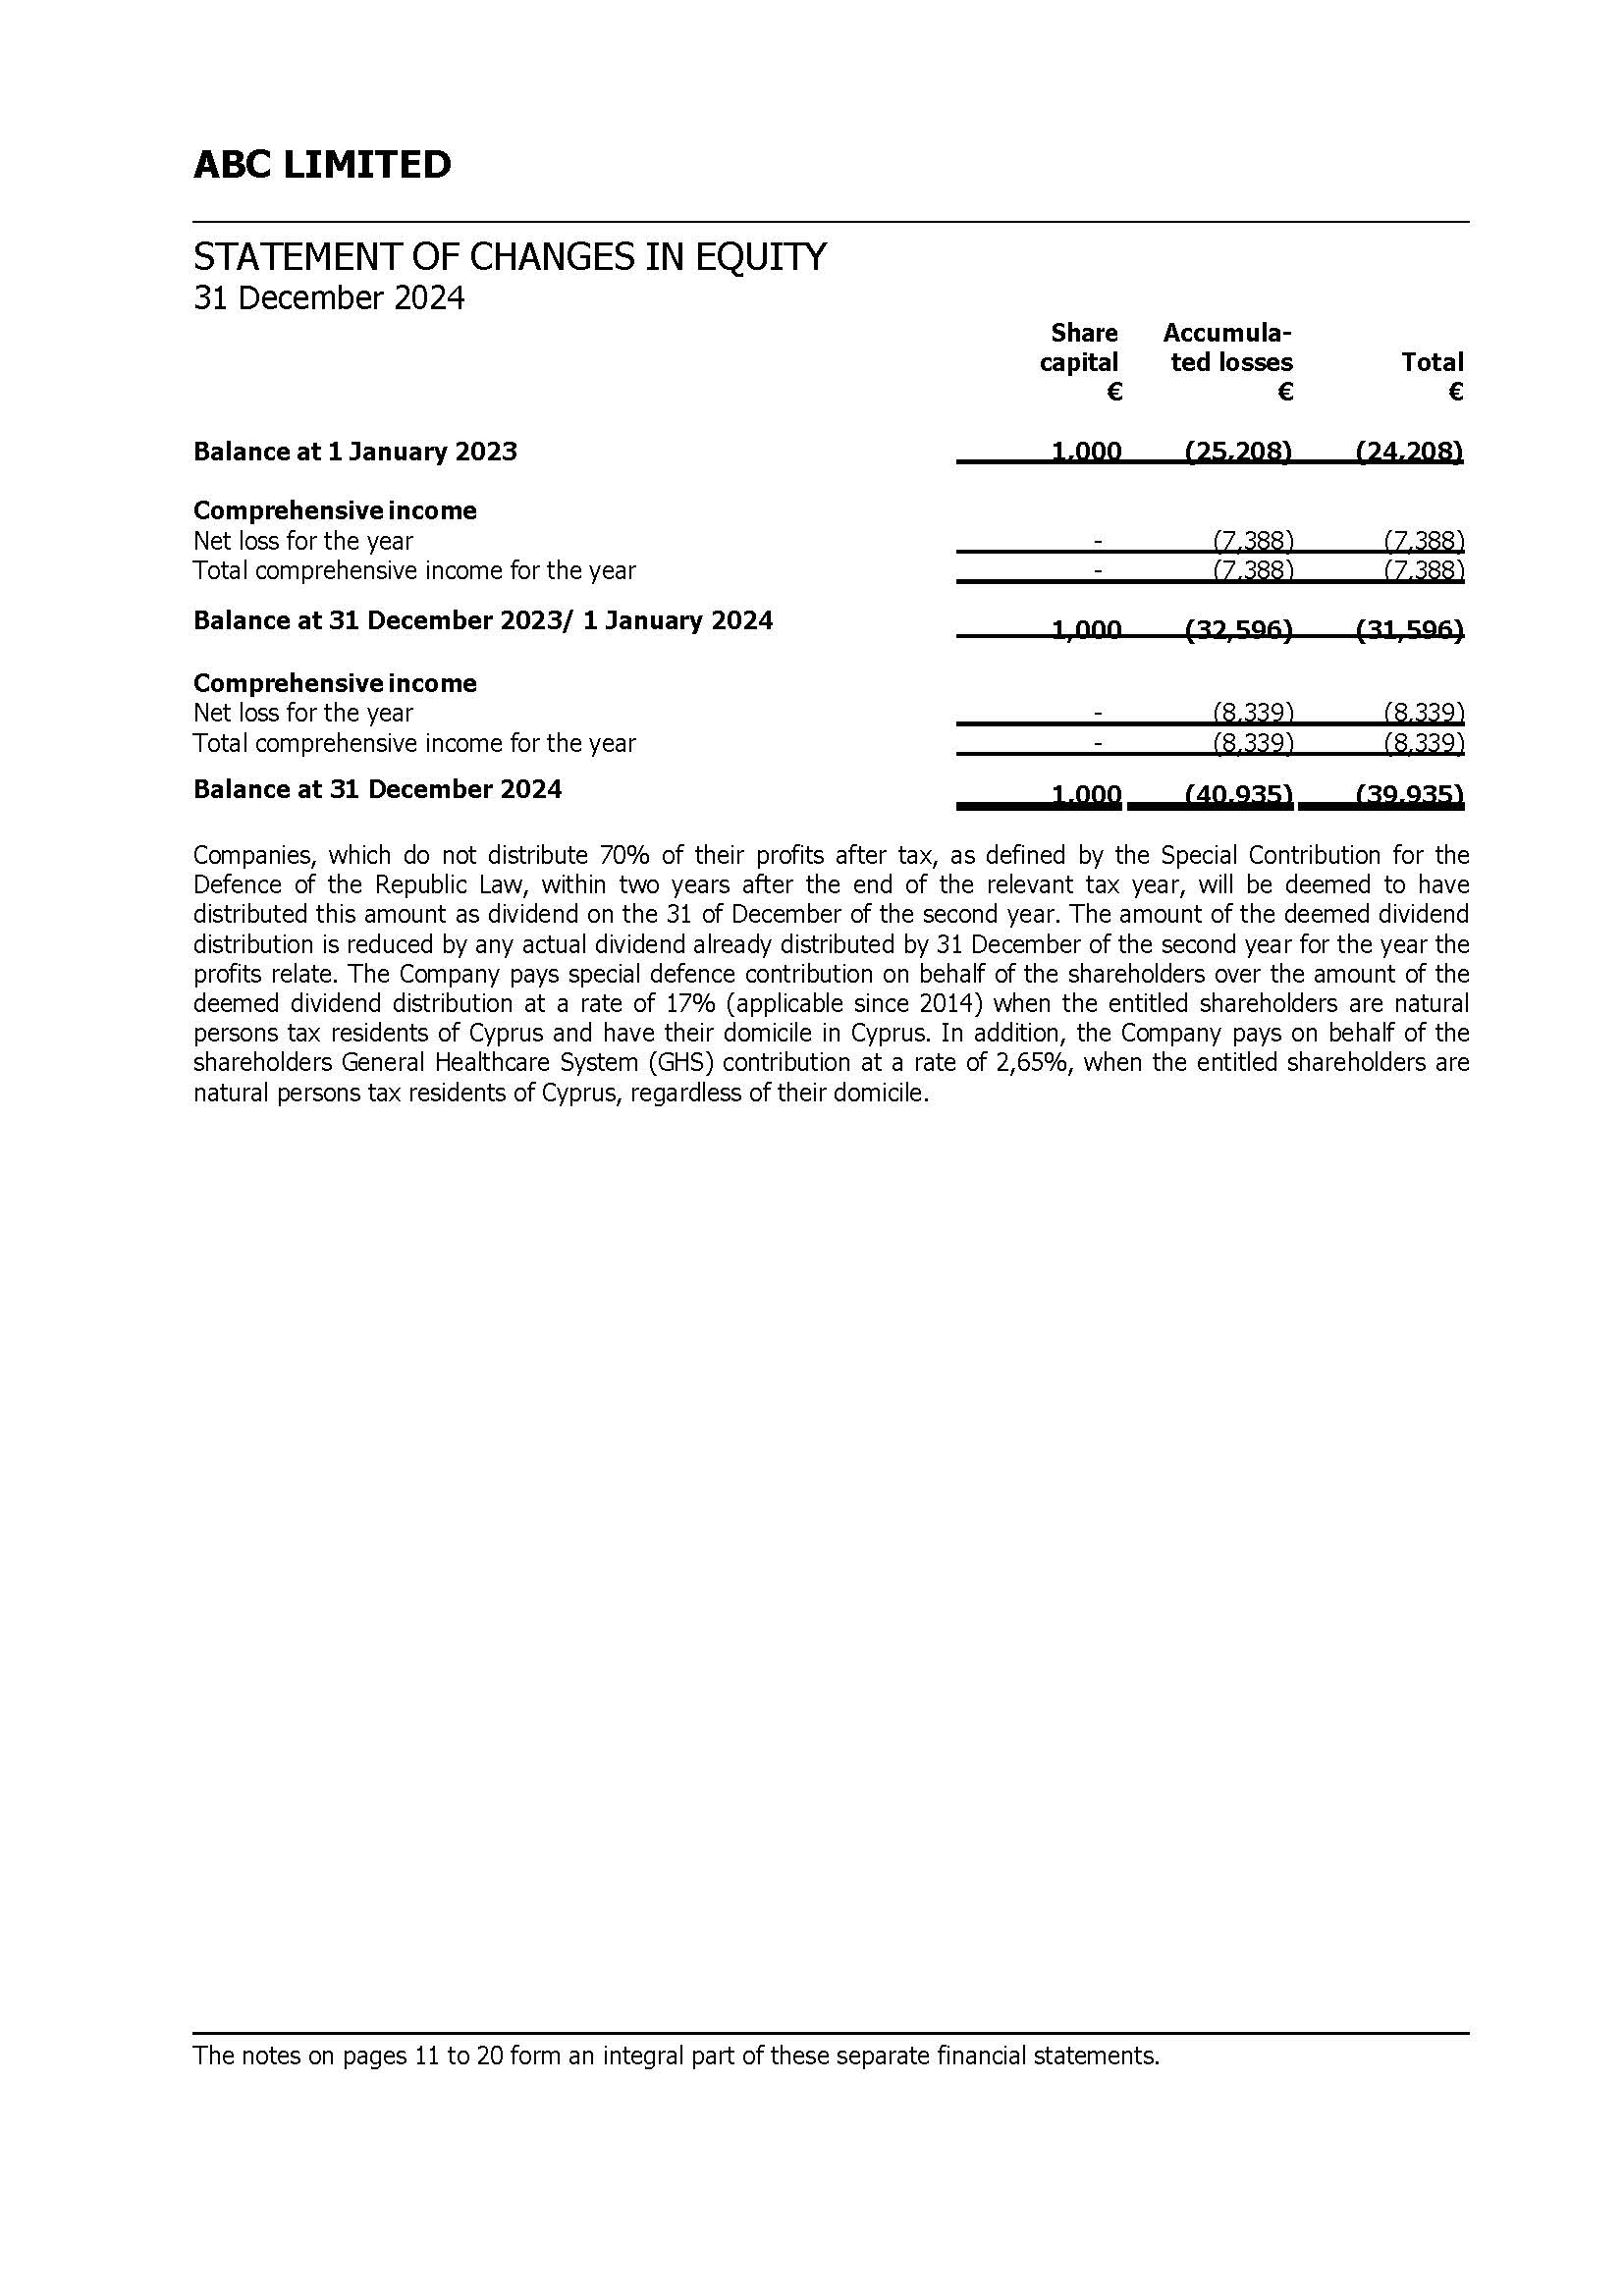
Outlines changes in equity over the accounting period.
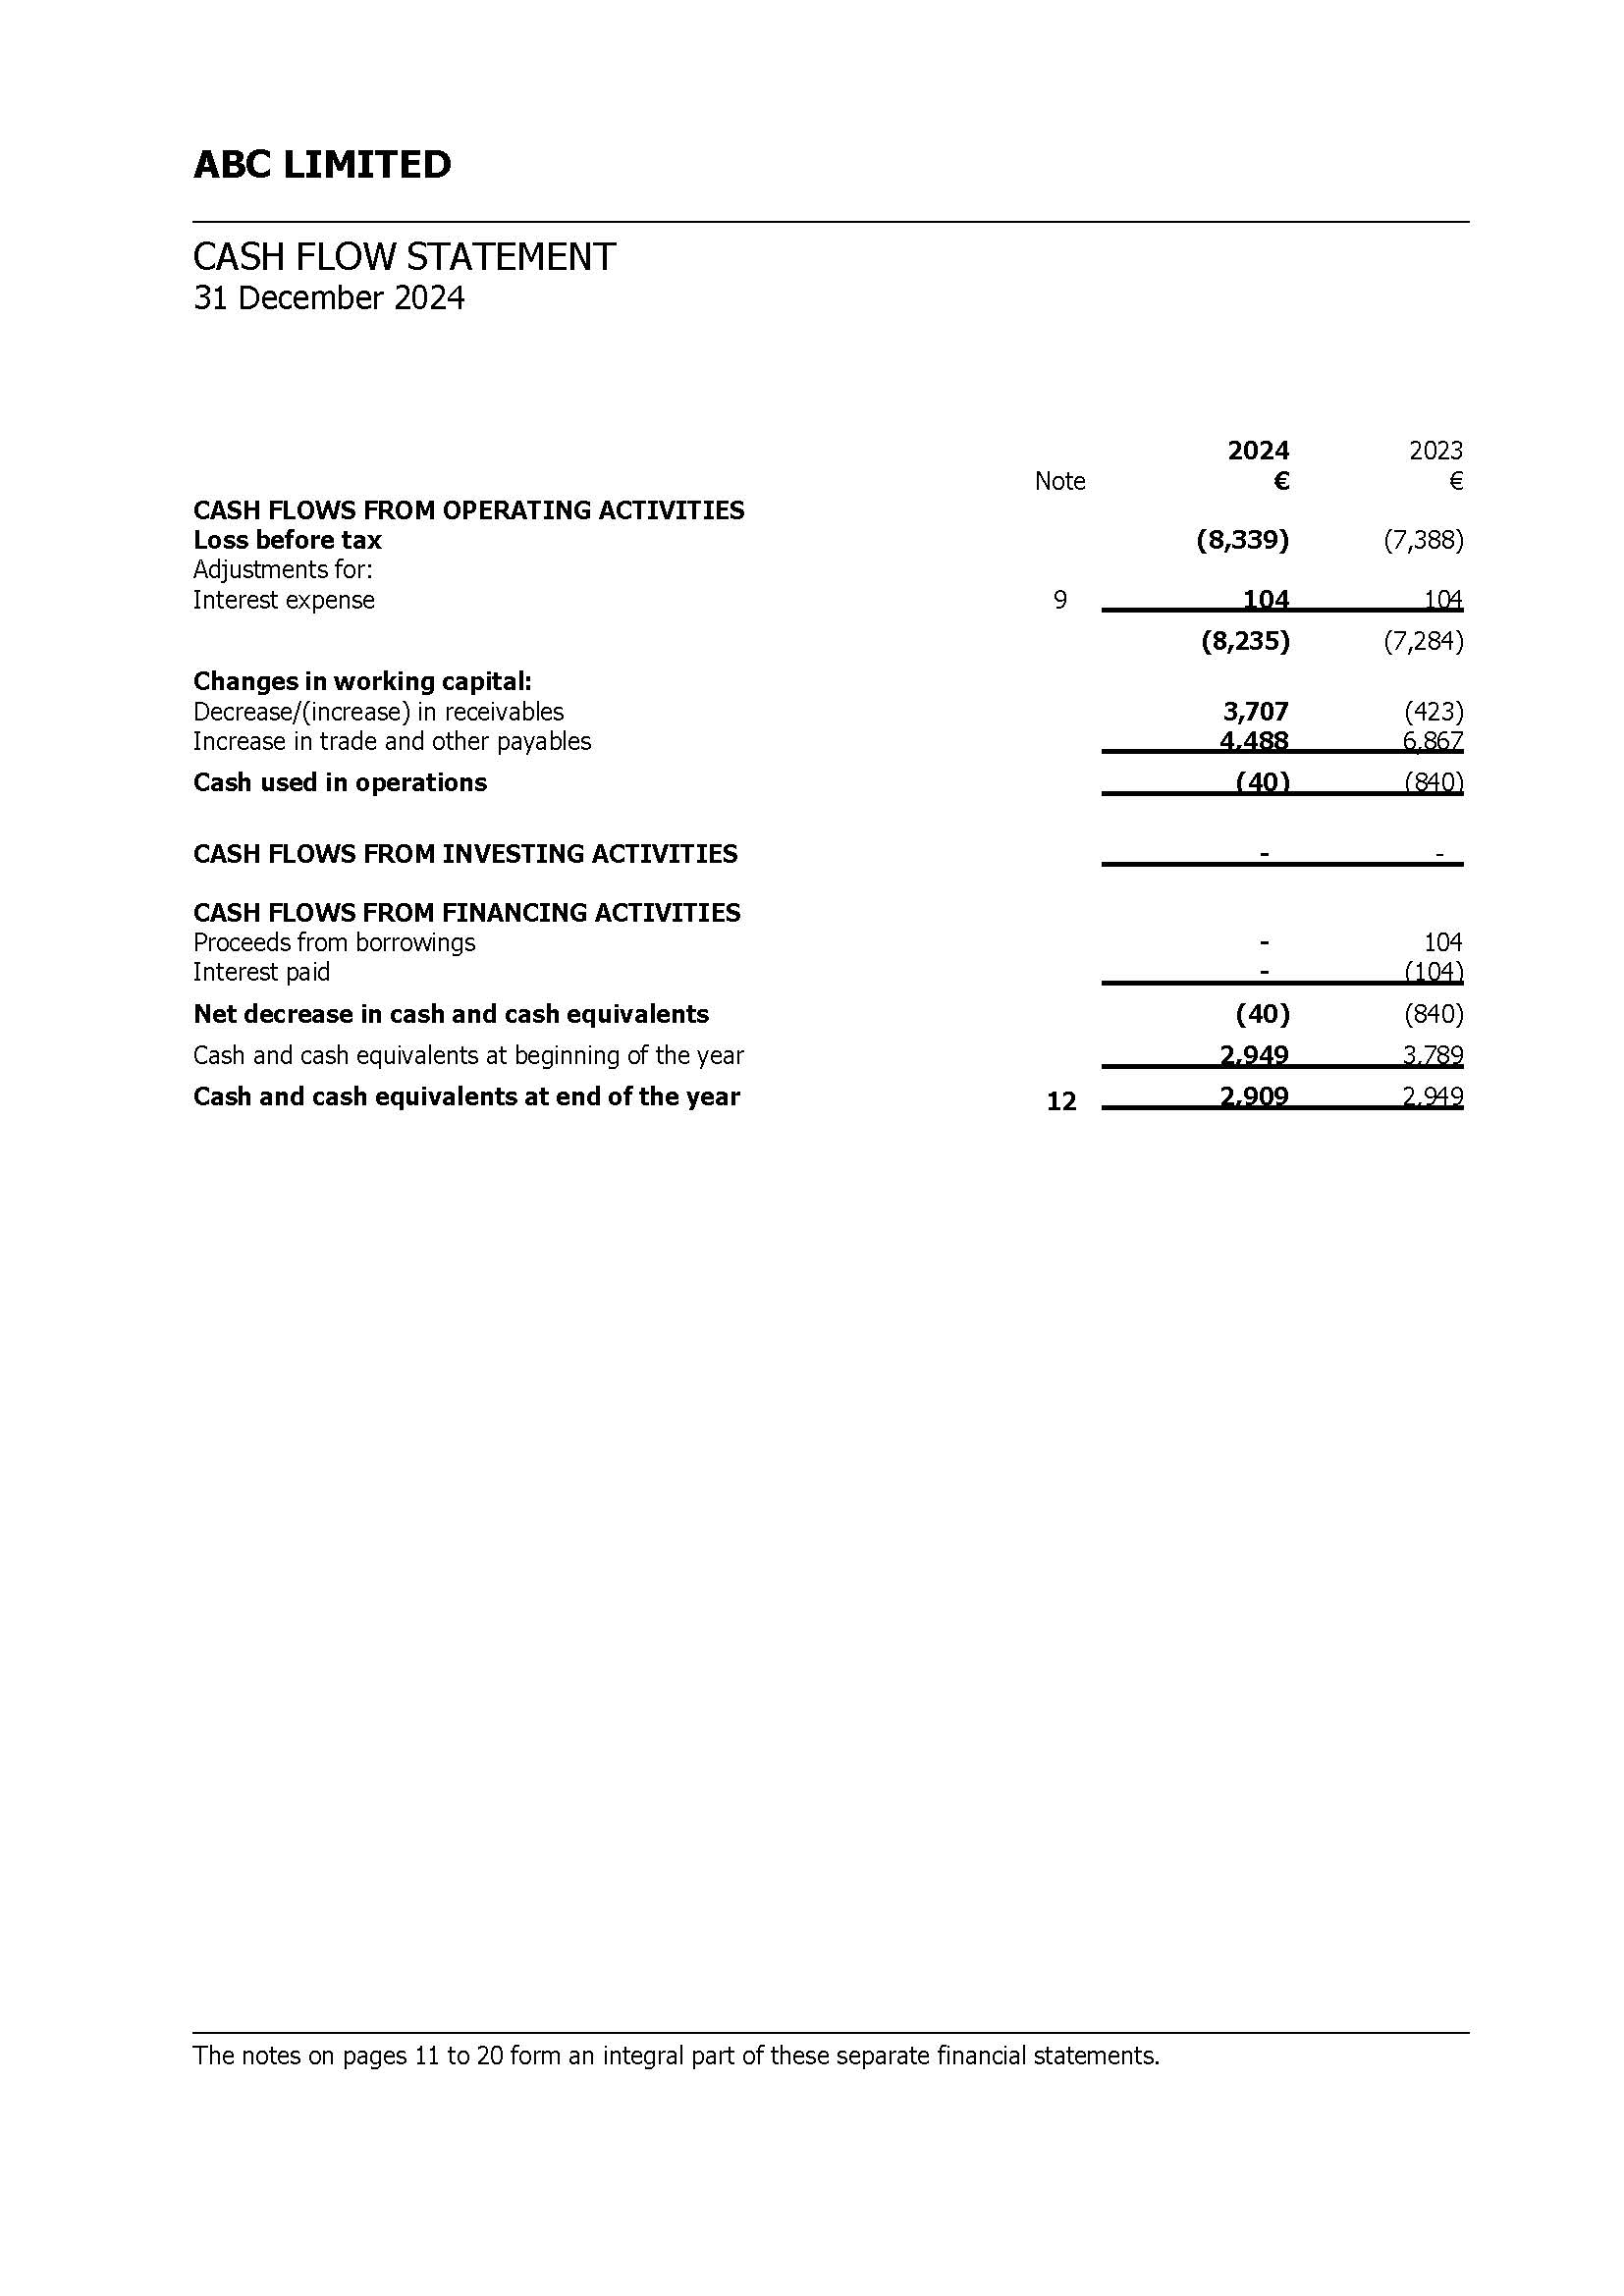
Tracks the movement of cash, including operating, investing, and financing activities.
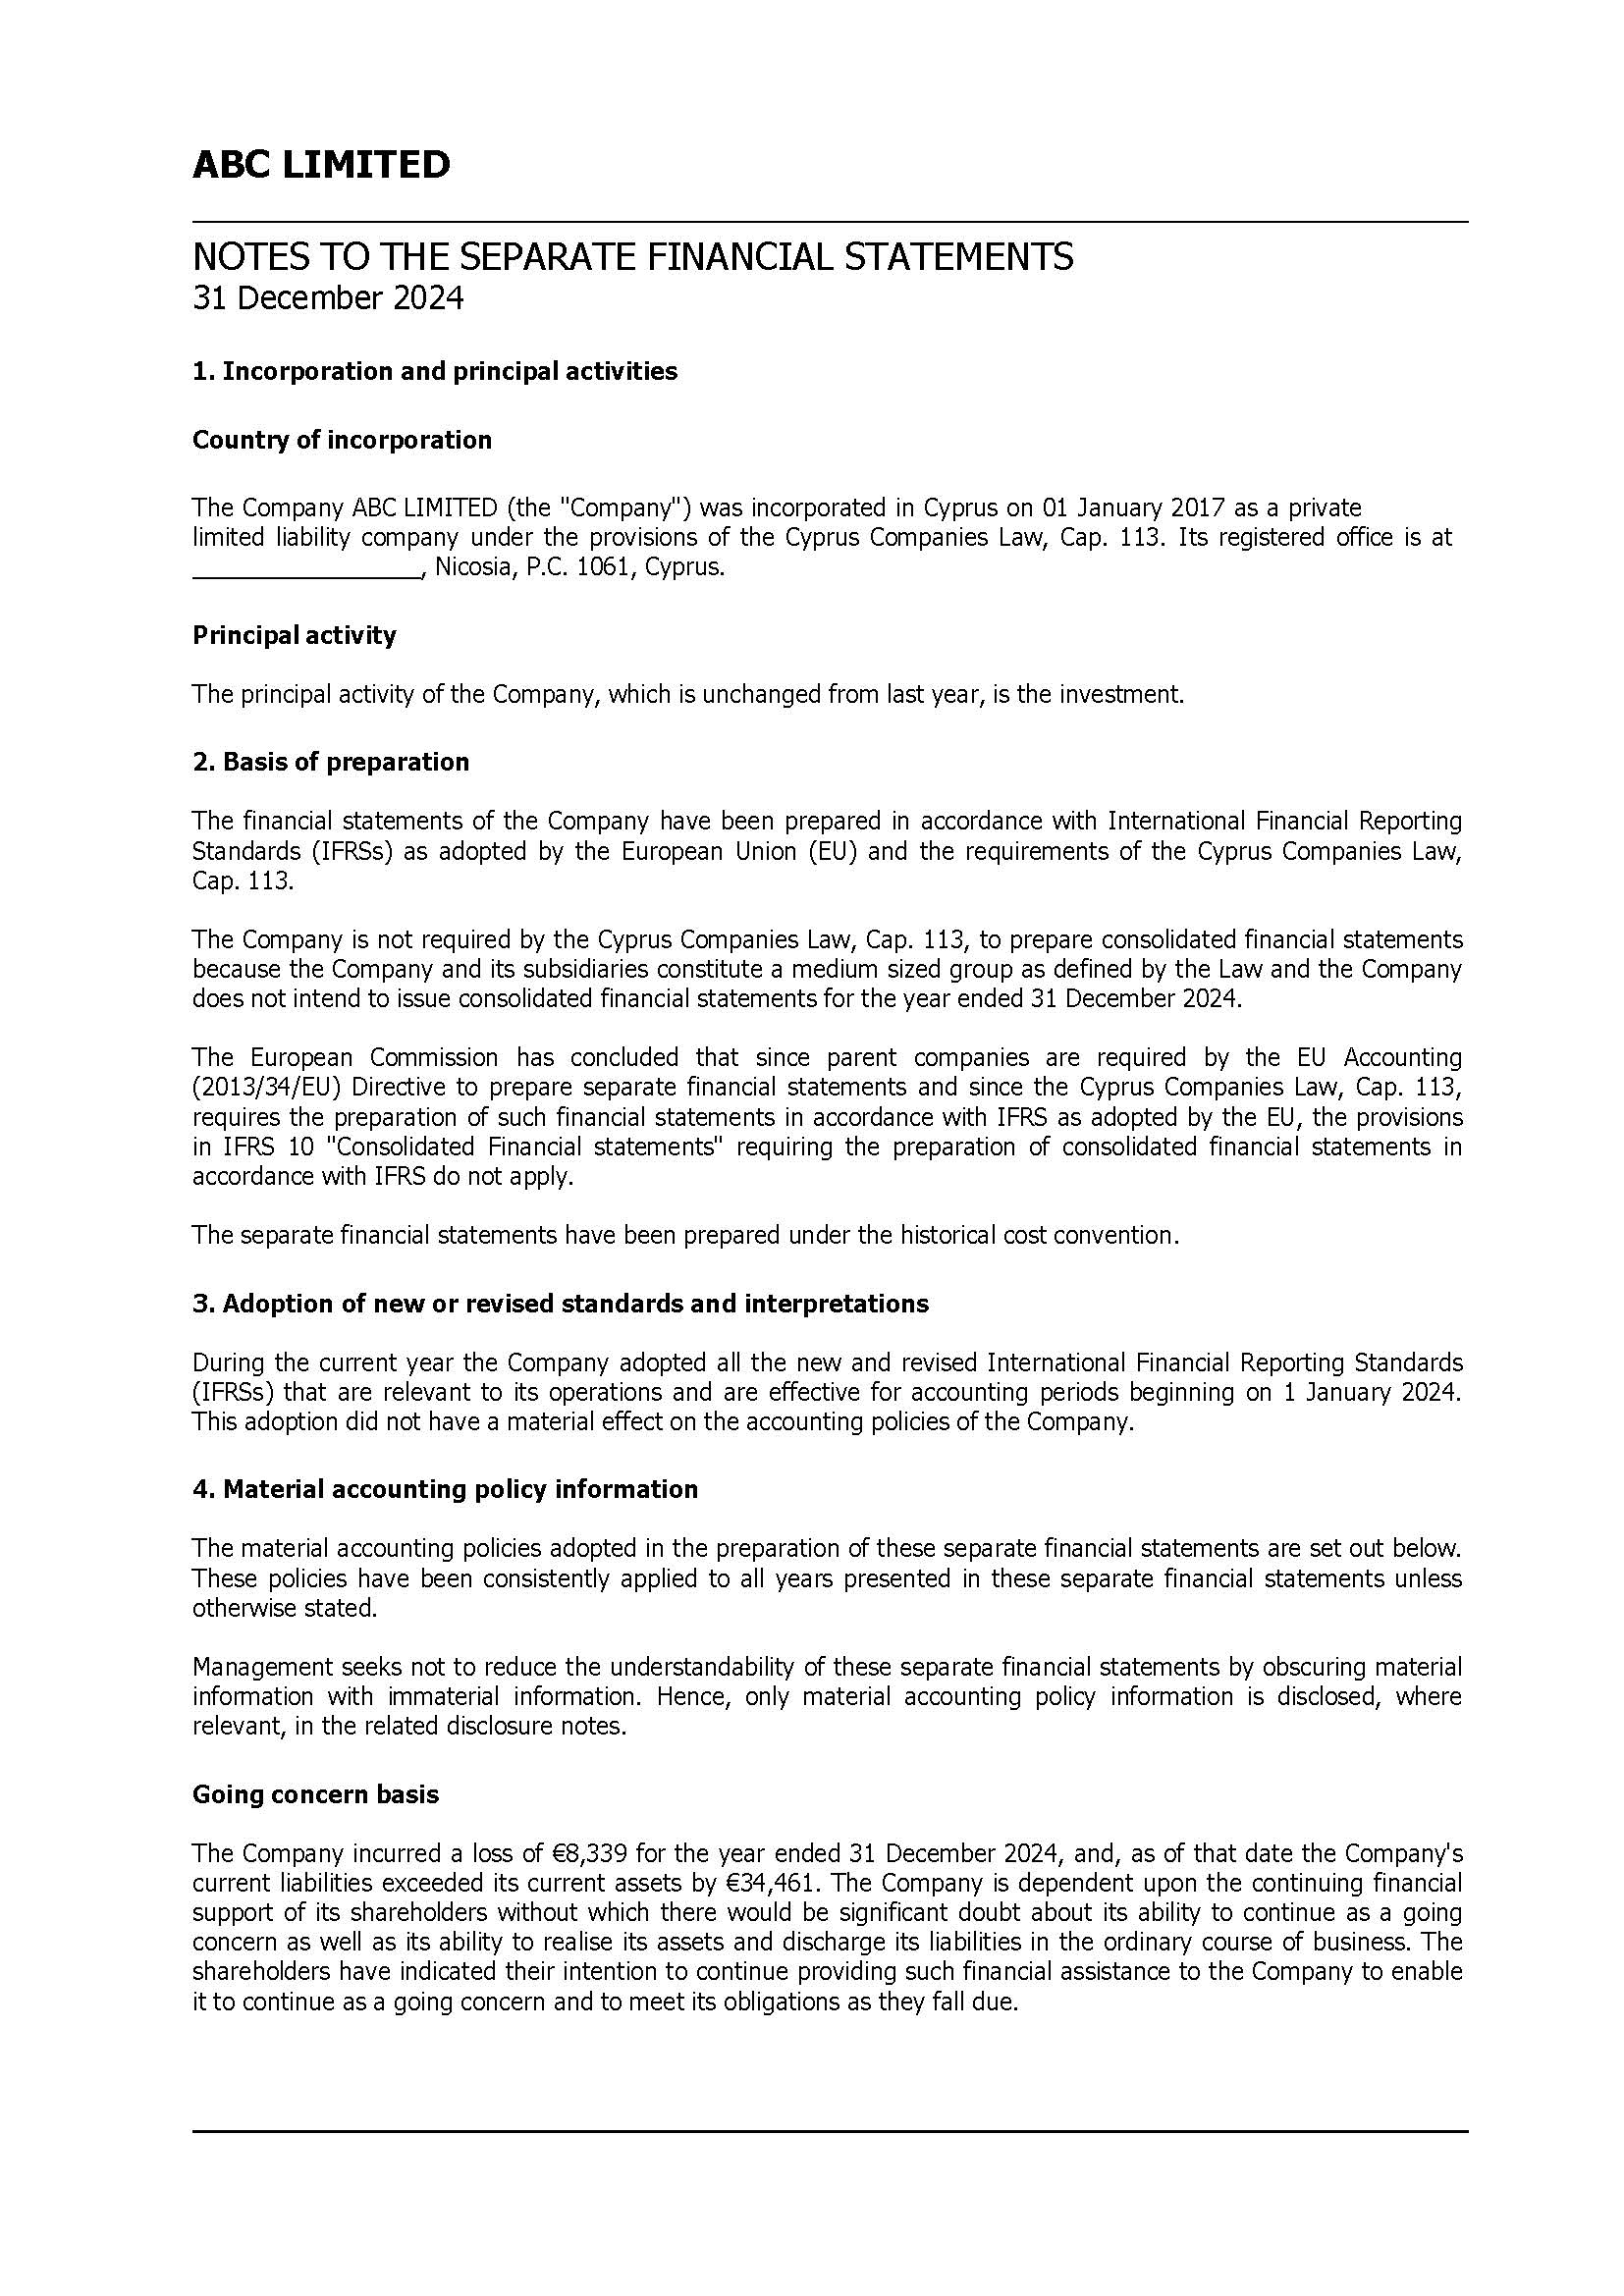
Provides explanations of accounting policies and a detailed breakdown of the figures.
A Cyprus company with subsidiaries must consolidate its financial statements with those of its subsidiaries in accordance with International Financial Reporting Standards. The consolidated financial statements of a group must reflect the combined assets, liabilities, equity, income, expenses, and cash flows of the parent company and its subsidiaries, as they constitute a single economic entity.
A company is considered a subsidiary of another company if the latter:
Control over the composition of the board of directors is defined as the ability to appoint or remove all or a majority of board members without the consent or approval of any other person.
The following entities are exempt from preparing consolidated financial statements:
The exemption does not apply in cases where an associated company is a public-interest entity, or where the preparation of the companies’ consolidated financial statements is governed by legislation other than the Companies Law.
Under the Cyprus Companies Law, all companies registered in this jurisdiction are required to conduct an annual audit, regardless of their size or whether they have generated a profit.
Even if a company has not done any business in the accounting period and is considered a ‘dormant company’, its financial statements must still be audited.
The primary objective of an audit is to confirm that a company’s financial statements accurately reflect its financial position and have been prepared in accordance with the applicable financial reporting standards.
Statutory audits can only be conducted by individuals or entities licensed under the Auditors and Statutory Audits of Annual and Consolidated Accounts Law 2009. These include auditors and audit firms that have been approved and registered by the Institute of Certified Public Accountants of Cyprus (ICPAC).
Auditors bear professional and legal responsibility for the accuracy and reliability of their audit opinion.
An auditor must act independently of the audited company and is required to adhere to professional auditing standards, including the International Standards on Auditing (ISA).
Initially, the auditor examines the company’s business structure, the nature of its operations, revenue sources, bank accounts, and accounting system. This enables the auditor to identify high-risk areas and determine the scope of necessary verification.
Next, the auditor reviews source documents and accounting records. They analyse bank statements, contracts, invoices, payment documents, and other supporting records to ensure that all transactions are accurately reflected in the accounting system.
The following aspects get the auditor’s particular attention:
Where necessary, the auditor may request additional documents or explanations from the company’s director or accountant.
Upon completion of the audit, the auditor issues a report expressing a professional opinion on the accuracy of the financial statements.
Based on their findings, the auditor issues a report, which may contain various types of opinions.
The most favourable outcome is an unqualified (or ‘clean’) opinion, which confirms that the financial statements fairly present the company’s financial position and comply with applicable standards.
In certain cases, the auditor may issue a qualified opinion. This occurs, for example, if a company has failed to prepare consolidated financial statements despite having subsidiaries, or if specific information was unavailable to the auditor.
A qualified opinion does not prevent the filing of financial statements, though banks or investors may raise questions.
In rare instances, an adverse opinion or a disclaimer of opinion may be issued if the auditor is unable to obtain sufficient evidence of reliability of the financial statements. Such situations are considered serious violations and require the financial statements to be revised.
Effective 1 January 2023, Cyprus has eliminated the requirement for a full audit for micro-enterprises, instead introducing a simplified format – the International Standard on Review Engagements (ISRE).
It is important to note, however, that this does not constitute an exemption from having financial statements reviewed by a qualified, certified professional; rather, it is merely a simplification of the procedure.
ISA vs. ISRE
An audit engagement and a review engagement are both aimed at confirming the reliability of financial statements, but they differ in terms of depth and the level of assurance provided by the resulting report. The objective of an audit is to form a well-founded opinion on whether the financial statements fairly and accurately reflect the company’s operations and financial position. The objective of a review engagement is to determine whether any circumstances have come to light that would indicate the financial statements do not comply with the applicable IFRS.
Thus, an audit provides reasonable (high) assurance that the financial statements, in all material respects, accurately reflect the company’s financial position. This is also reflected in the auditor’s wording: ‘the financial statements give a true and fair view’. In contrast, a review engagement provides limited assurance; while it does not guarantee the complete absence of errors in the financial statements, it confirms that no material misstatements have been identified, typically phrased as: ‘nothing has come to our attention that causes us to believe that the financial statements are not presented fairly’.
The level of assurance is determined, among other factors, by the extent of the work performed by the professional. Audits involve in-depth tests, including physical inspection, third-party confirmations, and internal control testing. In contrast, a review engagement primarily relies on analytical procedures and inquiries directed at the company’s management.
Because it is more labour-intensive, an audit is a more complex and costly procedure; a review engagement, being simpler and more cost-effective, helps reduce the administrative burden on small businesses.
Who is eligible to use ISRE
The option to replace an audit with a review engagement (ISRE) is available to companies that meet the following criteria:
A group of companies that is exempt from the requirement to prepare consolidated financial statements may also opt for an ISRE, provided that the group, together with its subsidiaries, does not exceed (or has ceased to exceed) the relevant thresholds for at least two consecutive financial years.
Although the ISRE does not result in a full audit report, it must still be conducted exclusively by a certified auditor or an audit firm.
Beyond meeting regulatory requirements, an audit holds significant practical value for a company’s operations. Audited financial statements may be required for:
Failure to provide audited financial statements can significantly limit a company’s ability to do business and interact with financial institutions.
Financial statements, accompanied by an independent auditor’s report, are submitted to the Registrar of Companies as an attachment to the Annual Return (Form HE32).
The Tax Return (Form IR4) is prepared based on these financial statements and submitted to the Tax Department; however, the financial statements themselves are generally not sent to the tax authorities. For the purposes of the tax return, providing the full information required in Part 2 of Form IR4 (Balance Sheet, Profit and Loss Statement, and Notes to the Financial Statements) is considered equivalent to submitting the financial statements. Nevertheless, the Tax Department reserves the right to request the financial statements themselves, and the company is obligated to provide them if asked.
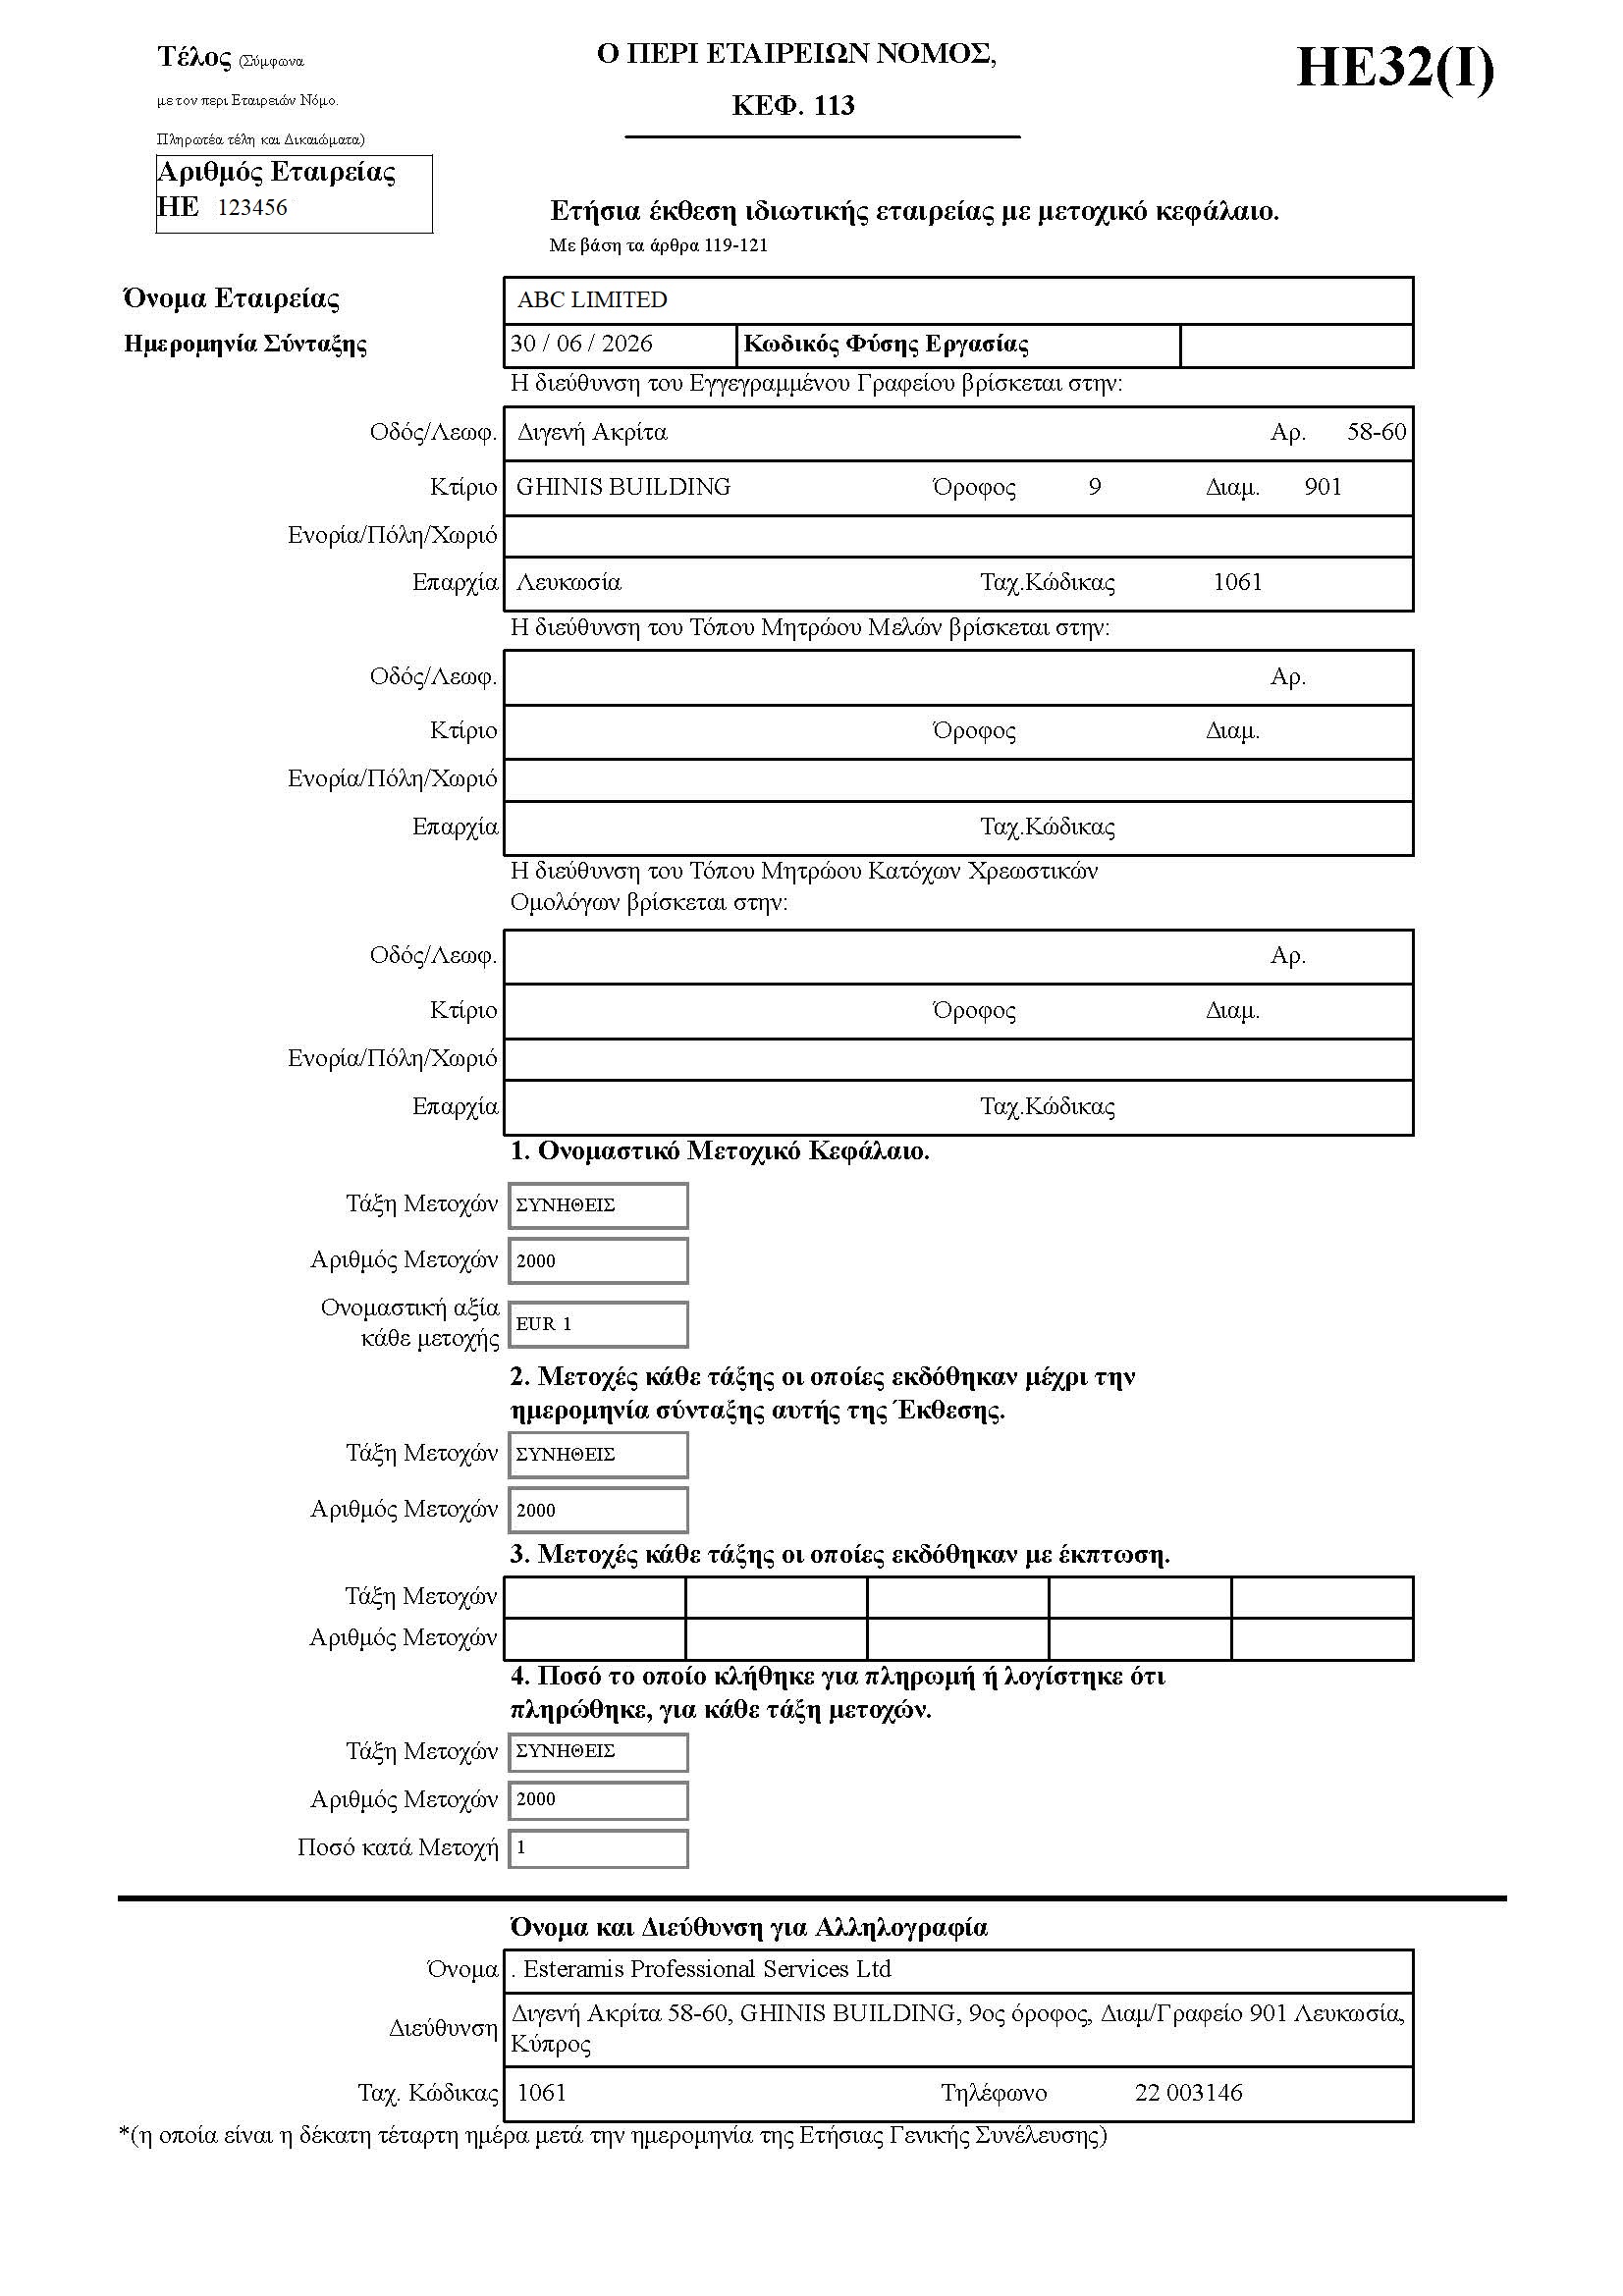
Tax reporting for Cyprus companies with employees requires the submission of Form TD7 (Employer’s Return for Withheld Tax and Contributions).
This form includes the following information:
Starting in 2025, employer returns using Form TD7 must be submitted on a monthly basis – by the end of the month following the reporting period, rather than annually. However, an annual reconciliation of all monthly reports is still required; as of 2026, this reconciliation must be completed by 31 March of the following year. Furthermore, it is now mandatory to include the individual tax identification number (TIN) for each employee on the form.
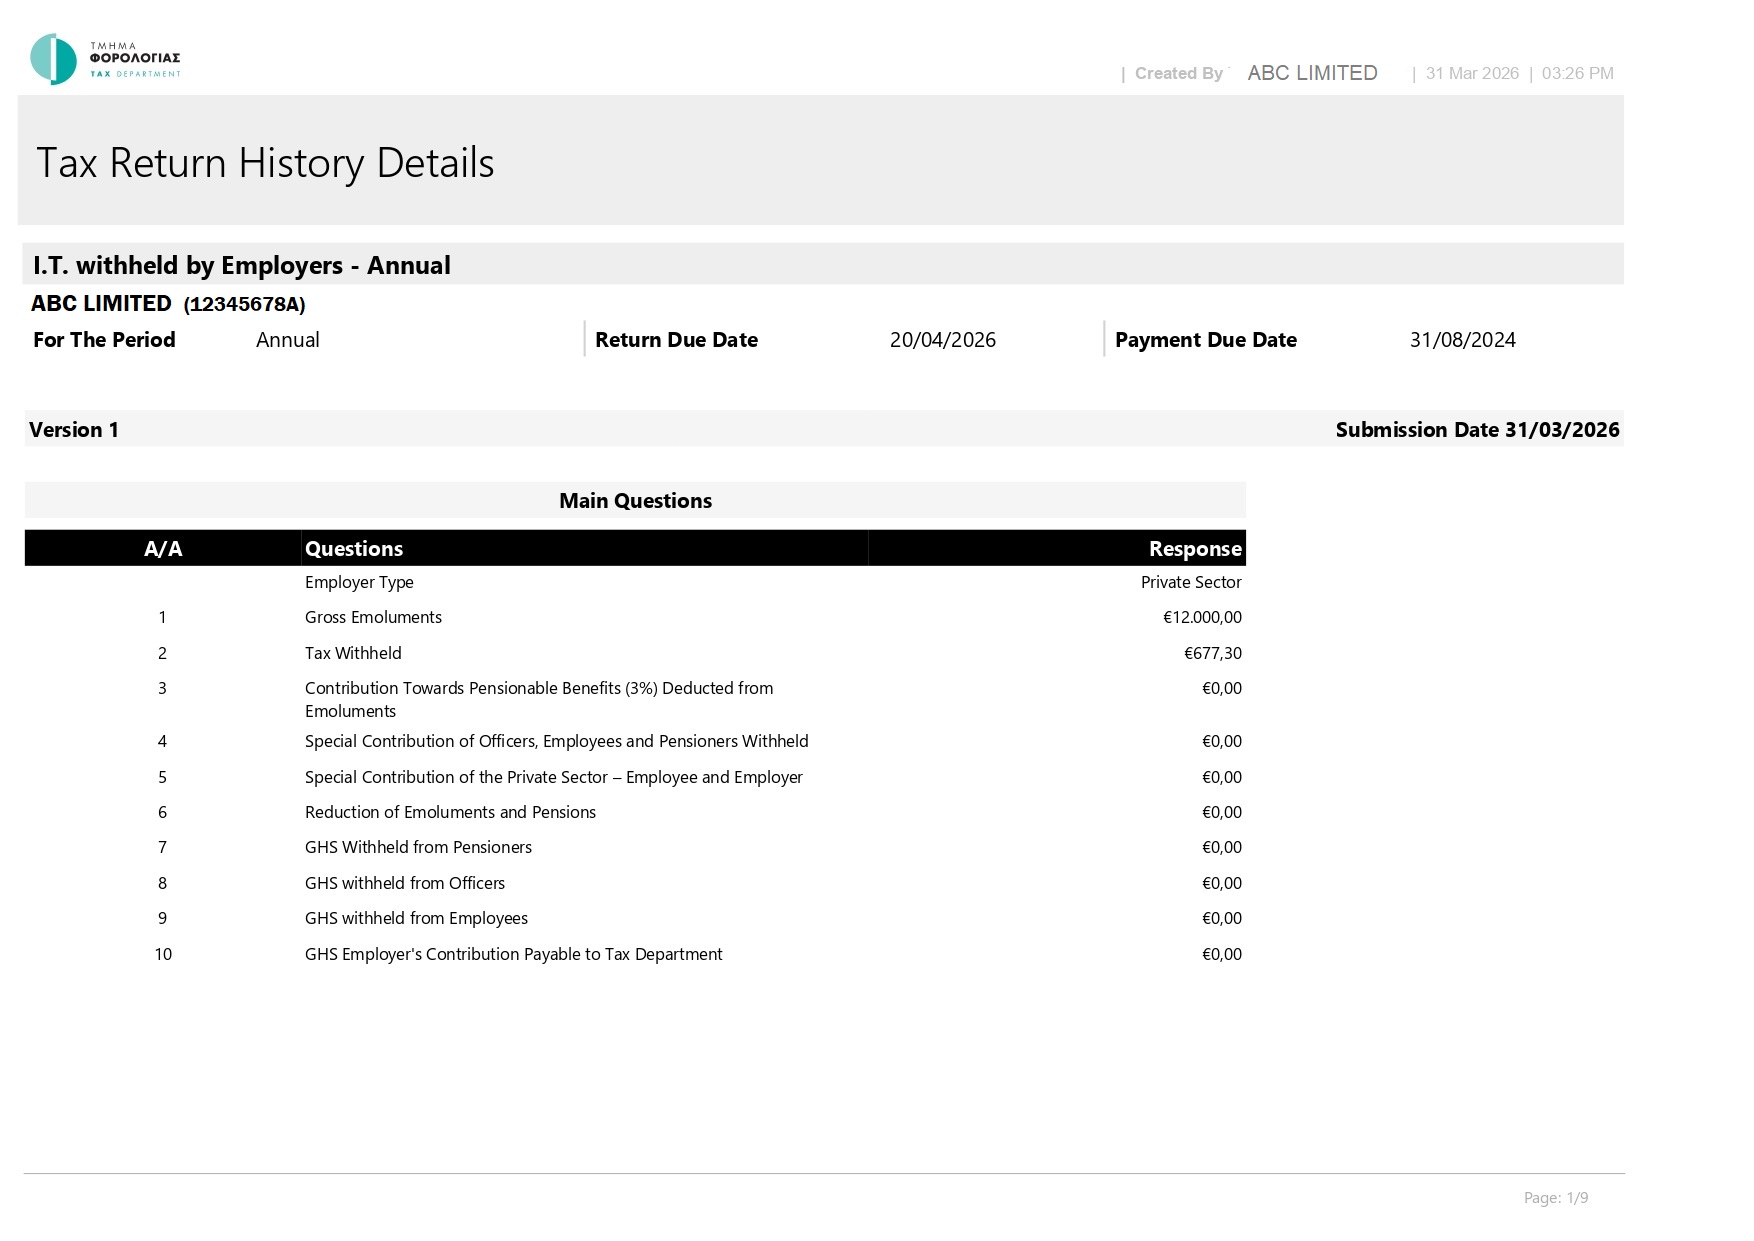
In addition to financial and tax reporting, all companies registered in Cyprus are required to file an Annual Return (Form HE32) with the Cyprus Registrar of Companies every year. The annual return itself does not contain financial figures; rather, it is a corporate document that reflects the company’s current structure and registration details.
The primary purpose of filing an Annual Return is to confirm that the information held by the Registrar regarding the company remains up to date and accurate.
Filing an Annual Return is mandatory, even if the company is not conducting business and has no income. Failure to file on time results in penalties which increase in proportion to the length of the delay. In cases of prolonged non-compliance, a compulsory strike-off of the company can be initiated.
The Annual Return includes the following information:
An Annual Return must be filed with the Registrar of Companies every year within 28 days of its making date (typically the date of the annual general meeting of shareholders). The making date generally falls one year after the date of the previous return, or, in the case of the first return, 18 months after the company’s incorporation.
The Annual Return enables government authorities to track changes in a company’s management and ownership structure, and ensures the transparency of its corporate structure.
| Violation | Penalty |
| Accounting | |
| Failure to maintain accounting records, keeping records non-compliant with the requirements, or failing to fulfil the obligation to retain records | Fine of up to CYP 1,000 |
| Financial statements as part of the Annual Return | |
| Late filing | Fine of EUR 50, plus an additional daily fine of EUR 1, up to a maximum of EUR 150 |
| Employer’s Return | |
| Late filing | Fine of EUR 100 |
Notably, under Cyprus law, it is not only the company itself but also its director that can be held liable. A director has a legal obligation to ensure that accounting records are maintained and financial statements are prepared.
The legislation provides that beneficial owners, defined as individuals upon whose instructions the company’s formal directors act, are considered ‘shadow directors’ and are subject to all the types of liability mentioned above.
Cyprus uses International Financial Reporting Standards (IFRS) as its accounting standards.
However, in early 2026, the jurisdiction introduced a new Financial Reporting Standard for Small Entities, aimed at simplifying compliance for small businesses and reducing their administrative burden. The standard was developed by the Institute of Certified Public Accountants of Cyprus (ICPAC) but is still awaiting final approval from the Minister of Finance. In any case, it will only apply to reporting periods beginning on or after 6 February 2026.
It can only be applied by small companies and small groups of companies (if they meet the established restrictions on a consolidated basis), which at the balance sheet date do not exceed at least two of the following three thresholds:
Regardless of the size of the company or group of companies, this reporting standard is not applicable to public-interest entities, companies listed on stock exchanges outside the EU, banks, insurance companies or large regulated firms.
Yes, even in cases where a company is not conducting business or generating profit, the preparation of financial statements is required to confirm the absence of taxable profit and to ensure compliance with legal requirements.
Companies with no business activity are often referred to as ‘dormant’, and in the same manner their financial statements are also called ‘dormant’ (dormant accounts).
Yes, an audit is mandatory in Cyprus for all registered companies, regardless of their size or whether they are actively conducting business. Annual financial statements must be audited and signed by a certified Cyprus auditor in accordance with International Standards on Auditing (ISA), even if the company did not carry out any business activities in the accounting period.
An auditor in Cyprus must be a qualified professional who holds a licence or a practicing certificate from the Institute of Certified Public Accountants of Cyprus (ICPAC) and is registered with the Public Audit Oversight Board (CyPAOB).
Furthermore, an auditor must have successfully passed not only the professional audit examination but also an examination in Cyprus corporate and business law and taxation. They must also have at least three years of practical experience, including a minimum of six months of experience in statutory audits of companies.
Effective 1 January 2023, a simplified financial reporting review format (International Standard on Review Engagements / ISRE) has been introduced in Cyprus for micro-enterprises as an alternative to a full audit. However, this does not exempt a company from having its financial statements examined by a qualified, certified professional; it merely simplifies the scope and nature of the procedures involved. Although a review engagement does not result in a full audit report, it must still be conducted by a certified auditor or an audit firm.
Companies and groups of companies that are exempt from the requirement to prepare consolidated financial statements may replace an audit with a review engagement, provided they meet a number of:
The tax return form for a Cyprus company includes a section titled ‘Company Financial Statements’, which comprises a balance sheet, a profit and loss statement, and notes – effectively replicating the data found in the financial statements. For the purposes of the tax return, providing this information is considered equivalent to submitting the financial statements themselves. However, the Tax Department reserves the right to request a full set of financial statements and supporting calculations, and the company is obligated to provide them upon such a request.
The annual corporate income tax return (Form IR4) for Cyprus companies is prepared on the basis of financial statements that are subject to a statutory audit (or, in the case of micro-entities, a review engagement in accordance with ISRE, provided that specific criteria are met). Moreover, in the final section of the tax return, the auditor provides their signature and seal to confirm the accuracy of the data; in practice, this means the auditor is involved not only in the preparation of the financial statements but also in the compilation of the tax return itself.
The obligation to produce consolidated financial statements arises when a Cyprus company controls one or more subsidiaries. Even if the ownership stake is less than 50%, an entity may still be classified as a subsidiary if it is effectively controlled by the Cyprus company.
Consolidated financial statements are compiled by combining the financial data of a parent company and its subsidiaries. In this process, intra-group transactions such as loans between group companies, intercompany settlements, and internal income or expenses are eliminated to avoid double counting.
The resulting statements reflect:
Such statements provide an objective view of the financial position of the entire group of companies.
The primary purpose of consolidated financial statements is to present the true financial position and performance of an entire group viewed as a single economic entity, rather than just that of an individual Cyprus company. This is particularly significant when a Cyprus company acts as a holding structure that owns operating companies in other jurisdictions.
In practice, the requirement to prepare consolidated financial statements is especially relevant for holding structures used in international business. Cyprus is widely utilised as a holding jurisdiction for the ownership of companies across Europe, Asia, and other regions.
Consolidated financial statements may be required in the following cases:
Banks and financial institutions often request consolidated financial statements to assess the financial position of a group and to analyse risks. Such statements also allow business owners to gain a comprehensive view of the financial performance of the entire group of companies.
If a Cyprus company is used as a holding structure, the preparation of accurate consolidated financial statements is a key element in ensuring financial transparency and protecting the interests of business owners.
The process of preparing and filing tax returns in Cyprus requires coordination between an accountant, an auditor and a tax specialist. Mistakes or failure to meet deadlines can lead to fines, inspections and problems in dealing with banks.
Professional support allows you to:
Financial statements are the cornerstone of a company’s entire reporting system in Cyprus and serve as the basis for audits and tax filings. Unlike in some offshore jurisdictions where financial reporting may be merely a formality, in Cyprus, financial statements are substantive documents that must be prepared based on source accounting records and in compliance with established financial reporting standards.
Failure to submit financial statements to the Registrar of Companies carries financial penalties. More seriously, the Registrar may designate a company as ‘non-compliant’, restrict its ability to carry out corporate changes (such as appointing or removing directors or shareholders), and, in cases of prolonged non-submission, initiate the company’s strike-off.
The absence of financial statements also makes it impossible to file tax returns, which leads to fines, penalties, and additional tax imposed by the tax authorities. Besides, a failure to produce financial statements is treated as a breach of duty by the directors, thus increasing their personal liability risks.
There are also risks that may be less obvious at first glance. For instance, banks and EMIs may block the company’s accounts or refuse to process transactions and provide services if they do not receive up-to-date financial statements. Moreover, because information regarding a failure to file financial statements is publicly available in the registry, it becomes immediately apparent to any potential business partner that the company has failed to meet its fundamental obligations.