Filing of Nil Tax Returns
(for dormant companies)
Price
1 750 USD

Accounting & Bookkeeping
Mandatory. Primary documents must be retained for at least 7 years.
Financial Statements Preparation
Annual
Accounting Standards
Hong Kong Financial Reporting Standards (HKFRS) or Small and Medium-Sized Entity Financial Reporting Framework and Financial Reporting Standard (SME-FRF & SME-FRS) subject to qualification criteria.
Consolidated Financial Statements
Mandatory if subsidiary companies are held.
Dormant Reporting Option
Available, but subject to mandatory statutory audit requirements unless formal dormant status is registered.
Filing Financial Statements with the Registry
Not required
Filing Financial Statements with the Tax Authority
Mandatory. Must be submitted together with the Corporate Tax Return.
Statutory Audit
Mandatory for all active companies.
Dormant Status
Available via formal registration with the Companies Registry.
Corporate Tax Return
Annual. If no tax liability arises, filing frequency may be reduced by the Inland Revenue Department to once every 3 to 4 years.
Annual Return
Form NAR1 must be filed annually with the Companies Registry within 42 days of the anniversary of incorporation.
Employer’s Return
Annual. Mandatory if the company has employees or pays directors’ fees.
Сompanies must maintain continuous accounting records throughout the financial year, tracking income, expenses, bank transactions, contracts, loans, investments, and other corporate operations. These records serve as the core foundation for compiling financial statements and completing the subsequent audit.
Failure to maintain accounts or retain primary documentation blocks the statutory audit process and prevents corporate tax compliance.
Following the end of the financial year, a complete set of financial statements is compiled under Hong Kong Financial Reporting Standards (HKFRS) or Small and Medium-Sized Entity Financial Reporting Framework and Financial Reporting Standard (SME-FRF & SME-FRS).
Consolidated financial statements are required if the entity operates as a holding company with subsidiaries.
The prepared financial statements are transferred to a licensed Hong Kong Certified Public Accountant (CPA) registered with the Hong Kong Institute of Certified Public Accountants (HKICPA) for mandatory statutory audit.
The auditor examines accounting entries and primary evidence to issue an independent auditor’s report.
Statutory audit is mandatory for all active companies regardless of profitability.
The Inland Revenue Department (IRD) issues and dispatches Profits Tax Return (PTR) forms annually at the beginning of April.
The standard filing deadline is 1 month from the date of issue printed on the form. Block extensions ranging from 3 to 9 months may be granted based on the specific financial year-end date of the company.
Newly incorporated companies receive their first PTR approximately 12 to 18 months post-incorporation.
Based on the audited financial statements, the following actions are executed:
A tax return submitted without the audited financial statements is treated as an incomplete filing.
The completed PTR must be submitted to the IRD together with the audited financial statements and the tax computation either
Filings are typically managed and executed via a registered tax representative.
Upon processing the submission, the IRD issues a Notice of Assessment or a Notice of Loss. The IRD retains the right to issue queries or request additional supporting documentation.
If tax liability is assessed, payment must be settled by the deadline specified in the Notice of Assessment. Late payments incur immediate interest penalties and enforcement surcharges.
Provisional profits tax may be levied based on the preceding year’s assessable profits.
Independent of the audit cycle, a company must file:
These filings are critical components of ongoing corporate maintenance and regulatory compliance.
The interactive calculator provides an estimated cost for accounting, bookkeeping, and statutory audit services.
Total fees depend on annual gross turnover, transaction volume, invoice frequency, the format of primary documentation submissions, and the overall scope of required advisory services.
Statutory audits are performed by licensed Hong Kong Certified Public Accountants (CPA).
Accounting records in Hong Kong must be based on primary documentation that confirms the execution of transactions. This includes bank statements, commercial invoices, contracts, agreements, acts of completion, payment receipts, and other source documents.
Accounting records must contain:
(a) Entries from day to day of all sums of money received and expended by the company, alongside details of the underlying transactions.
(b) A detailed record of the assets and liabilities of the company.
The accounting architecture must explicitly enable the company to:
Directors bear ultimate liability for corporate accounting, regardless of whether operational bookkeeping is outsourced to an external corporate services provider. Failure to maintain proper accounting records, intentional non-compliance, or breaches of record-keeping retention periods constitutes an offense. Directors are subject to a maximum statutory fine of 300 000 HKD, and in cases of willful non-compliance, imprisonment for up to 12 months.
Under Hong Kong legislation, directors bear the primary statutory liability for the preparation of financial statements. Directors must compile financial statements for each financial year that:
Данная обязанность является прямым требованием закона и не может быть делегированаThis statutory obligation is non-delegable and remains with the directors regardless of whether the physical compilation is outsourced to internal accountants or external corporate service providers.
Financial statements must adhere to the “true and fair view” principle. Formal compliance with accounting standards is insufficient if the records fail to reflect the economic substance of corporate transactions. In such scenarios, directors must disclose supplementary information necessary to achieve an accurate representation of the financial state. In exceptional circumstances, departures from specific accounting standards are permitted to ensure fair presentation, subject to comprehensive disclosure of the nature and rationale of the departure.
Financial statements of Hong Kong corporate entities are compiled under Hong Kong Financial Reporting Standards (HKFRS) issued by the Hong Kong Institute of Certified Public Accountants (HKICPA). These standards are fully converged with International Financial Reporting Standards (IFRS), ensuring high levels of cross-border transparency and comparability.
Private companies that are not publicly accountable and meet specific statutory thresholds may adopt the simplified Small and Medium-Sized Entity Financial Reporting Framework and Financial Reporting Standard (SME-FRF & SME-FRS), which reduces disclosure requirements and provides simplified recognition and measurement criteria for certain financial indicators.
The selection of the reporting framework depends on corporate structure, auditor requirements, and commercial objectives. Standard HKFRS may be required to secure international bank financing or institutional investment.
Most private Hong Kong entities utilized in international trade and holding structures qualify for and implement the SME-FRS framework.
To qualify for the simplified reporting regime, a private company (or a small group) must meet at least two of the following three financial thresholds:
Additionally, corporate approval from at least 75% of the voting shareholders is required.
A standalone private company that does not form part of a corporate group may opt into the simplified framework regardless of the financial thresholds, provided all shareholders give unanimous written consent.
Financial statements may be compiled in:
Entities engaged in international trade primarily denominated in US Dollars commonly utilize USD as their reporting currency. This approach does not require regulatory pre-approval, provided the selected functional currency is applied consistently across reporting periods.
The initial financial period:
All subsequent financial reporting periods must span exactly 12 months.
Finalized financial statements must be:
- Examined and verified by a licensed statutory auditor.
- Signed and executed by an authorized director and the auditor.
- Submitted as a mandatory attachment alongside the Corporate Tax Return.
Company directors formally confirm the accuracy of the financial statements and accept ultimate statutory liability for their preparation.
The report provides a comprehensive review of operational performance, core corporate risks, corporate governance structures, and strategic business development plans.
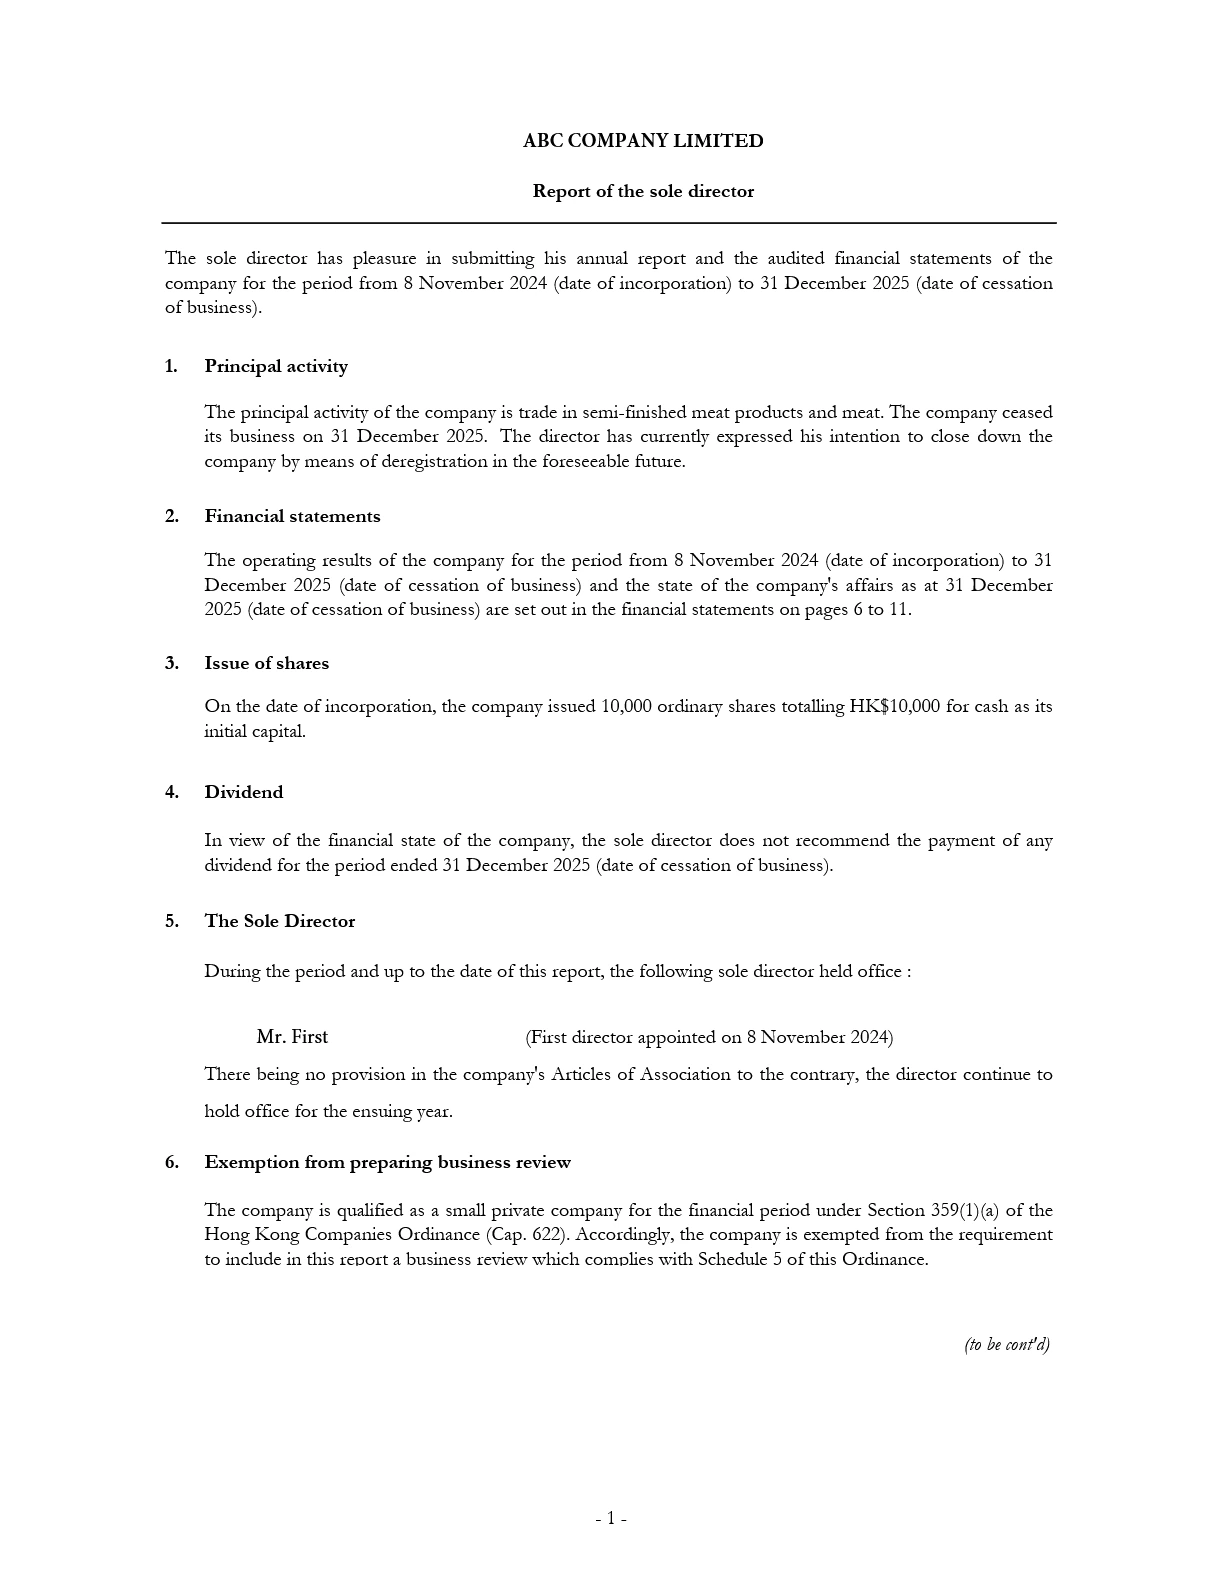
Compiled by an independent licensed Hong Kong Certified Public Accountant (CPA), this report contains the formal professional opinion on whether the financial statements present a true and fair view in all material respects.
The independent auditor’s report is issued on the auditor’s official letterhead and executed with the signature and seal of the practicing CPA firm.
The Statement of Financial Position (or balance sheet) reflects the financial state of the company, systematically capturing its assets, liabilities, and shareholder equity at a specific reporting date.
The Income Statement details the net performance of the company’s financial results, mapping all generated corporate revenues and operational expenses for both the current reporting period and the comparative historical periods.
The disclosure notes form the explanatory narrative of the financial reporting package, outlining the corporate accounting policies and the specific financial reporting frameworks applied by the entity.
The notes provide detailed structural breakdowns of individual line items within the Income Statement and the Statement of Financial Position, alongside disclosures of contingencies and subsequent events impacting the entity’s financial standing.
If a Hong Kong entity holds subsidiaries or exercises operational control over other entities at the end of the financial year, directors must prepare consolidated financial statements that present the financial position and performance of the entire corporate group as a single economic entity.
Corporate control is determined by actual operational governance over the financial and strategic policies of another entity, rather than simple equity ownership percentages. A target entity is classified as a subsidiary if the Hong Kong parent company:
Consolidated financial statements are mandatory if the ultimate beneficial owner of the Hong Kong parent company is an individual. If the parent company is held by a corporate entity, specific consolidation exemptions may apply.
Consolidation exemptions are permitted if:
If a corporate group fails to compile consolidated financial statements and does not qualify for statutory exemptions, the licensed auditor is legally required to issue a qualified audit opinion due to non-compliance with the Companies Ordinance.
A qualified audit opinion or a disclaimer of opinion triggers immediate scrutiny from the IRD during corporate tax assessments. Consequently, holding entities frequently elect to prepare full consolidated financial statements even when technically qualifying for a consolidation exemption.
The consolidated reporting framework must systematically integrate the aggregate assets, liabilities, equity, revenues, expenses, and cash flows of the parent entity and its subsidiaries to reflect a unified economic structure.
Under the Companies Ordinance (Cap. 622), all companies incorporated in Hong Kong must undergo an annual statutory audit. This legal requirement applies irrespective of gross turnover, profit margins, tax liabilities, or the geographical location of operations.
Statutory audit is mandatory for both onshore operating entities and offshore structures, including international trade corporations, holding companies, and investment funds.
Even if an entity operates at a loss or claims an offshore profits tax exemption, its financial statements must be examined by a licensed auditor.
The primary objective of the audit is to verify that the financial statements present a true and fair view of the company’s financial position and comply with the applicable financial reporting frameworks.
Statutory audits may only be conducted by a licensed Hong Kong Certified Public Accountant (CPA) who:
Auditors bear professional and statutory liability for the accuracy of the independent auditor’s report.
The auditor must remain independent of the company and adhere to the Hong Kong Standards on Quality Management, Auditing, Review, Other Assurance, and Related Services (HKSA), which are fully aligned with International Standards on Auditing (ISA).
During the initial phase, the auditor evaluates the corporate structure, business model, source of funds, banking channels, and accounting architecture. This assessment enables the auditor to identify high-risk compliance areas and determine the scope of substantive testing procedures.
The auditor then conducts a detailed examination of primary documentation and accounting ledgers. Bank statements, commercial contracts, invoices, and payment receipts are audited to ensure all financial transactions are accurately recorded.
The audit focuses specifically on the following operational criteria:
The auditor retains the right to issue management queries or request additional supporting documentation from the directors or corporate accountants.
Upon completion of the fieldwork, the auditor issues an independent auditor’s report expressing a professional opinion on the fair presentation of the financial statements.
To compile the statutory file after the close of each financial year, the following primary records covering the relevant reporting period must be submitted:
Digital copies or scanned duplicates of the aforementioned documents are sufficient for audit onboarding purposes.
Upon completion of the statutory audit, the licensed auditor issues an independent auditor’s report containing one of several types of audit opinions.
The most favorable outcome is an unmodified (clean) opinion, which certifies that the financial statements present a true and fair view of the company’s financial position in compliance with the applicable financial reporting framework.
Alternatively, the auditor may issue a modified opinion, such as a qualified opinion. This occurs if the entity fails to compile consolidated financial statements despite controlling subsidiaries, or if the auditor encounters a limitation on the scope of the audit due to unavailable records.
While a qualified opinion does not block the submission of corporate tax returns to the tax authority, it frequently triggers immediate compliance issues with international banks, creditors, and investors.
In rare instances, severe non-compliance or a lack of sufficient appropriate audit evidence results in an adverse opinion or a disclaimer of opinion. These outcomes represent critical statutory breaches that require comprehensive financial restructuring and remediation.
The sole exception to the mandatory annual audit requirement is a company holding official dormant status. An entity qualifies for dormant status only if it is completely devoid of any commercial or accounting transactions. The entity must maintain zero exposure across the following operational criteria:
The only permitted outlays are mandatory maintenance fees, such as statutory corporate registry or registered office expenses.
If a company executes even a single minimal commercial transaction, including minor processing fees, it is legally classified as active and remains bound to the statutory audit framework.
Many Hong Kong entities manage operations globally without generating income from local geographical sources. Securing an offshore profits tax exemption from the Inland Revenue Department (IRD) based on the territorial principle requires the mandatory submission of fully audited financial statements.
The auditor evaluates operational workflows to verify that the core profit-generating activities took place outside Hong Kong. Consequently, the audit serves as the primary instrument to confirm and defend an entity’s offshore tax status.
Beyond statutory compliance, an independent audit is critical to ongoing business operations. Formally audited financial statements are systematically required for:
Operating without an audited financial history restricts an entity’s capacity to execute cross-border business and maintain relationships with top-tier financial institutions.
The reporting architecture in Hong Kong is structured around the Profits Tax Return (PTR), which must be submitted to the Inland Revenue Department (IRD).
Financial statements are not processed as standalone registry filings; instead, they serve as a mandatory attachment to the tax return and are evaluated by the IRD as an integrated component of the company’s tax file.
The PTR remains the central element of corporate tax compliance, while the underlying financial statements and the independent auditor’s report provide the verifiable baseline for the data reported within the tax return.
A Profits Tax Return cannot be submitted as a standalone document. It must be filed as an integrated package with supporting evidence to establish the full tax file of the company, including:
Audited financial statements serve as the primary legal verification of the financial metrics reported by the entity.
The tax year in Hong Kong is uniform for all corporate entities, commencing on 1 April and concluding on 31 March of the following calendar year. This period is officially designated as the Year of Assessment.
An individual company’s financial year-end does not need to coincide with the statutory tax year. In such instances, the basis period for the Year of Assessment is the corporate financial year that concludes within that specific tax year.
For example, if a company’s financial year ends on 31 December 2025, the assessable profits for that period are assessed in the Year of Assessment ending 31 March 2026.
The calculation of assessable profits is anchored by the net accounting profit reported in the audited financial statements, adjusted under the Inland Revenue Ordinance). Specific operating expenses may be disallowed for tax purposes, while qualifying revenue streams may be exempted from corporate tax.
The Inland Revenue Department (IRD) issues annual tax returns to registered corporate entities. The bulk issuance of PTR forms occurs in April of each calendar year. Upon receipt of the form, the company is required to complete and submit the return within the prescribed deadline.
For newly incorporated entities, the initial PTR is issued 12 to 18 months post-incorporation. This timeframe allows the new entity to complete its extended first financial period, compile its financial statements, and finalize the statutory audit.
Following the initial filing, subsequent returns are issued annually if:
а) The company has assessable profits and an active corporate tax liability.
б) The company has incurred significant delays or non-compliance history in auditing or filing preceding tax returns.
Filing a tax return remains mandatory even if the company reported zero operational activity or net losses.
If a company secures an offshore profits tax exemption and files returns in due time, the IRD typically issues a formal notice suspending the annual issuance of tax returns. Consequently, compliant offshore entities are shifted to a reduced filing frequency, submitting a PTR once every 3 to 4 years. However, executing the statutory audit remains mandatory on an annual basis, as the IRD retains the permanent right to issue a retroactive PTR for any historical period at its absolute discretion.
The standard filing deadline for a Profits Tax Return is 1 month from the exact date of issue printed on the form by the IRD.
For newly incorporated entities, the deadline for the first PTR is extended up to 4 months from the date of issue, providing sufficient time to onboard the auditor and complete the statutory filing package.
Companies utilizing a registered tax representative to execute electronic filings through the eTax portal qualify for automatic block extensions. The extended filing deadlines are determined by the company’s specific financial year-end date, categorized under seasonal code classifications updated annually by the IRD.
Extension Code Classifications
Code NFor entities with a financial year-end falling between 1 April and 30 November. No statutory filing extensions are permitted under this classification.
Code D For entities with a financial year-end falling between 1 December and 31 December. The standard filing deadline is typically extended to late August or September of the current calendar year.
Code M For entities with a financial year-end falling between 1 January and 31 March. The standard filing deadline is extended to mid-December of the current calendar year or early January of the subsequent year.
If a company formally reports a tax loss within its PTR, an additional structural extension may be granted, extending the deadline up to February of the subsequent calendar year.
Filing extensions apply to the submission deadline of the Profits Tax Return. Tax liability settlement timelines are determined independently and are enforced only after the issuance of the formal Notice of Assessment.
Upon receiving the Profits Tax Return filing package, the Inland Revenue Department (IRD) processes the documentation and issues either a Notice of Assessment or a Statement of Loss.
The Hong Kong tax system operates under the administrative principle of “assess first, audit later.” The IRD routinely issues an initial tax assessment based on the submitted return, reserving the statutory right to conduct post-assessment audits, field investigations, or anti-tax avoidance reviews at a later date.
Audited financial statements serve as the primary legal evidence used by the IRD to assess corporate tax liabilities.
The IRD retains the absolute authority to request supplementary corporate documentation, including:
Such tax queries represent standard tax administration procedures and do not indicate underlying regulatory violations.
Audited financial records are critical for entities asserting that their corporate profits are derived from sources outside Hong Kong. The licensed auditor must examine operational workflows to verify that the profit-generating activities occurred entirely outside Hong Kong boundaries.
A failure to submit audited financial statements entitles the IRD to summarily reject the offshore tax status claim and levy corporate profits tax on the total net revenue.
If a company reports zero commercial activity throughout the basis period, submitting a Profits Tax Return remains a mandatory legal obligation. The company must file a nil return.
The IRD reserves the right to demand formal verification of the inactive status, including financial statements and independent auditor’s reports, if any operational indicators are identified, such as active corporate bank account movements or active transactional balances.
Independent of financial and tax reporting, all companies incorporated in Hong Kong must submit an Annual Return to the Companies Registry utilizing Form NAR1. The Annual Return does not disclose financial metrics; instead, it operates as a mandatory corporate profile confirming the current legal structure and registry data of the entity.
The primary objective of the filing is to ensure that the public record remains accurate and legally valid.
Filing the Annual Return is mandatory, even for entities reporting zero operational activity or net losses. Late submissions trigger immediate fines scaled to the duration of the non-compliance period. Extended non-compliance results in compulsory striking off from the Companies Registry.
The Annual Return encompasses verified details regarding:
Form NAR1 must be filed with the Companies Registry annually within 42 days of the anniversary of incorporation. This mechanism allows regulatory authorities to track changes in governance and ownership, maintaining corporate transparency.
All Hong Kong entities are legally bound to submit an Employer’s Return of Remuneration and Pensions to the Inland Revenue Department (IRD). The IRD utilizes this filing to monitor personal income tax liabilities and cross-reference individual employment data.
If the company has no personnel, a nil Employer’s Return must be filed to verify that no salaries or benefits were distributed.
If the entity has no active staff but remunerates its directors, the IRD requires the formal disclosure of all directors’ fees within the return.
For companies operating with active personnel, the return must detail:
The initial Employer’s Return is issued by the IRD approximately 12 to 18 months post-incorporation and must be submitted within 1 month from the printed date of issue. Following the initial filing, the return must be completed and filed annually.
Additionally, employers are legally required to file proactive notifications with the IRD upon onboarding new personnel or terminating existing employment contracts. These filings form a critical part of the local tax enforcement framework and are mandatory for all registered employers.
Compliance Requirement |
Penalties and Sanctions |
| Accounting & Bookkeeping | Failure:
Fine of 300 000 HKD, criminal prosecution and imprisonment for up to 12 months for willful non-compliance |
| Corporate Tax Return | Late filing:
Fine of up to 10 000 HKD, court summons for corporate officers, and a compounding penalty equal to triple the amount of tax assessed for the period. Submission of incorrect returns: Fine of 50 000 HKD, a compounding surcharge equal to triple the amount of understated tax, and imprisonment for up to 3 years. |
| Annual Return | Late filing (42 days to over 9 months delay): 870 HKD and 3 480 HKD.
Court prosecution: Fine of up to 50 000 HKD plus a penalty of 1 000 HKD for each day the infraction continues. |
| Employer’s Return | Fine of up to 10 000 HKD, judicial prosecution, and a penalty equal to 3x the amount of understated tax. |
Hong Kong corporate jurisprudence enables regulatory authorities to pierce the corporate veil and enforce personal statutory liability against company directors. Directors bear an absolute fiduciary and legal duty to ensure compliance regarding accounting records and statutory reporting.
Under the applicable laws, UBOs who exercise dominant executive influence over the appointed nominee directors are legally classified as shadow directors, and are subject to all penalties, fines, and criminal liabilities detailed above.
Statutory audit is mandatory for all companies incorporated in Hong Kong, except for entities holding official dormant status. Under the Companies Ordinance (Cap. 622), every active entity must compile annual financial statements examined by a local licensed Certified Public Accountant (CPA) registered with the Hong Kong Institute of Certified Public Accountants (HKICPA).
These audited records must be submitted together with the Corporate Tax Return to the Inland Revenue Department (IRD). Statutory audit forms the cornerstone of corporate transparency framework, and a company cannot execute its tax compliance duties without a valid independent auditor’s report.
All registered corporate entities, excluding officially recognized dormant structures, must undergo an annual financial statement audit performed by a licensed member of the HKICPA. This statutory obligation covers both entities managing operations within Hong Kong and structures operating entirely offshore, including international trade platforms, holding companies, and investment portfolios. The resulting independent auditor’s report must be submitted as part of the mandatory filing package with the IRD.
Financial reporting in Hong Kong is governed by Hong Kong Financial Reporting Standards (HKFRS) issued by the HKICPA. These standards are fully converged with International Financial Reporting Standards (IFRS) established by the International Accounting Standards Board (IASB). Private entities that meet specific statutory size thresholds qualify to adopt the simplified Small and Medium-Sized Entity Financial Reporting Framework and Financial Reporting Standard (SME-FRF & SME-FRS).
Financial statements serve as the primary instrument for corporate tax administration. They are required to determine assessable profits or to substantiate the complete absence of local taxable income when claiming an offshore profits tax exemption under the territorial principle.
The audited financial statements form a mandatory attachment to the Profits Tax Return (PTR) submitted to the IRD, which utilizes these verified metrics to evaluate corporate tax liabilities and audit the legitimacy of the claimed offshore tax status.
Compiling financial statements is mandatory even if an entity reports zero commercial operations or net losses, as these records provide the legal verification of inactive status required to satisfy regulatory obligations. While officially recognized dormant companies are exempt from the statutory audit framework, they are still legally bound to file tax returns upon issuance by the IRD.
Dormant status is not assigned automatically; it must be formally registered by delivering a statutory notification form in hard copy to the Companies Registry, becoming effective only upon physical delivery.
The statutory audit is a mandatory precursor to corporate tax filing. Upon completion of the review, the independent auditor’s report and the finalized financial statements must be attached to the Profits Tax Return (PTR) for submission to the IRD.
The tax authority relies on the audited financial files as its primary source of verification to assess corporate tax liabilities.
Submitting a PTR without the accompanying audited accounts constitutes a material breach of the Inland Revenue Ordinance (Cap. 112), resulting in immediate administrative penalties and tax audits.
Navigating the corporate tax and reporting architecture requires systematic coordination between corporate accountants, licensed CPAs, and tax consultants. Accounting errors or filing delays result in direct statutory fines, structural tax audits, and operational restrictions from international banks.
Retaining professional corporate services ensures:
Financial statements operate as the core document of the corporate reporting framework and are required to execute both the statutory audit and tax filings. Unlike traditional offshore tax havens with nominal record-keeping habits, Hong Kong requires verifiable financial files built on primary transactional ledgers.
While there is no direct standalone administrative fine for missing financial statements as a separate registry document, they are a mandatory attachment to the annual PTR. Submitting a tax return without the audited financial statements invalidates the entire filing package, exposing the entity to IRD penalties for incomplete submissions, late-filing surcharges, and compounding non-compliance assessments.