Compilation and Filing of Dormant Company Accounts
Price
1250 USD

⃰ After the UK left the EU (the so-called Brexit), in order to submit VIES returns, it is necessary to additionally register for VAT in the EU member state.
Accounting & Bookkeeping
Mandatory; retention of supporting documents for at least 3 years
Financial Statements Preparation
Annually
Accounting Standards
UK GAAP ⃰
Consolidated Financial Statements
If a company has subsidiaries
Dormant Reporting Option
Yes
Filing Financial Statements with the Registrar
Yes
Filing Financial Statements with the Tax Authority
LTD: Yes
LLP: Only for a turnover of ≥ £15 million
Statutory Audit
Only for companies that do not qualify as dormant or small
Dormant Status
Does not affect a duty to prepare and file financial statements.
Tax Return
LTD: Annually, within 9 months of the end of the accounting period
LLP: Annually (by 31 October for paper returns; by 31 January for online returns)
Confirmation statement
Annually, at least once every 12 months to Companies House. Not a financial document
Throughout its financial year, a company is required to maintain accounting records, recording income and expenses, bank account transactions, contracts, loans, investments, and other operations. This data forms the basis for drawing up statements and, where necessary, for subsequent audits.
Without accounting records or source documentation a company cannot produce financial statements or file tax returns.
After the end of the financial year, a set of financial statements is drafted in accordance with UK Generally Accepted Accounting Practice (UK GAAP).
If a company is a holding company, the preparation of consolidated financial statements may be required.
Dormant and small companies are exempt from audit. A company qualifies as small if, during the accounting period (for periods commencing after 6 April 2025), it does not exceed at least two of the following three criteria:
If a company exceeds the statutory limits, its financial statements must be audited by a licensed UK auditor. The auditor examines the accounting records and source documentation and issues an auditor’s report.
Based on the financial statements, the tax return form is completed:
LTD
A key feature of the UK corporation tax is that the tax payment deadline falls earlier than the deadline for filing the tax return. Tax must be paid within 9 months and 1 day after the end of the accounting period, whereas the return on Form CT600 must be filed within 12 months of the period’s end.
LLP
An LLP is a tax-transparent entity, meaning that, as a legal entity, it does not pay corporation tax. All partnership profits are automatically distributed among the members and subsequently taxed at their level, depending on their status (individuals or legal entities) and tax residency.
The filing deadlines for the partnership’s SA800 return depend on the submission method:
Then each member is required to file a personal tax return and pay tax on their allocated share of the profit.
In addition to the financial and tax reporting, the company is required to file:
These filings are not directly related to the audit but are mandatory elements of corporate compliance.
The calculator provides an estimate of the cost of accounting and audit services for a company.
The cost depends on the company’s turnover, the number of invoices and transactions, the format in which supporting documents are provided, and the scope of services required.
The audit is conducted by a certified UK auditor.
Accounting in the UK is based on source documentation that substantiates the actual execution of transactions. Such documentation includes contracts, invoices, certificates of work performed, delivery notes, bank statements, payment orders, and other documents verifying the company’s transactions.
Accounting records must reflect:
If the company’s business involves dealing in goods, the accounting records must contain:
Overall, accounting records must enable to:
Failure to comply with document retention requirements or deadlines may result in the director (or another company officer) facing a fine imposed by HMRC or disqualification. If a wilful violation is proven, the liability, on conviction, may even include imprisonment for up to 2 years.
Under UK law, the responsibility for preparing financial statements rests with the company’s directors. Directors must ensure that a full set of accounts (financial statements) is prepared for each financial year.
This duty is a statutory requirement and cannot be delegated to third parties, even if the statements are effectively prepared by accountants or external specialists.
The accounts of a UK company must give a ‘true and fair view’ of its assets, liabilities, financial position, and profit or loss. To ensure the statements provide a true and fair view, directors and accountants must adhere to key accounting standards, prioritise substance over form, maintain rigorous internal controls, and provide clear information.
If company directors approve annual financial statements that do not give a true and fair view of the company’s financial position, and do so knowingly or negligently, they face the risk of criminal prosecution, unlimited personal fines, and disqualification.
Currently, financial statements of UK companies must meet the New UK Generally Accepted Accounting Practice (UK GAAP), which incorporates many provisions of International Financial Reporting Standards (IFRS) and International Accounting Standards (IAS).
Another standard – UK-adopted international accounting standards – is mandatory only for consolidated financial statements of UK companies with securities traded on a recognised stock exchange.
Under UK GAAP and IFRS, a company can choose any currency for the presentation of its financial statements, provided it reflects the economic environment in which the company operates. UK companies may prepare and file financial statements in a foreign currency. Filings of accounts presented in a foreign currency are accepted under the Companies Act 2006 framework via guidance from the Institute of Chartered Accountants in England and Wales (ICAEW).
However, HMRC requires that taxable profit be calculated in GBP and that, for VAT returns, foreign currency amounts be converted into GBP using official exchange rates.
A company’s accounting reference period (or financial year) ends on its accounting reference date (ARD). The ARD is automatically set as the last day of the month in which the company was incorporated. For instance, for a company incorporated on 23 September 2025, the financial year-end is 30 September, and the initial accounting reference period runs from 23 September 2025 to 30 September 2026. Successive accounting reference periods span 12 months, meaning the company will annually file financial statements drawn up as at 30 September.
As is the case in many jurisdictions, the first financial year may be extended to up to 18 months (though it must be at least 6 months long).
A company is allowed to make its annual financials up to 7 days before or after its standard ARD. For example, if the ARD falls on 31 December, the financials may legally cover a period ending anytime between 24 December and 7 January. This flexibility allows businesses to align their financial year-end with specific weekends or month-ends without formally changing the established date. It is important to note, however, that the deadlines for filing financial statements with Companies House do not change as a result.
While the 7-day adjustment is an option for specific instances, companies may also formally change their financial year-end date. Shortening the accounting reference period is currently unrestricted (it can be done as often and by as many months as desired) whereas extending it is limited to a maximum of 18 months and is permitted no more than once every 5 years. Importantly, since a tax period cannot exceed 12 months, extending the financial year beyond 12 months necessitates the filing of two separate company tax returns.
In the UK, companies are classified into micro-entities, small, medium-sized, or large companies based on specific financial indicators and the number of staff. For financial years starting on or after 6 April 2025, a business must meet (i.e., not exceed) at least two of the three criteria, to qualify.
| Micro-entities | Small companies | Medium-sized companies | Large companies | |
| Turnover | ≤GBP 1 million | ≤GBP 15 million | ≤GBP 54 million | > GBP 54 million |
| Balance sheet total | ≤GBP 500,000 | ≤GBP 7.5 million | ≤GBP 27 million | >GBP 27 million |
| Number of employees | ≤10 | ≤50 | ≤250 | >250 |
A company normally changes its size classification only if it meets or exceeds the thresholds for 2 consecutive financial years (except in the first financial year).
This classification directly determines the depth of statutory disclosures in the financial statements, the accounting framework used (such as FRS 102 or FRS 105), and whether a mandatory independent audit is required.
Statutory accounts (financial statements) must include:
The basic statutory set may be accompanied by:
In October 2025, the government announced plans to exempt medium-sized private companies and wholly-owned subsidiaries of UK parent companies from the requirement to produce a strategic report, as well as to remove the requirement for all companies to produce a directors’ report.
A company’s size determines not only the composition of its financial statements but also the level of detail in the financial information presented.
Historically, many companies filed ‘abbreviated accounts’. However, this option was abolished in 2016 and replaced by ‘abridged accounts’. The ‘abbreviated accounts’ format allowed a company to prepare full financial statements for its shareholders and then condense them for filing with the registry for public access. In contrast, ‘abridged accounts’ require making and submitting the same set of financial statements for both shareholders and Companies House; this means the company must decide whether or not to abridge the accounts at the very stage of their drafting.
At present, small companies have the following accounts formats available for submission to Companies House:
These consist of a simplified balance sheet and profit and loss account.
Small companies can still choose to abridge these elements of the accounts, but they must do so for both their members and Companies House. This decision must be made in advance, and all shareholders must approve it annually.
The company submits only the balance sheet and notes, omitting the profit and loss account and the directors’ report.
In this scenario, the company decides what information to prepare for its shareholders – full accounts, abridged accounts, or micro-entity accounts – and then removes certain information before filing with Companies House.
Abridged accounts vs. Filleted accounts
Abridged accounts are a way of preparing the profit and loss account and balance sheet without disclosing full information. Filleted accounts occur when a company decides not to submit certain reports to Companies House, such as the profit and loss account or the directors’ report.
The simplest and most compact format for the smallest companies. This format allows making accounts with even less detail than other businesses, and exempts directors from preparing a report.
Certain important changes regarding accounts are set to take effect in April 2028:
- The option to prepare and file ‘abridged accounts’, featuring a simplified or condensed balance sheet and profit and loss account, will be abolished.
- Submitting a profit and loss account and a directors’ report will become mandatory for all small companies and micro-entities.
- Companies will be able to opt out of disclosing their profit and loss figures in the public register, although HMRC and law enforcement agencies will still receive this information.
- All accounts will need to be filed digitally via commercial software in iXBRL format, as traditional web-based and paper filing methods will no longer be supported.
Under the Companies Act 2006, a UK company with subsidiaries is required to consolidate its financial statements with those of its subsidiaries. The group’s consolidated financial statements must reflect the aggregate assets, liabilities, equity, income, expenses, and cash flows of the parent and subsidiary companies, as they constitute a single economic entity.
A company is considered a subsidiary of another company if the latter:
The following entities are exempt from preparing consolidated financial statements:
A parent company is not required to produce consolidated financial statements if the entire group qualifies as small and is not otherwise excluded (e.g., it does not include public companies). The thresholds for group size classification are the same as those for individual companies.
An intermediate parent company, whether incorporated in the UK or elsewhere, may be exempt from consolidation if its results are fully consolidated into the publicly available financial statements of a larger group.
Listed companies are required to prepare group financial statements regardless of their physical size.
A parent company can exclude a subsidiary from consolidation if the subsidiary’s figures are ‘immaterial’ to the group’s overall position.
If several subsidiaries are immaterial individually but material in the aggregate, their consolidation is mandatory.
Even if a group meets the small group criteria, it loses the consolidation exemption if the parent or any affiliated group company is:
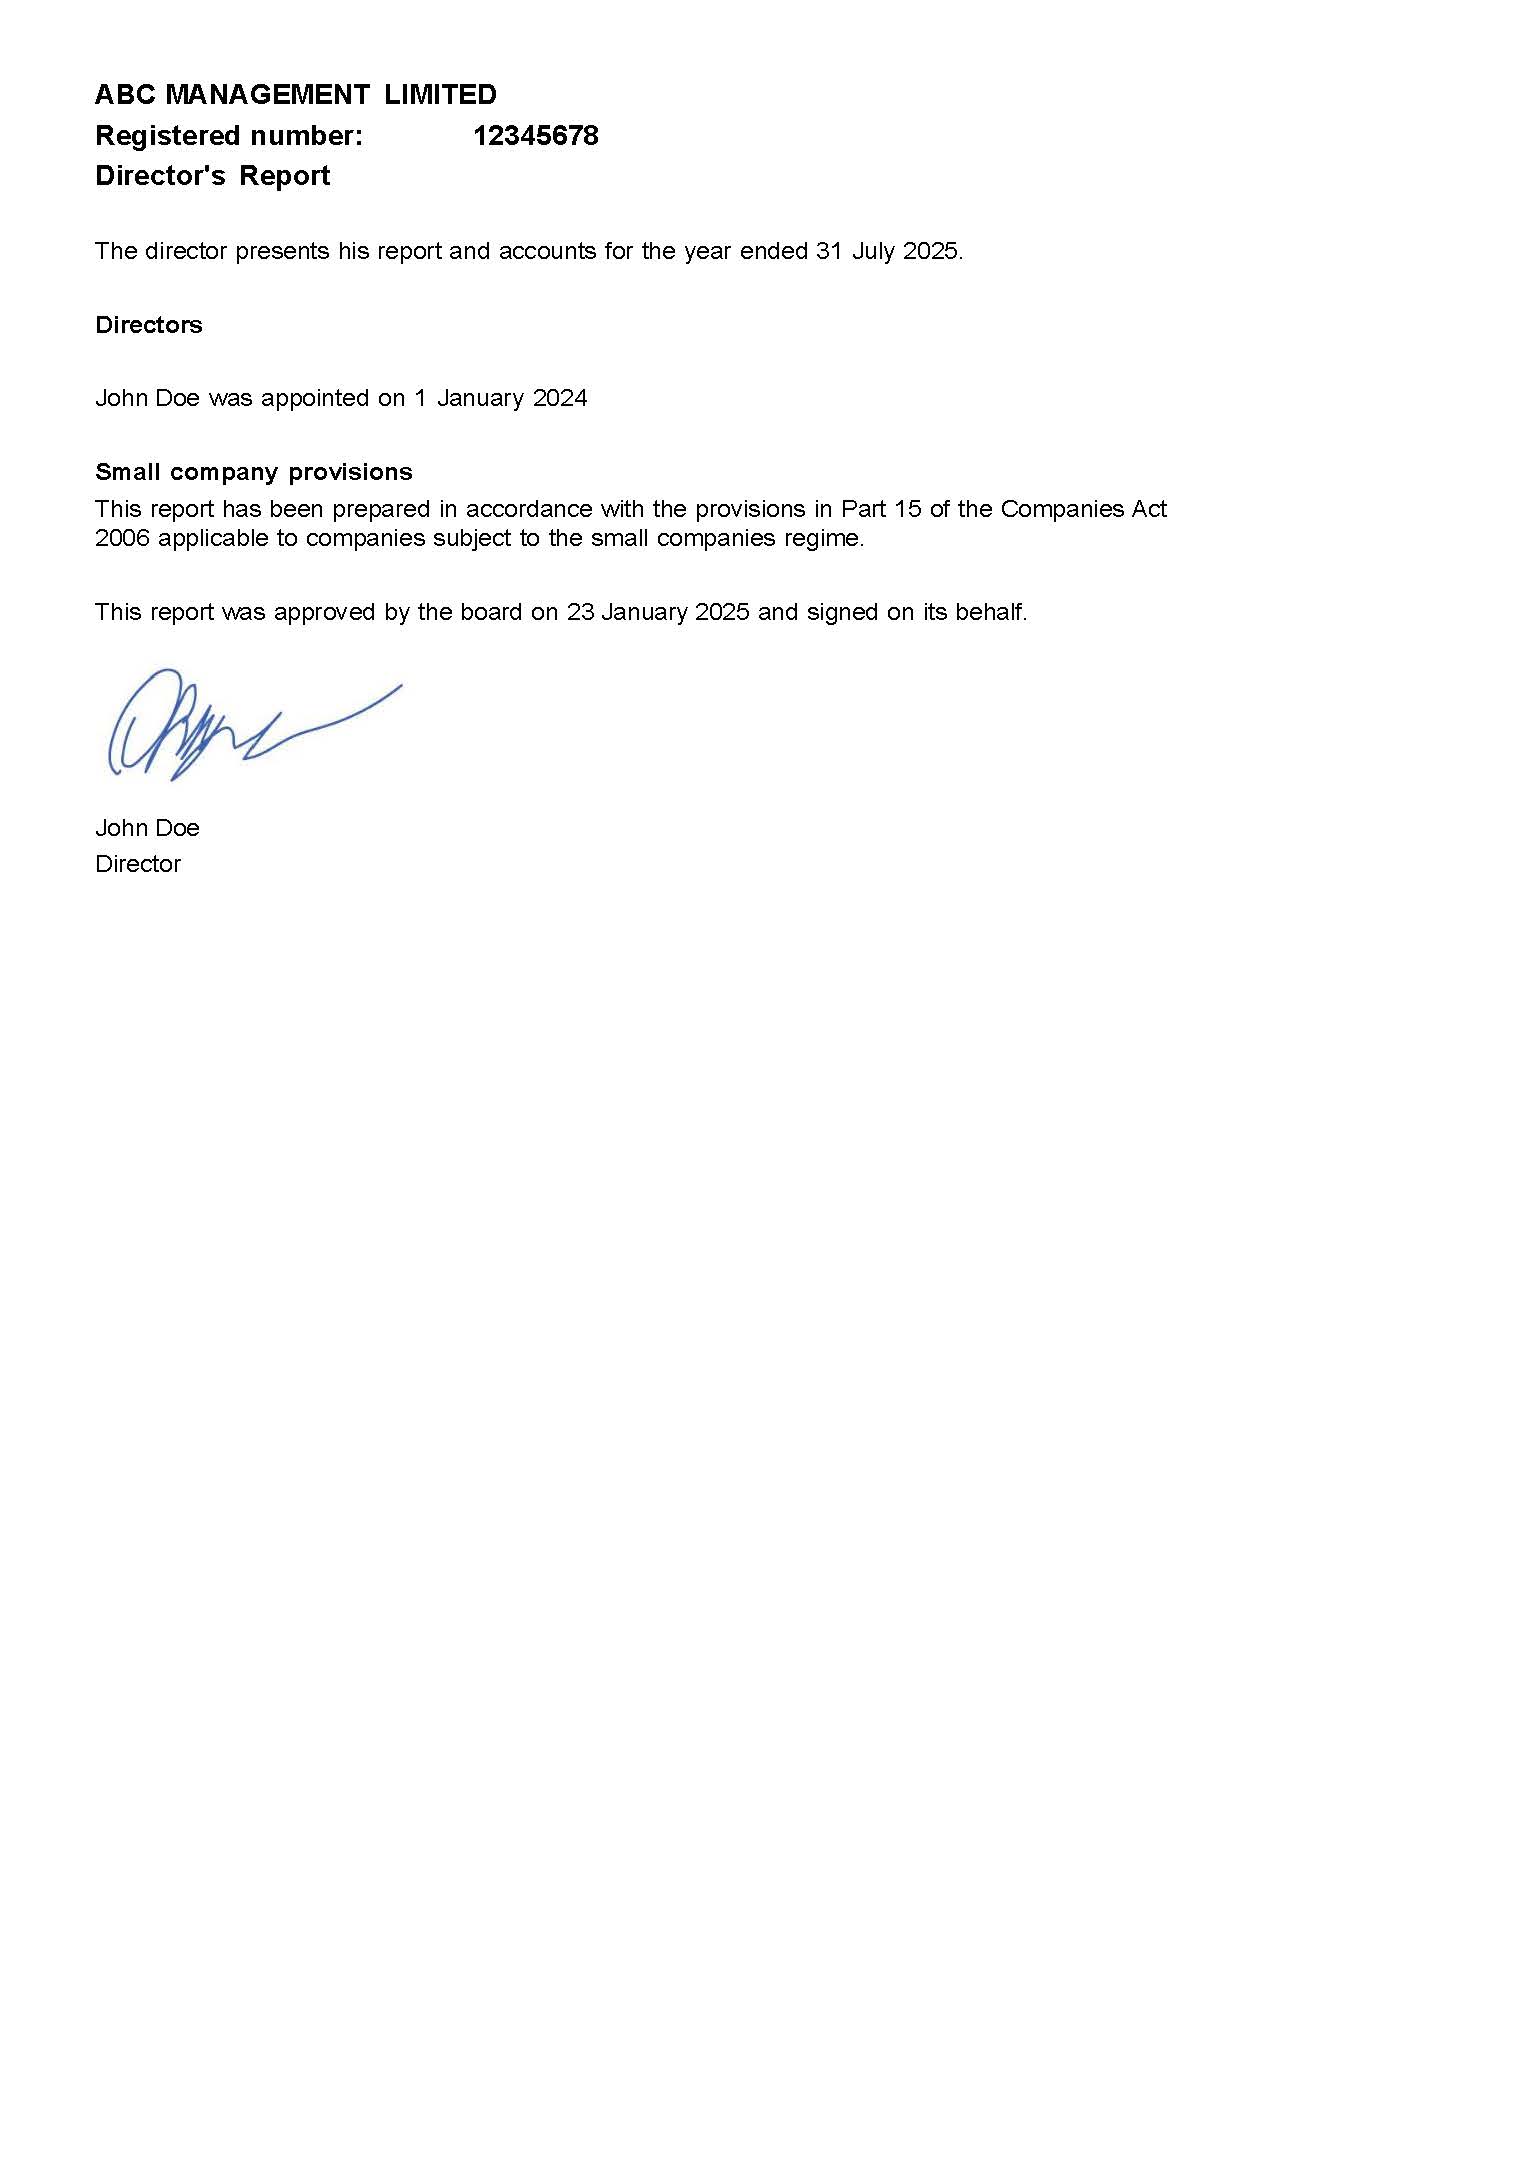
An overview of the company’s performance, challenges, and prospects for strategic development from the directors’ perspective (mandatory for all companies except micro-entities).
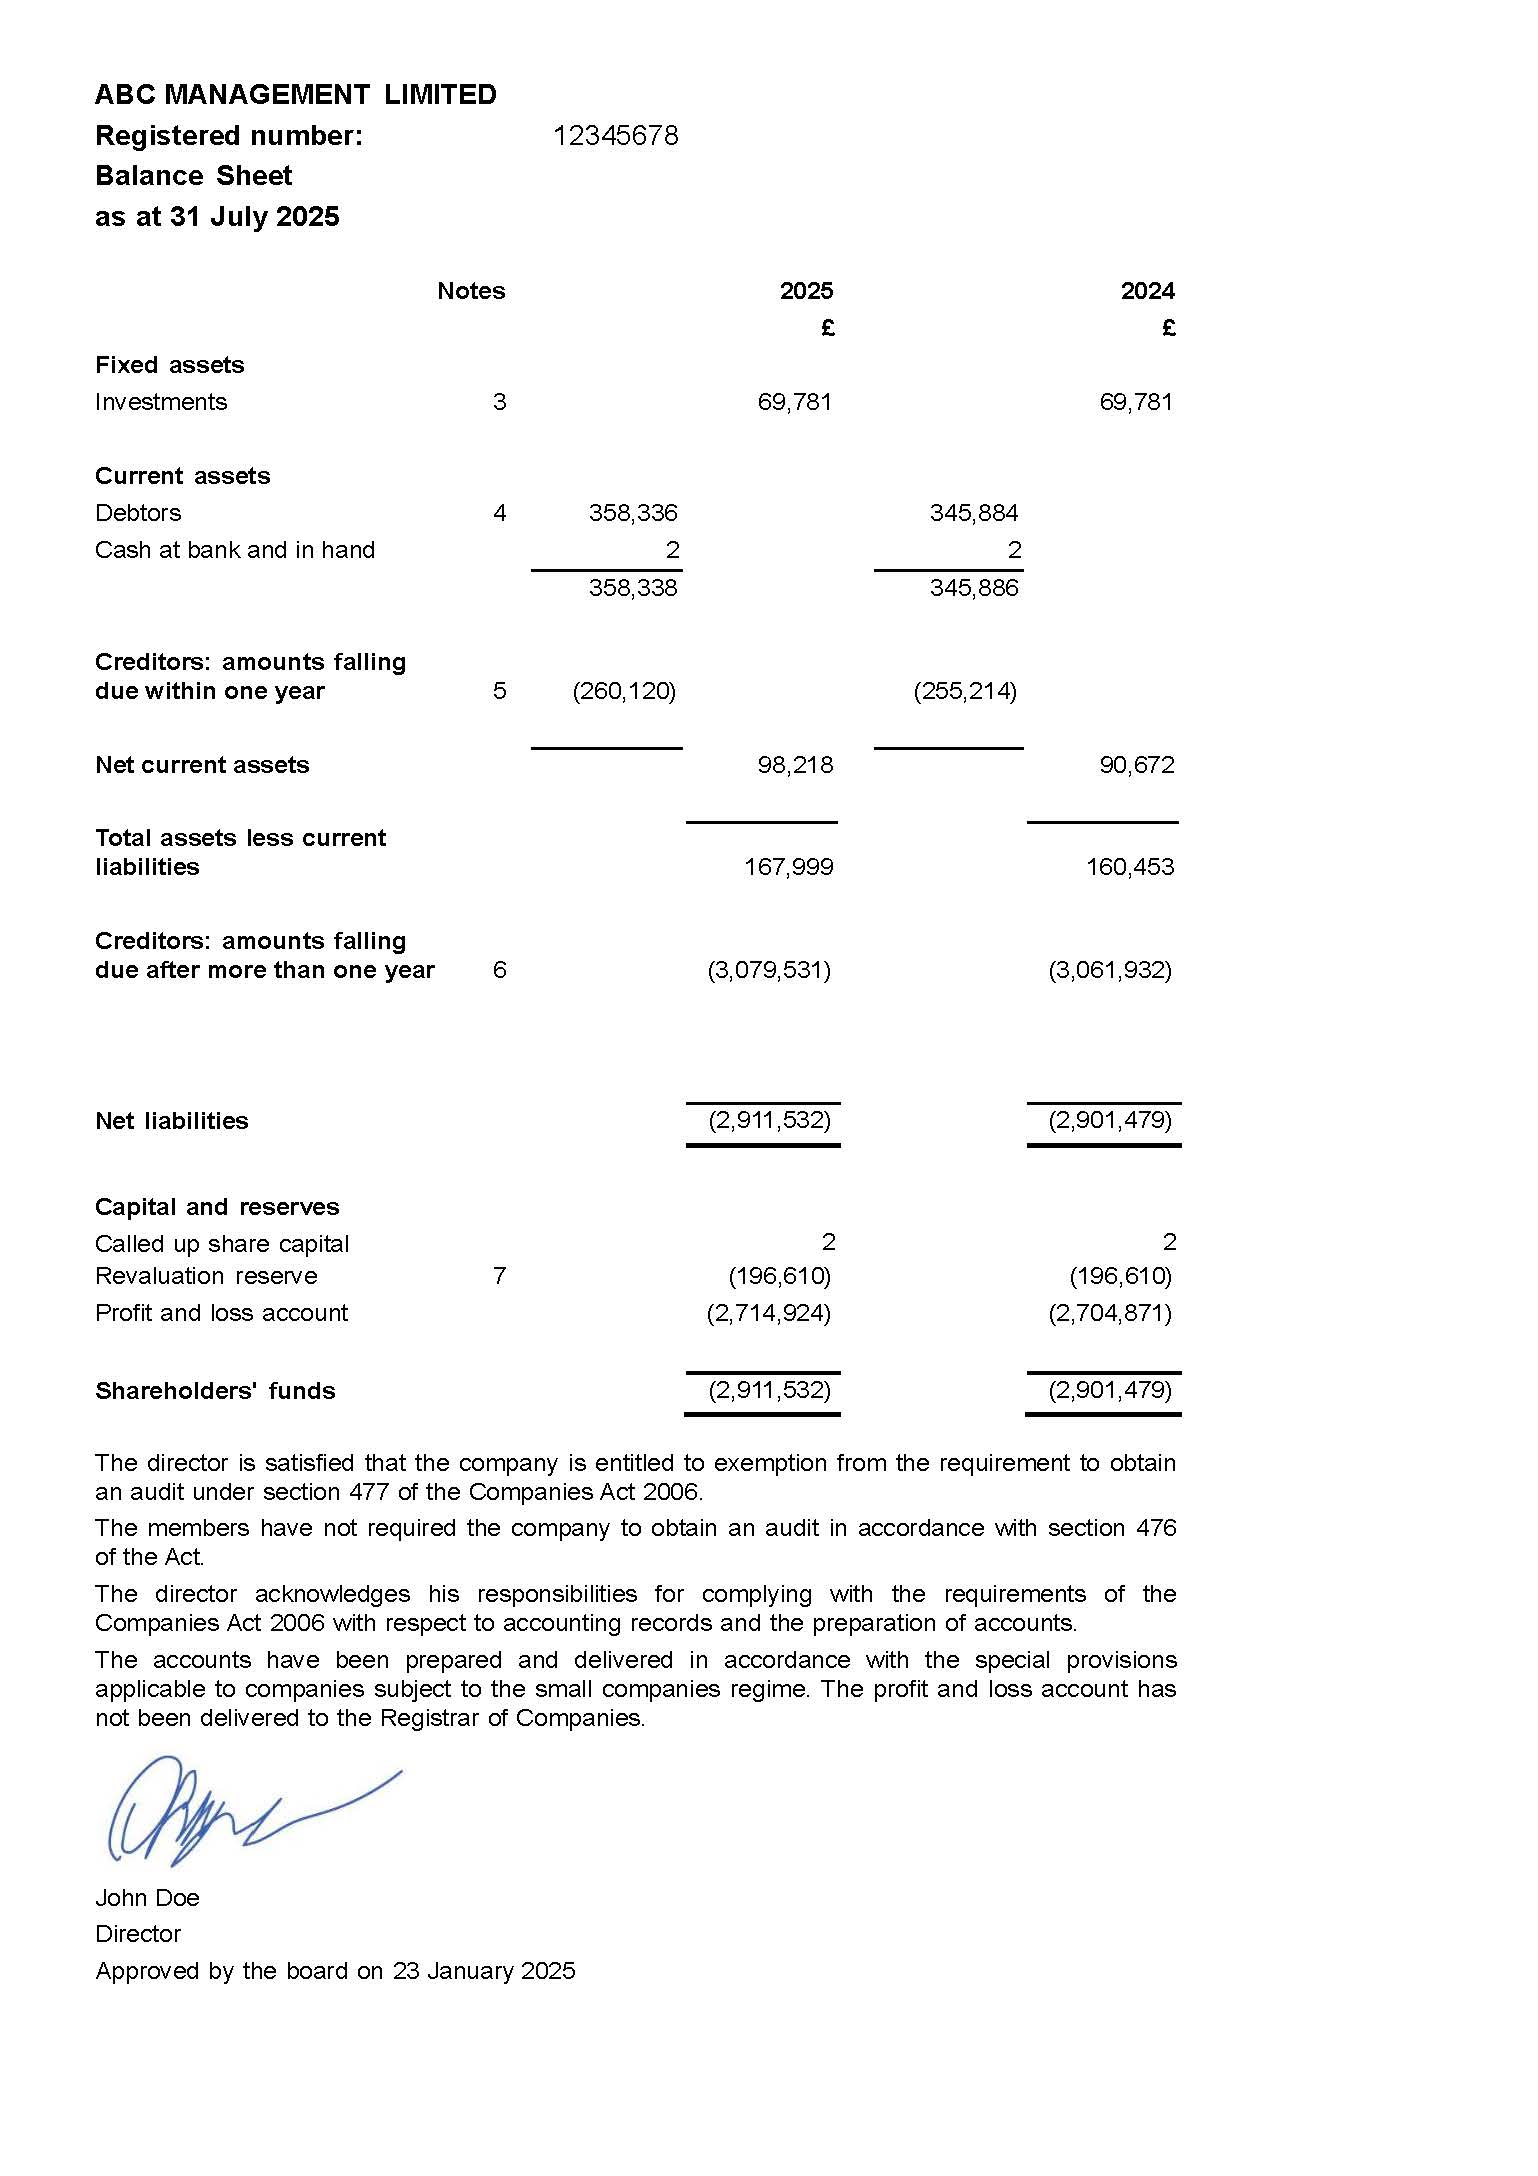
Shows the value of all the company’s assets, debts, and liabilities as at the reporting date (i.e. the last day of the financial year)
Shows the company’s sales revenue, operating expenses, and profit or loss for the financial year
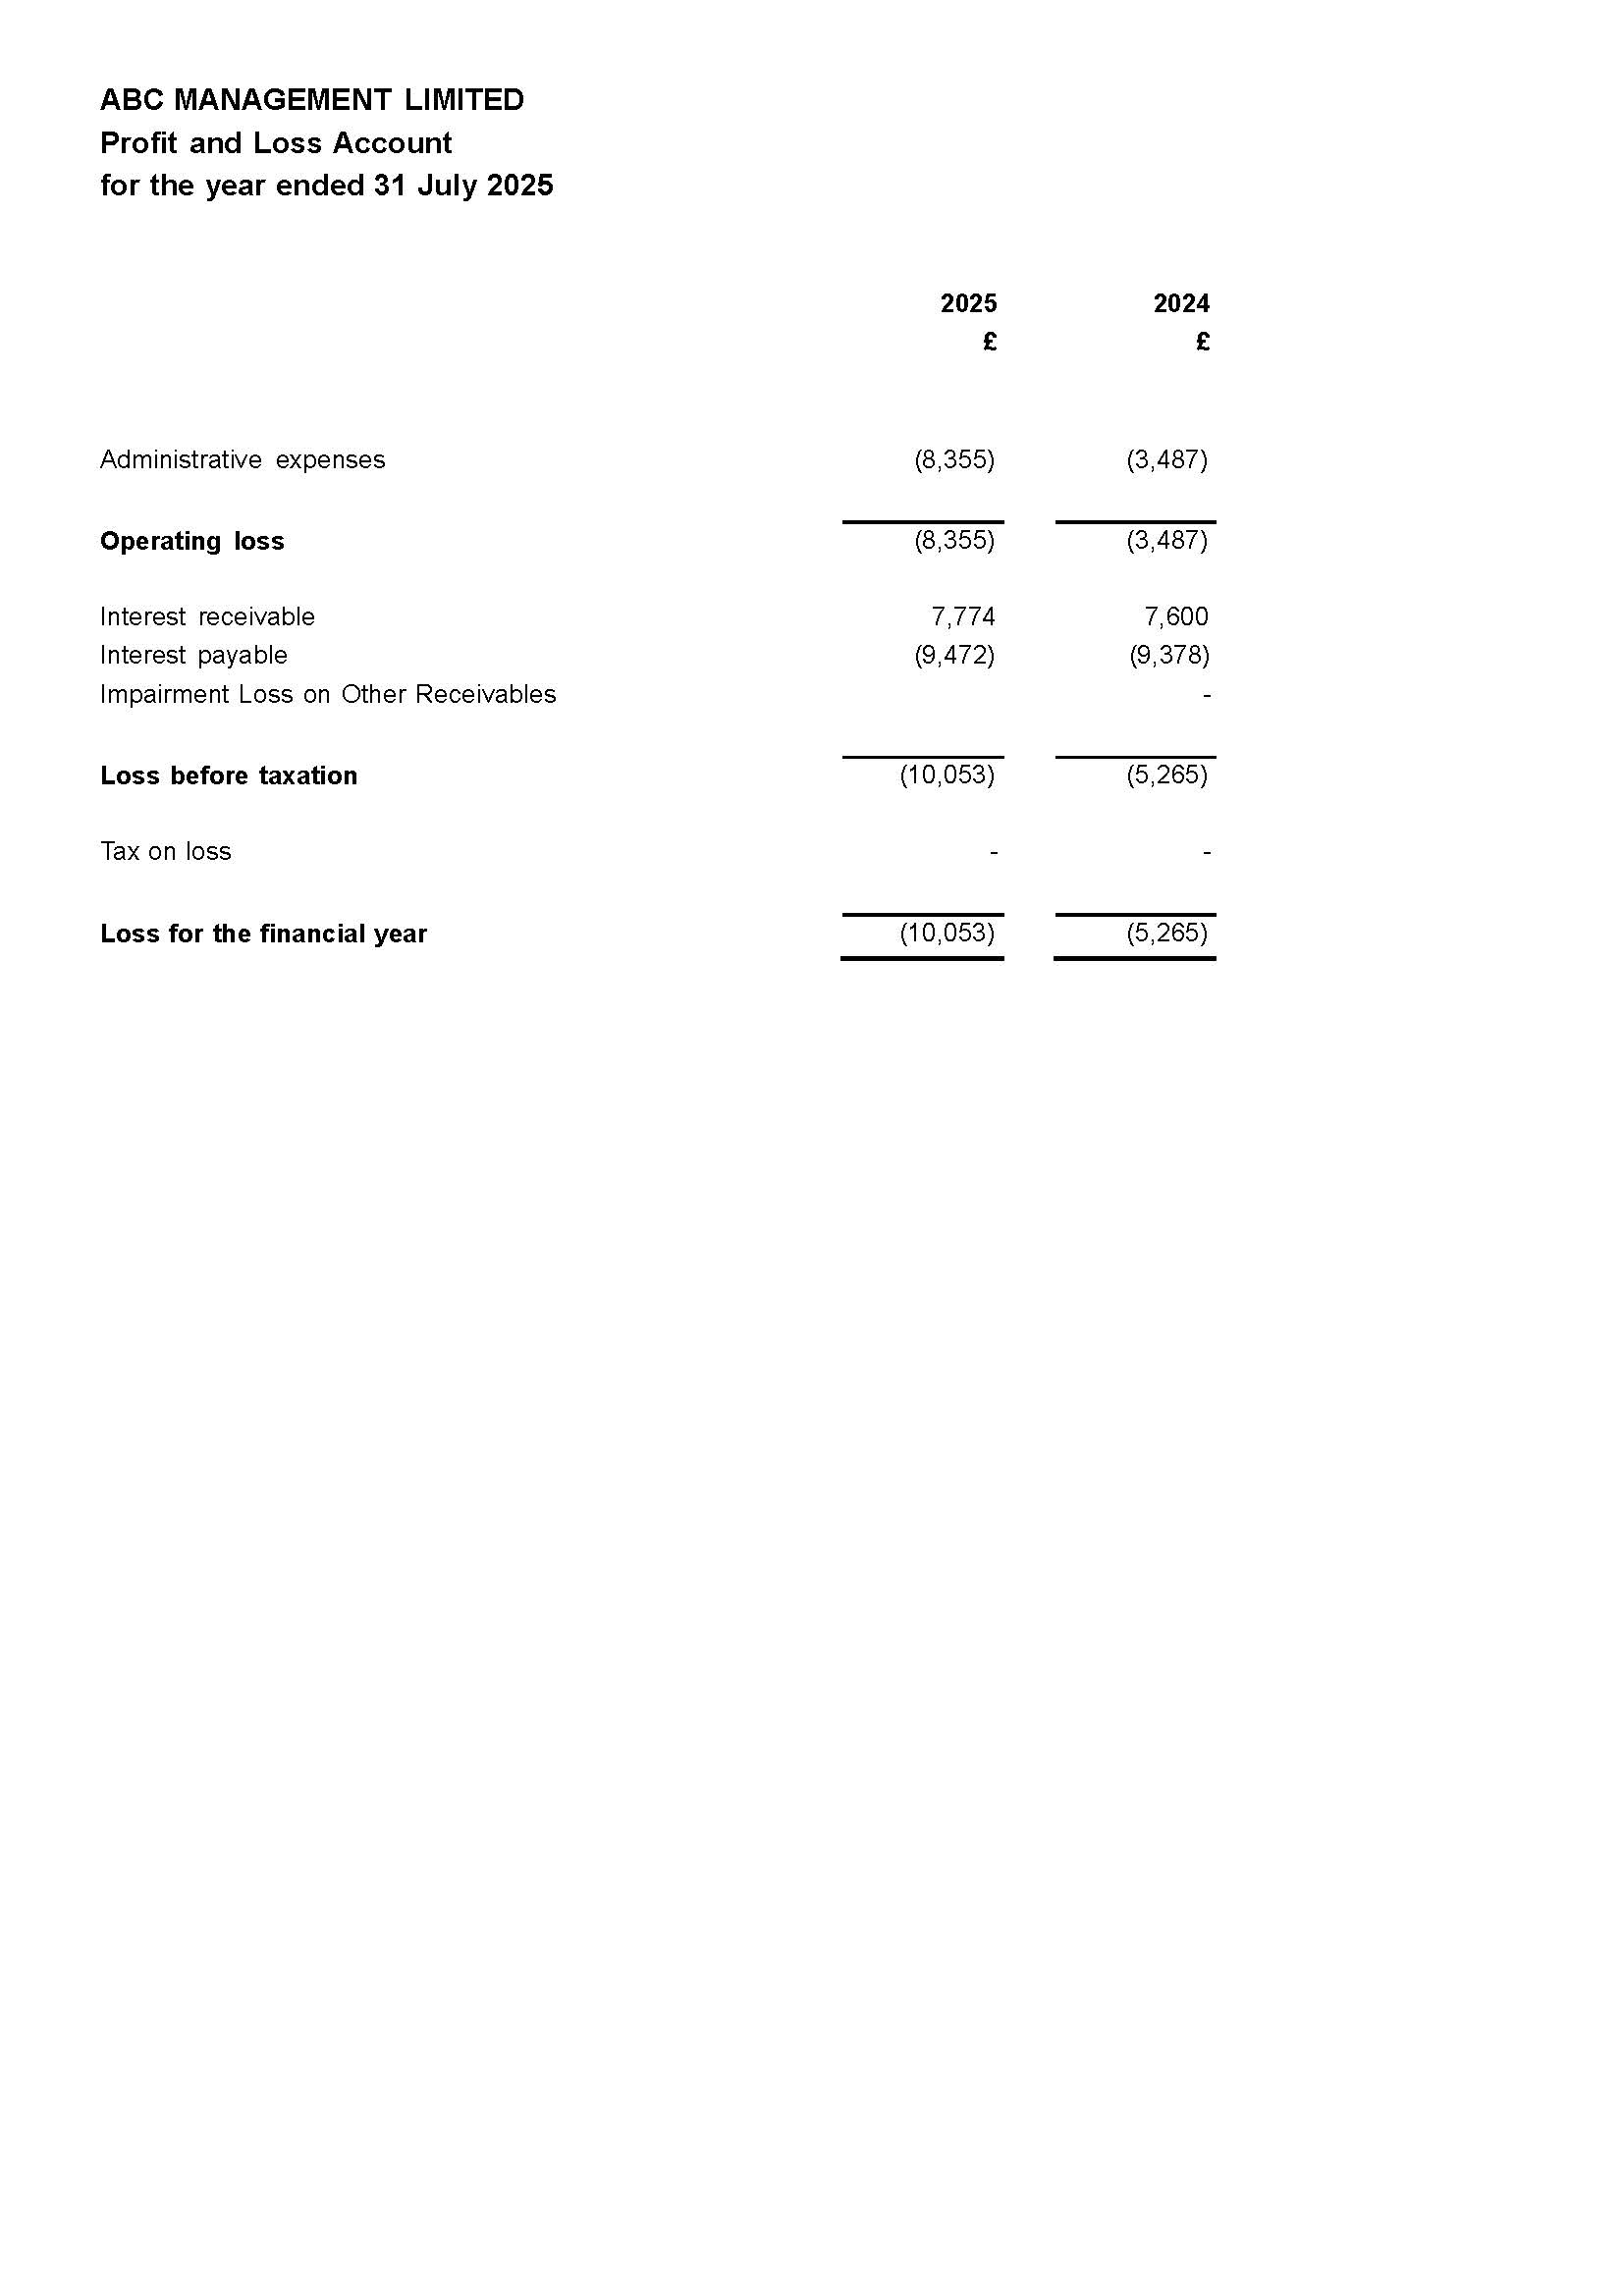
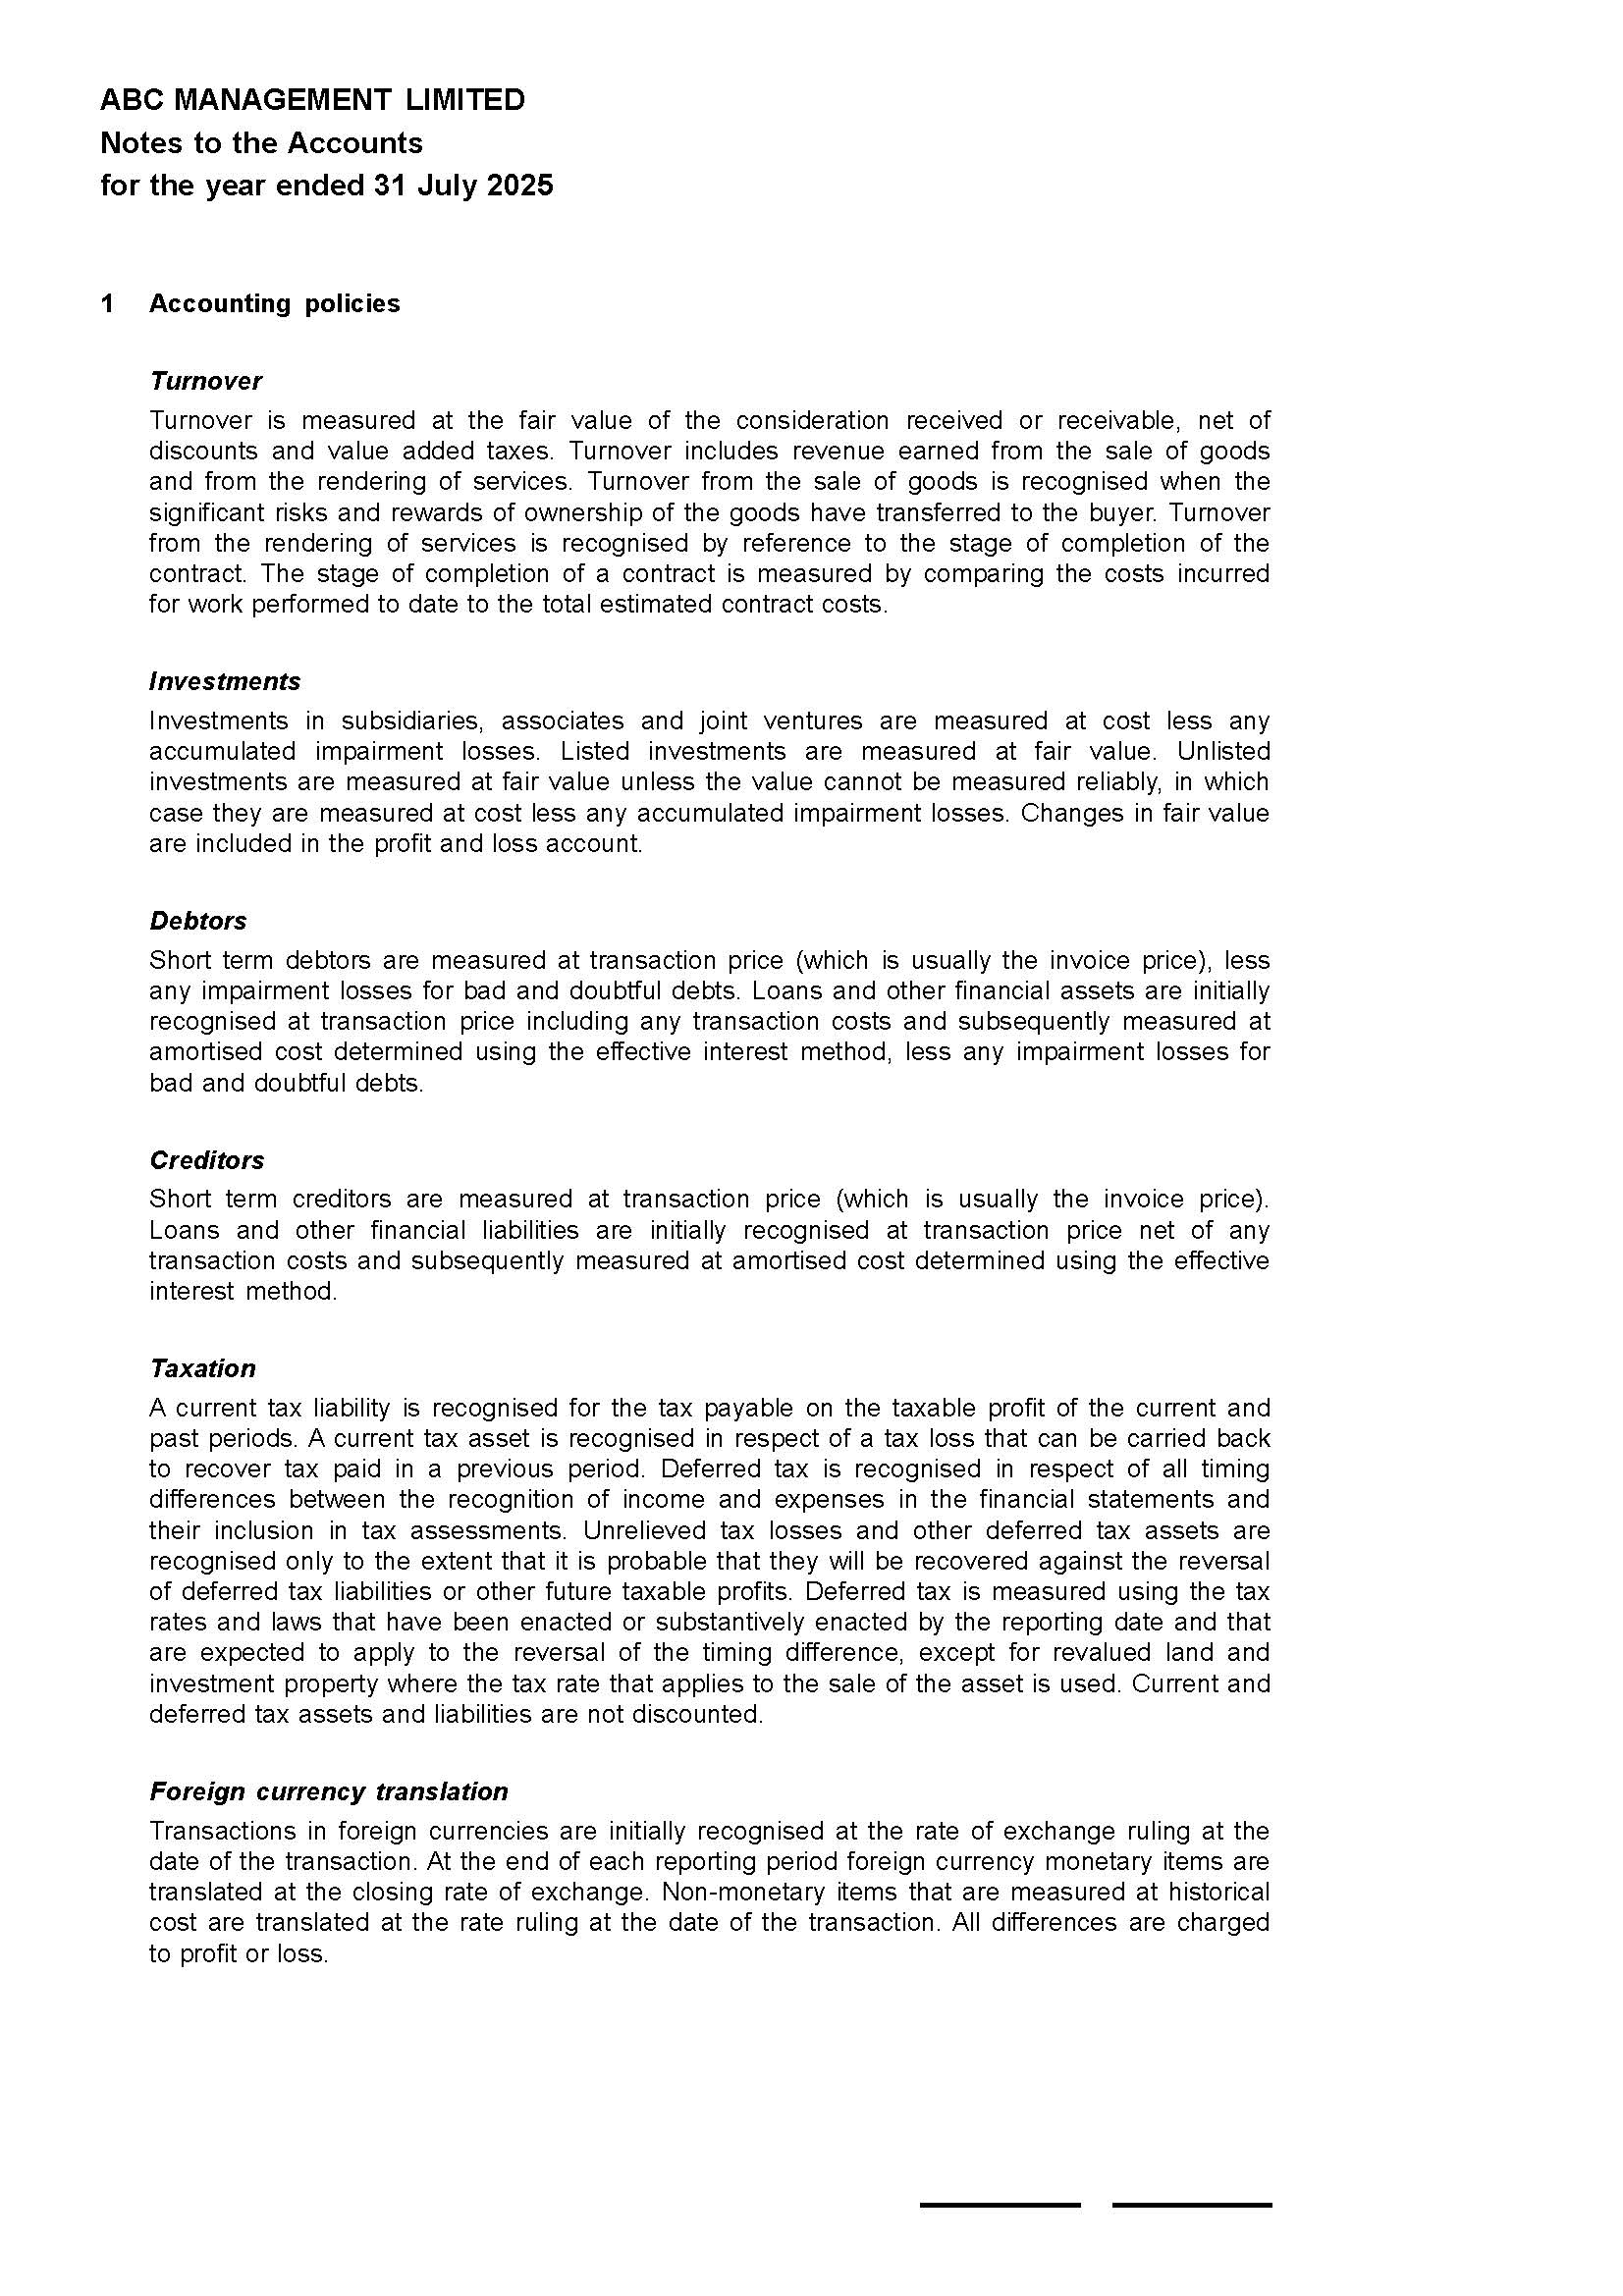
Detailed explanatory notes and disclosures accompanying the company’s financial statements, providing further clarification of the figures presented in the balance sheet and profit and loss statement
If a UK company does not qualify for an audit exemption, its financial statements must be audited, and the auditor’s report must be attached to the statements.
The primary objective of the audit is to confirm that the company’s financials fairly present its financial position and have been prepared in accordance with applicable financial reporting standards.
To act as an auditor in the UK, an individual or an entity must hold an official auditor qualification, obtain a practising certificate, and be registered with a recognised supervisory body, such as the ICAEW or ACCA.
To qualify as an auditor in the UK, an individual must meet strict legal and professional criteria:
If an audit is conducted by an organisation, that organisation must meet the following requirements:
Independence rules
An auditor must also be completely independent of the company they are auditing. Under the Companies Act 2006, a person cannot be an auditor if they are:
Initially, the auditor examines the company’s business structure, the nature of its operations, revenue sources, bank accounts, and accounting system. This enables the auditor to identify high-risk areas and determine the scope of necessary verification.
Next, the auditor reviews source documents and accounting records. They analyse bank statements, contracts, invoices, payment documents, and other supporting records to ensure that all transactions are accurately reflected in the accounting system.
The following aspects get the auditor’s particular attention:
Where necessary, the auditor may request additional documents or explanations from the company’s director or accountant.
Upon completion of the audit, the auditor issues a report expressing a professional opinion on the accuracy of the financial statements.
Based on their findings, the auditor issues a report, which may contain various types of opinions.
The most favourable outcome is an unqualified (or ‘clean’) opinion, which confirms that the financial statements fairly present the company’s financial position and comply with applicable standards.
In certain cases, an auditor may issue a qualified opinion. This occurs, for example, if a company has failed to prepare consolidated financial statements despite having subsidiaries, or if specific information was unavailable to the auditor.
A qualified opinion does not prevent the filing of financial statements with tax authorities, though banks or investors may raise questions.
In rare instances, an adverse opinion or a disclaimer of opinion may be issued if the auditor is unable to obtain sufficient evidence regarding the reliability of the financial statements. Such situations are considered serious violations and require the financial statements to be revised.
To qualify for an audit exemption, a UK company must fall into one of the two categories:
Dormant Companies
A company is considered dormant if there have been no ‘significant accounting transactions’ in the accounting period.
When classifying a company as dormant, the following transactions are excluded from the list of ‘significant’ ones (i.e., the company does not lose its dormant status if these occur):
Small Companies
The criteria for small companies are set out above (see ‘Company Size Classification’).
A company cannot qualify as small if it is:
Under Section 476 of the Companies Act, shareholders have the right to request an audit, notwithstanding any audit exemption. If such a request is made, the company is required to prepare audited financial statements.
The responsibility for classifying the company as small or dormant rests with the director. If the director determines that the company meets the requirements of Section 477 or Section 480 of the Companies Act and is therefore eligible for an audit exemption, they must include a corresponding statement in the financial statements, citing the relevant section of the Act. The director must also declare that the shareholders have not exercised their right to request an audit.
Beyond meeting regulatory requirements, an audit holds significant practical value for a company’s operations. Audited financial statements may be required for:
Failure to provide audited financial statements can significantly limit a company’s ability to do business and interact with financial institutions.
The filing deadline for private companies and LLPs is 9 months after the accounting reference date (ARD).
Limited companies submit their financial statements to Companies House and HMRC (alongside their Company Tax Return). LLPs file financial statements with Companies House but not with HMRC (provided their aggregate annual turnover is less than GBP 15 million).
Until 31 March 2026, a free online service known as ‘File your accounts and Company Tax Return’ – a joint filing system operated by Companies House and HMRC – was available. Companies used this portal to submit both financial statements and tax returns to both agencies simultaneously.
However, from 1 April 2026, it is mandatory to use commercial software for filing annual accounts and tax returns with HMRC.
Submitting annual accounts to Companies House can currently be done in three ways, although a shift to using only commercial software is planned for 1 April 2028:
Liability for the late filing of financial statements applies to both the company and its directors (Sections 451–453 of the Companies Act, under the heading ‘Failure to file accounts and reports’).
Company’s Liability
Penalties
Companies House automatically imposes scaled financial penalties based on the length of the delay and whether the company is private or public. The following fines apply to private companies:
| Delay | Fine |
| up to 1 month | GBP 150 |
| 1 to 3 months | GBP 375 |
| 3 to 6 months | GBP 750 |
| over 6 months | GBP 1,500 |
If accounts are late two years in a row, the fines are doubled.
Compulsory strike-off
Persistent late filing can lead Companies House to strike the company off the register.
Director’s Liability
Personal criminal liability
If a company’s financial statements are not submitted by the statutory deadline, every director holding office at that time commits an offence. Thus, the Companies Act 2006 imposes personal criminal liability on each director for any failure to meet the filing deadlines for the company’s accounts.
Outsourcing the making of financial statements to an accountant does not release a director from personal liability. A defence is available only if the director can prove that all reasonable steps were taken to ensure compliance. This line of defence sets a high evidentiary threshold; therefore, to mitigate the risk of personal criminal liability, it is essential to have in place formalised and documented procedures confirming that such steps were taken.
Penalties
The consequences of conviction on this offence include personal liability for each director in the form of an unlimited fine, as well as a criminal record.
Disqualification
In the most serious cases of persistent non-compliance with corporate law, Companies House may also seek disqualification, which can bar an individual from acting as a director for up to 5 years.
All UK companies are required to prepare and submit a Confirmation Statement (Form CS01) to Companies House annually, at least once every 12 months. It is not a financial statement and does not contain any financial figures. The form simply requires the verification and confirmation (or updating) of the company’s general registration details held in the register:
The form must be submitted within 14 days of the end of the reporting period (12 months from the company’s incorporation date or the date the previous Confirmation Statement was filed). This requirement applies even to companies that have not conducted business and have had no changes over the past year.
Failure to file the Confirmation Statement may result in a fine of up to GBP 5,000 and the company being struck off the register.