Filing of Dormant Company Tax Return
Price
2 200 USD

Accounting & Bookkeeping
Mandatory; primary documentation must be kept for at least 7 years
Financial Statements Preparation
Annually
Accounting standards
International Financial Reporting Standards (IFRS)
Consolidated Financial Statements
Mandatory if the company has active subsidiaries
Dormant Reporting Option
Available, but rules depend entirely on the license type
Filing Financial Statements with the Registry
Mandatory for Mainland companies and the majority of Free Zones
Filing Financial Statements with the Tax Authority
Mandatory upon submission of the annual corporate tax return
Statutory Audit
Mandatory for Mainland companies, residents of most Free Zones, companies with revenues over AED 50,000,000, and Qualifying Free Zone Persons (QFZP)
Dormant Status
Officially non-existent in the UAE legal framework
Corporate Tax Return
Must be filed within 9 months following the end of the financial year
Annual Return
Replaced by the annual trade license renewal
The company is required to continuously maintain its bookkeeping records: recording revenues, expenses, bank account movements, agreements, contracts, and other business transactions throughout the financial year. The records must be retained for at least 7 years and serve as the foundation for financial statement preparation.
Maintaining accounting records is mandatory for all UAE entities without exception, including offshore structures.
Following the end of the financial year, a complete package of financial statements is generated in accordance with International Financial Reporting Standards (IFRS) or IFRS for SMEs (for small and medium-sized enterprises).
For holding structures registered with the Federal Tax Authority (FTA) as a single tax group, consolidated financial statements must be prepared.
The prepared financial statements are submitted to an independent licensed auditor in the UAE.
Audit is mandatory for:
A tax computation is prepared based on the financial statements and the auditor’s report, if an audit is mandatory.
The net accounting profit is adjusted according to UAE tax laws, factoring in exempt income, non-deductible expenses, and the carry-forward of tax losses.
The tax return form is completed online via the Federal Tax Authority (FTA) portal (EmaraTax).
The company uploads its tax return to the FTA portal and pays the applicable corporate tax (9% on taxable profits exceeding AED 375,000).
The return must be filed, and the tax paid, within 9 months following the end of the company’s financial year. No extensions to this statutory deadline are permitted under the UAE laws.
In addition to tax filings and audits, UAE companies must fulfill ongoing corporate governance requirements that are not directly tied to taxation:
Executed annually. This process verifies the legal address (tenancy contract or flexi-desk lease), covers Registrar fees, and requires uploading the current auditor’s report in specific Free Zones. Failure to renew the license triggers an automatic freeze of the corporate bank account.
Required within 15 days of any structural changes, as well as during the annual license renewal.
Applicable if the company employs staff in the UAE. Salary disbursements must be processed strictly through the state-monitored Wages Protection System (WPS).
The cost of bookkeeping and accounting services in the UAE is tailored to the individual parameters of your business.
The final pricing is determined based on annual revenue, the volume of monthly bank transactions, the number of primary financial documents (invoices) processed, and the selected service package.
Bookkeeping compliance in the UAE relies on primary documentation. Retained records must include:
All records must be structured to enable the Federal Tax Authority (FTA) to seamlessly verify tax returns and evaluate the company’s financial position during a routine audit. Entities utilizing cloud-based accounting systems must guarantee that records remain fully accessible, secure, and retrievable throughout the mandatory statutory retention period.
Under Cabinet Decision No. 75 of 2023, failure to maintain proper accounting records or adhere to statutory retention rules results in an administrative fine of AED 10,000 for the first violation, escalating to AED 20,000 for repeated infractions within a rolling 24-month period.
In accordance with Article 25 of Federal Decree-Law No. 28 of 2022 on Tax Procedures, evading administrative fines or tax dues carries criminal penalties, including imprisonment and/or punitive fines of up to 300% of the total evaded amount.
Similar criminal liabilities apply to the deliberate submission of fraudulent data, or the concealment and destruction of corporate records.
If an FTA tax auditor discovers a complete absence of corporate ledgers and books, the authority reserves the legal right to independently calculate the company’s taxable base utilizing indirect estimation methods, which typically results in significantly inflated tax liabilities.
In accordance with UAE legislation, the responsibility for the preparation and accuracy of financial statements rests solely with the company’s management. Directors are legally required to ensure that financial reports are compiled annually for each financial year.
Financial statements must present a true and fair view of the company’s actual financial position as of the reporting date and its financial performance for the preceding period.
Article 349 of UAE Commercial Companies Law No. 32 of 2021 establishes criminal liability for executives, auditors, and liquidators who deliberately misrepresent or distort financial reporting.
Concealing the company’s true financial standing carries penalties including imprisonment for a term ranging from 6 months to 3 years, and/or administrative fines between AED 100,000 and AED 500,000.
Financial accounts and statements in the UAE must be prepared in compliance with International Financial Reporting Standards (IFRS).
Full IFRS Framework is mandatory for major enterprises with an annual revenue exceeding AED 50,000,000, public joint-stock companies, financial institutions, and residents of specific highly regulated financial free zones (such as DIFC and ADGM).
IFRS for SMEs Framework is permitted for small and medium-sized enterprises. This framework significantly reduces disclosure requirements and simplifies the accounting treatment of complex financial instruments, provided the entity is non-public and its turnover falls within established criteria.
Individual Free Zone Authorities retain the legal right to mandate specific versions or localized compliance frameworks under the umbrella of general IFRS rules.
Core IFRS principles implemented in UAE accounting:
Financial statements may be prepared in UAE Dirhams (AED) or any foreign currency that serves as the primary currency of the business (such as USD or EUR). No prior regulatory approval is required.
The Federal Tax Authority (FTA) requires all final figures on the EmaraTax portal to be submitted in AED for corporate tax return filings. If the accounting records are maintained in a foreign currency, the financial figures must be converted into AED using the official exchange rate published by the Central Bank of the UAE as of the financial year-end date.
The first financial period:
All subsequent financial reporting periods must span exactly 12 months.
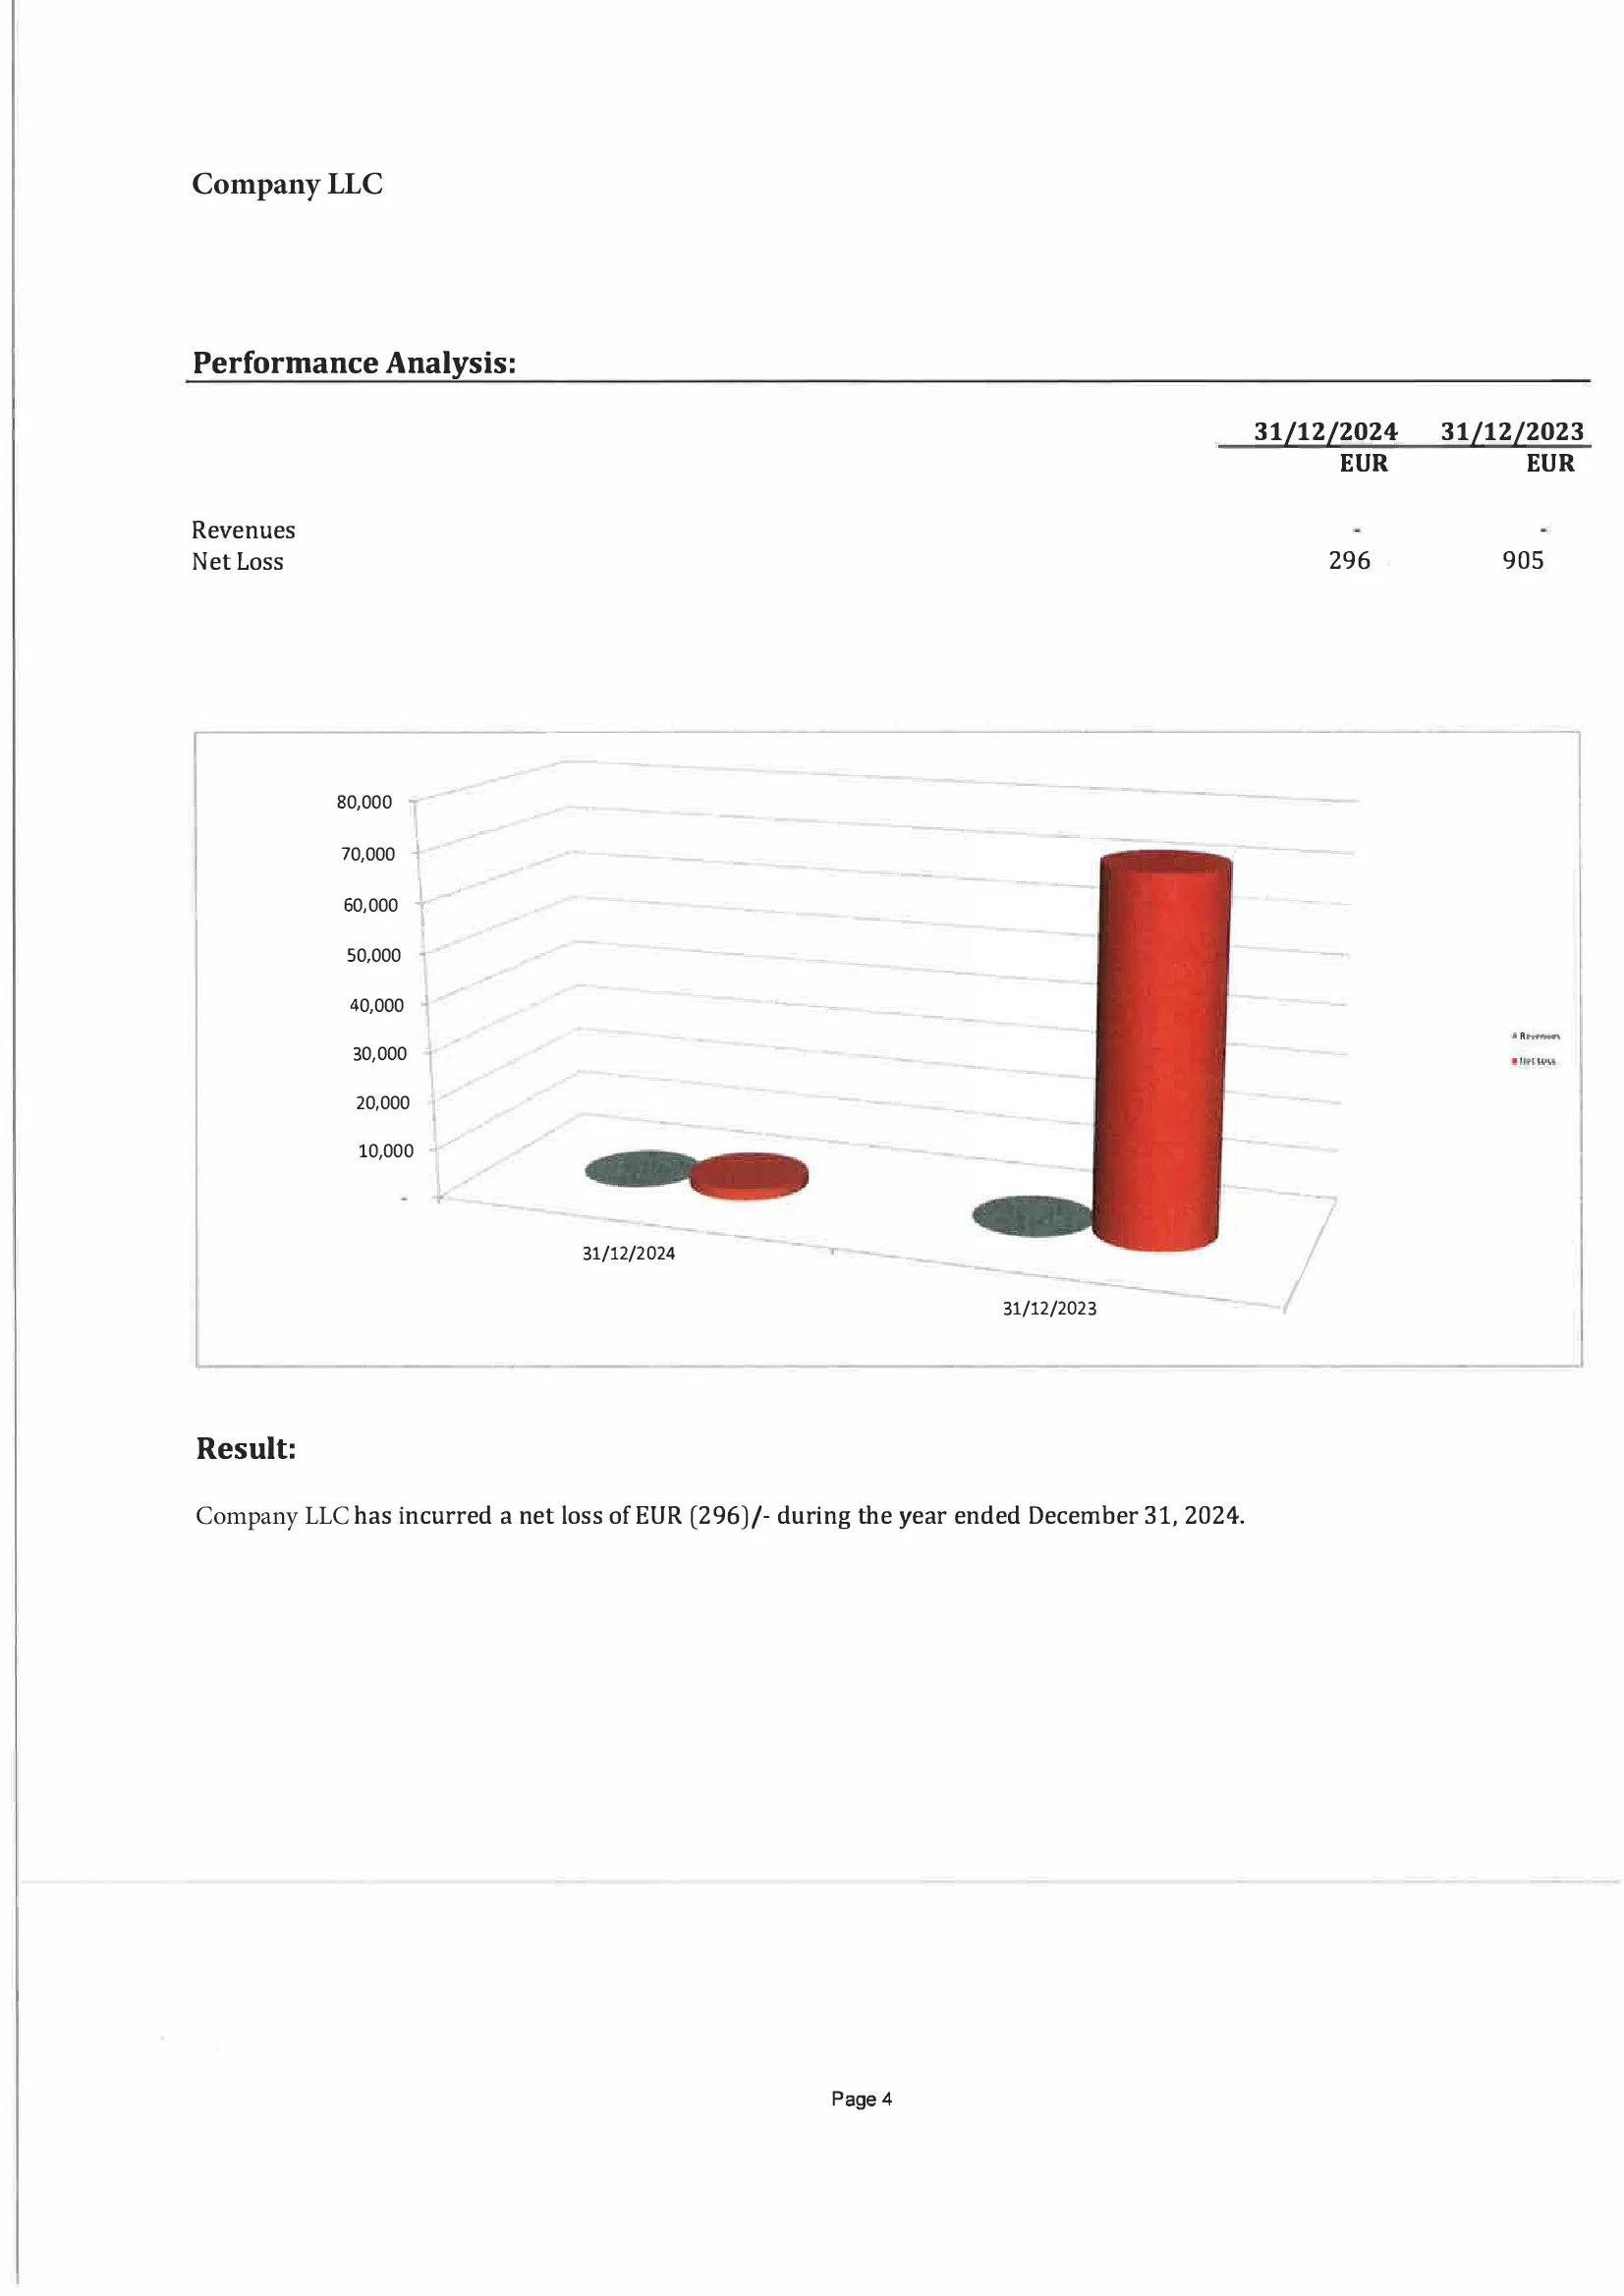
An analytical report supplementing the financial statements and containing:
The report enables users to assess the company’s performance over time, identify key trends, and gain a deeper understanding of its financial position and operational efficiency.
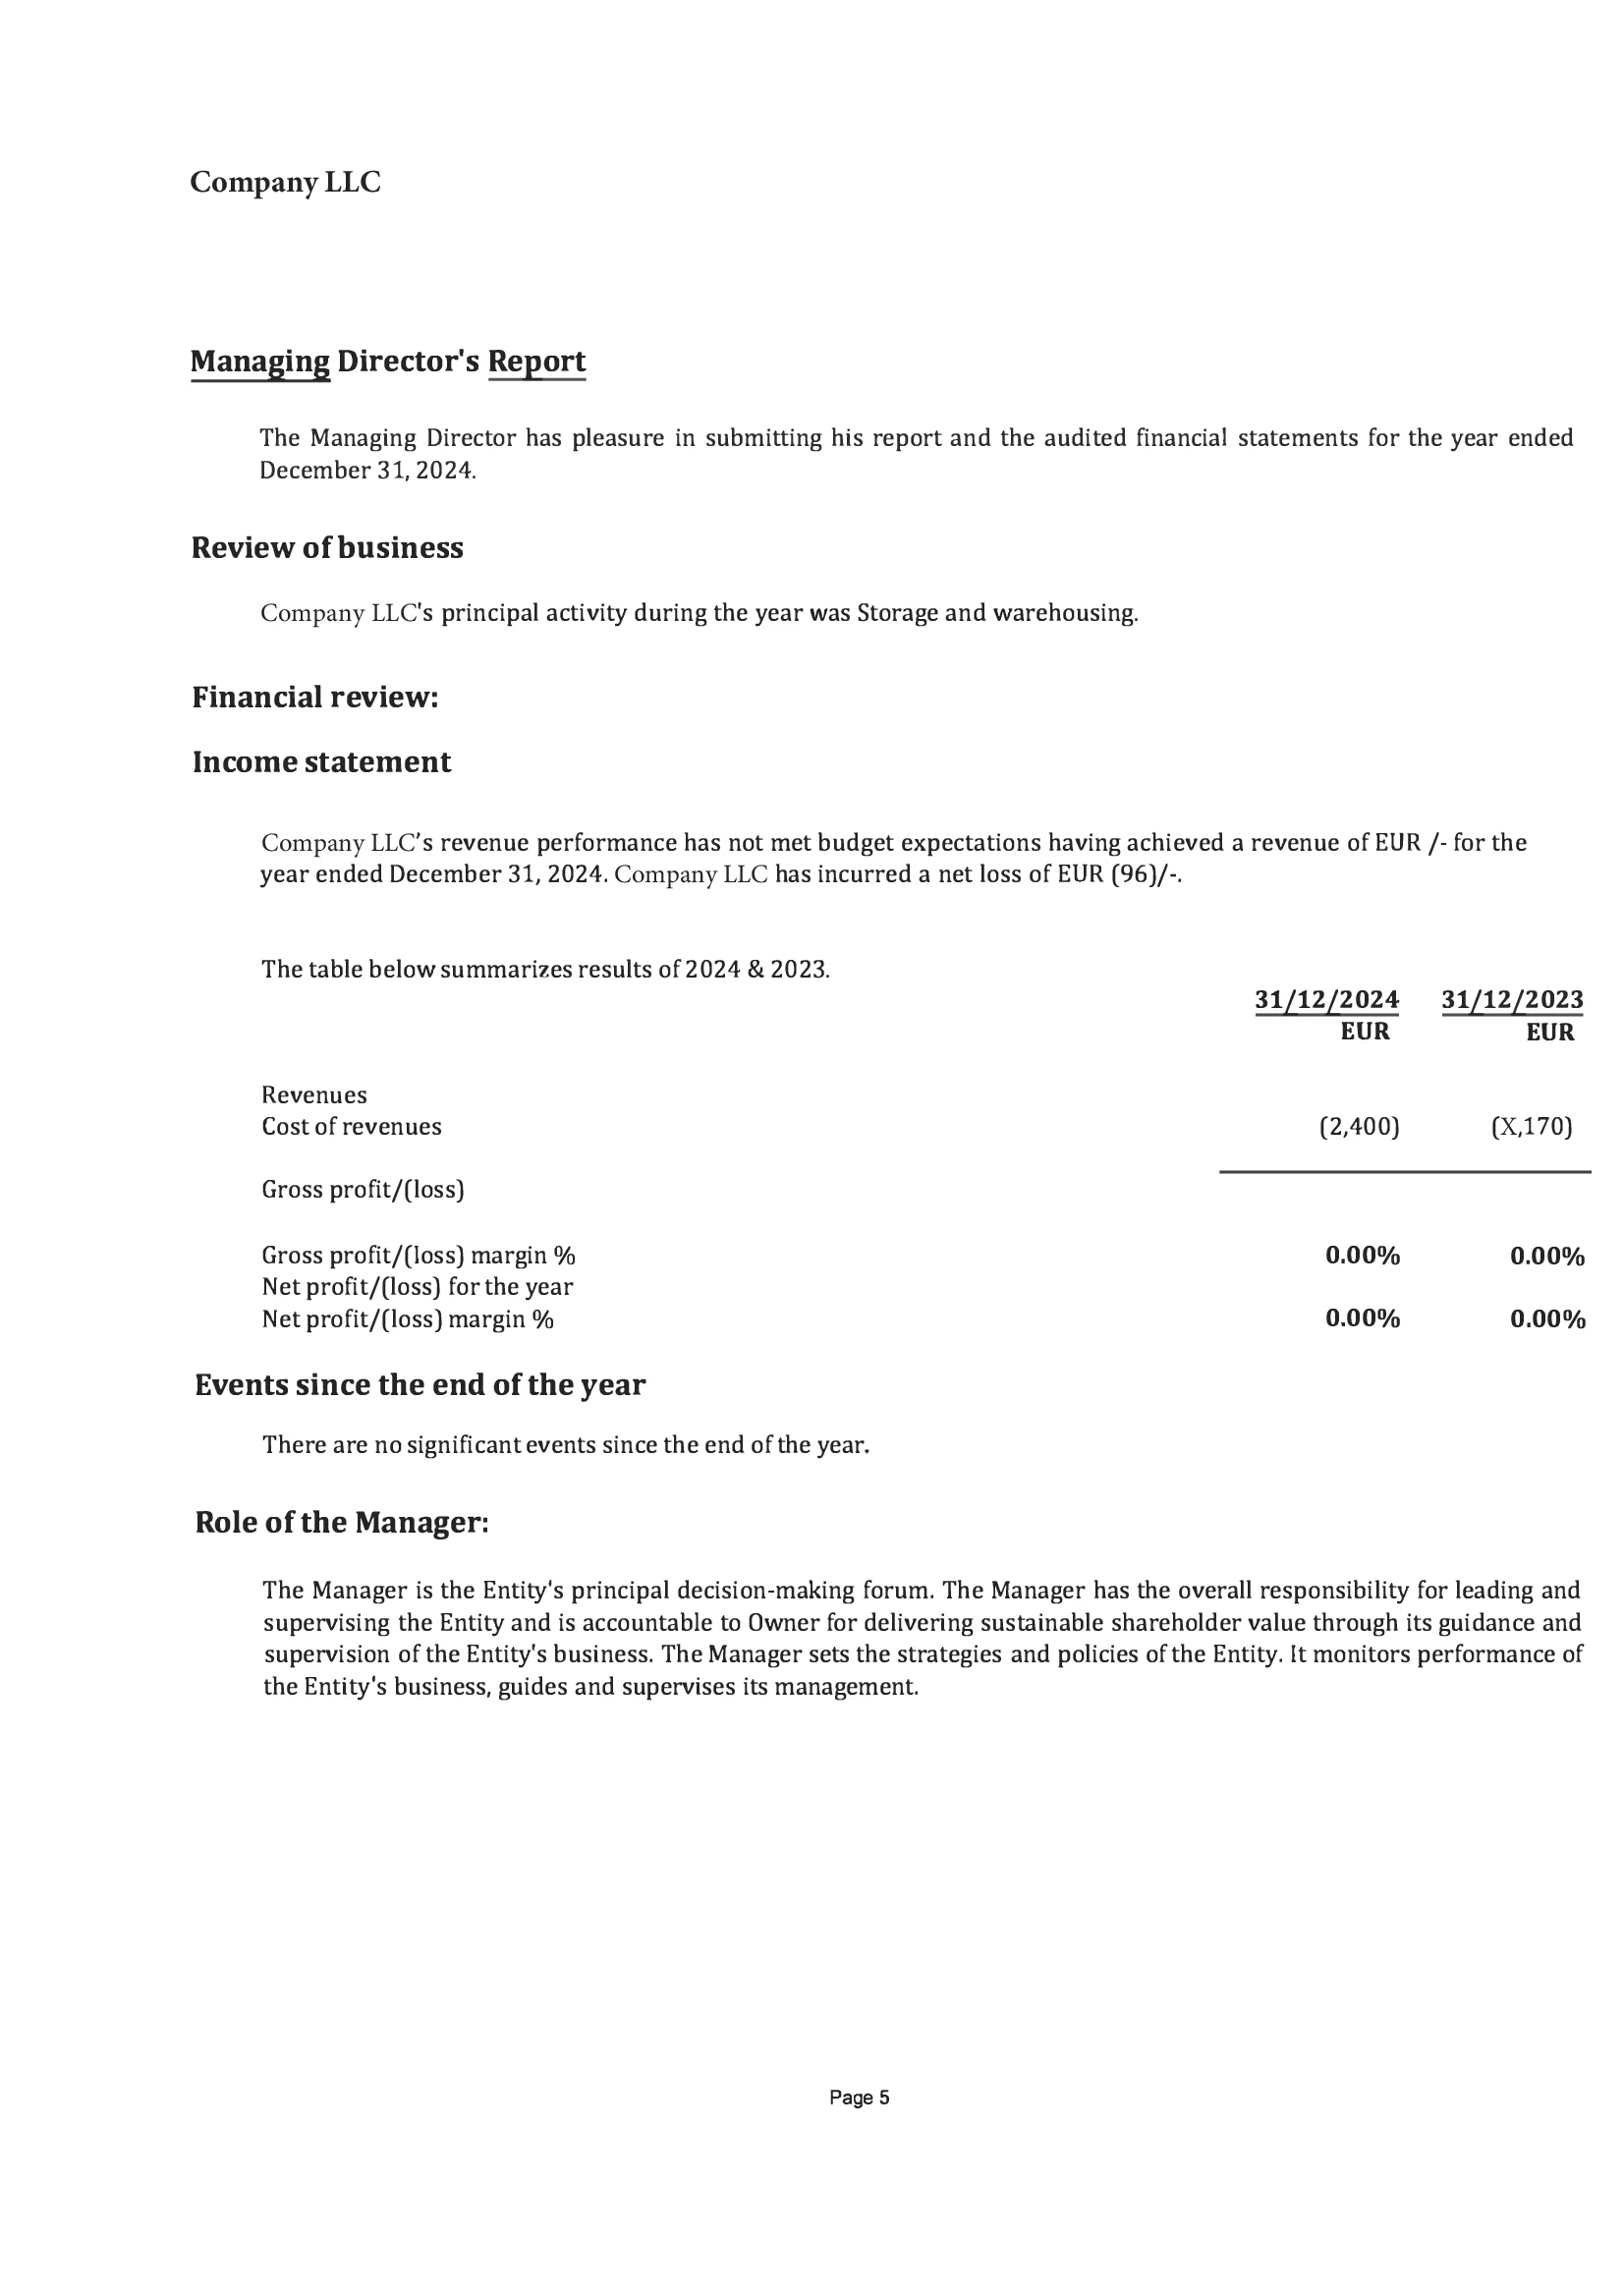
Contains an overview of the Company’s activities during the reporting period, prepared by management.
Includes information on key events, financial and operational performance, principal risks, future development prospects, significant changes in the Company’s operations, as well as management’s acknowledgment of its responsibility for the preparation of financial statements and compliance with applicable legal and corporate governance requirements.
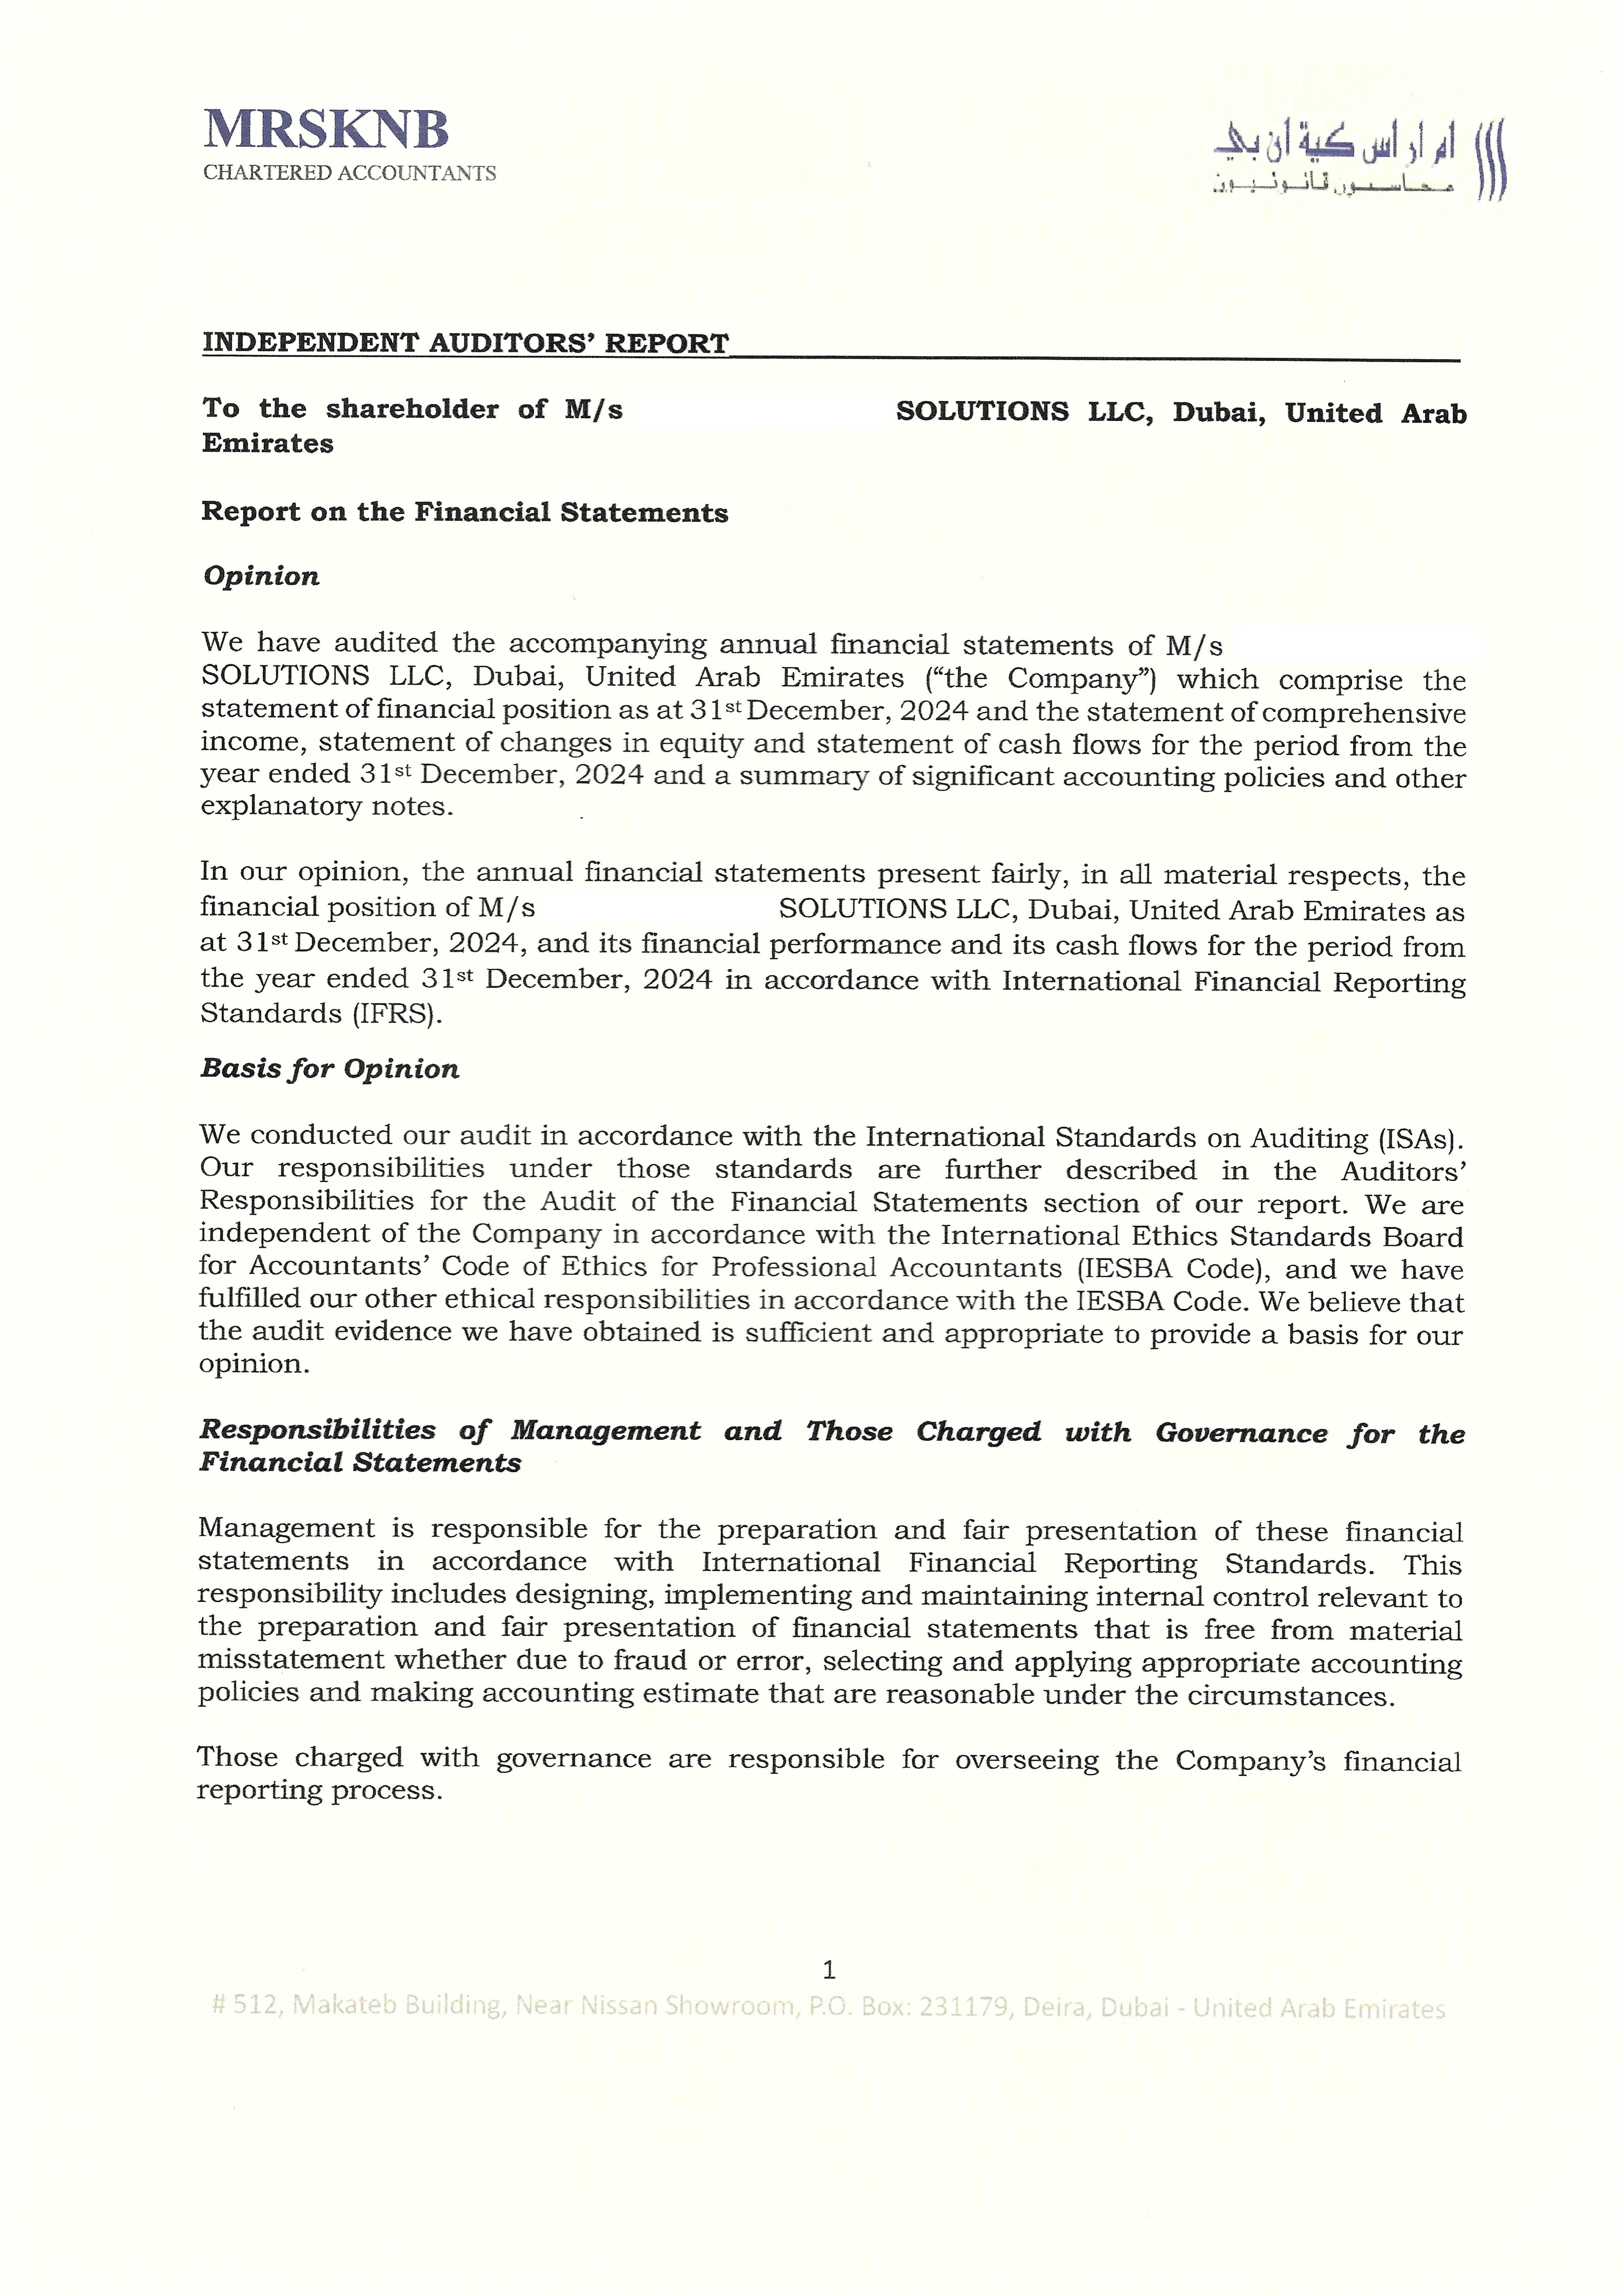
The auditor’s opinion on whether the financial statements have been prepared, in all material respects, in accordance with International Financial Reporting Standards (IFRS).
The report presents the auditor’s conclusions based on the audit procedures performed, provides an opinion on the fair presentation and completeness of the financial information, and identifies any material misstatements, qualifications, or limitations identified during the audit.
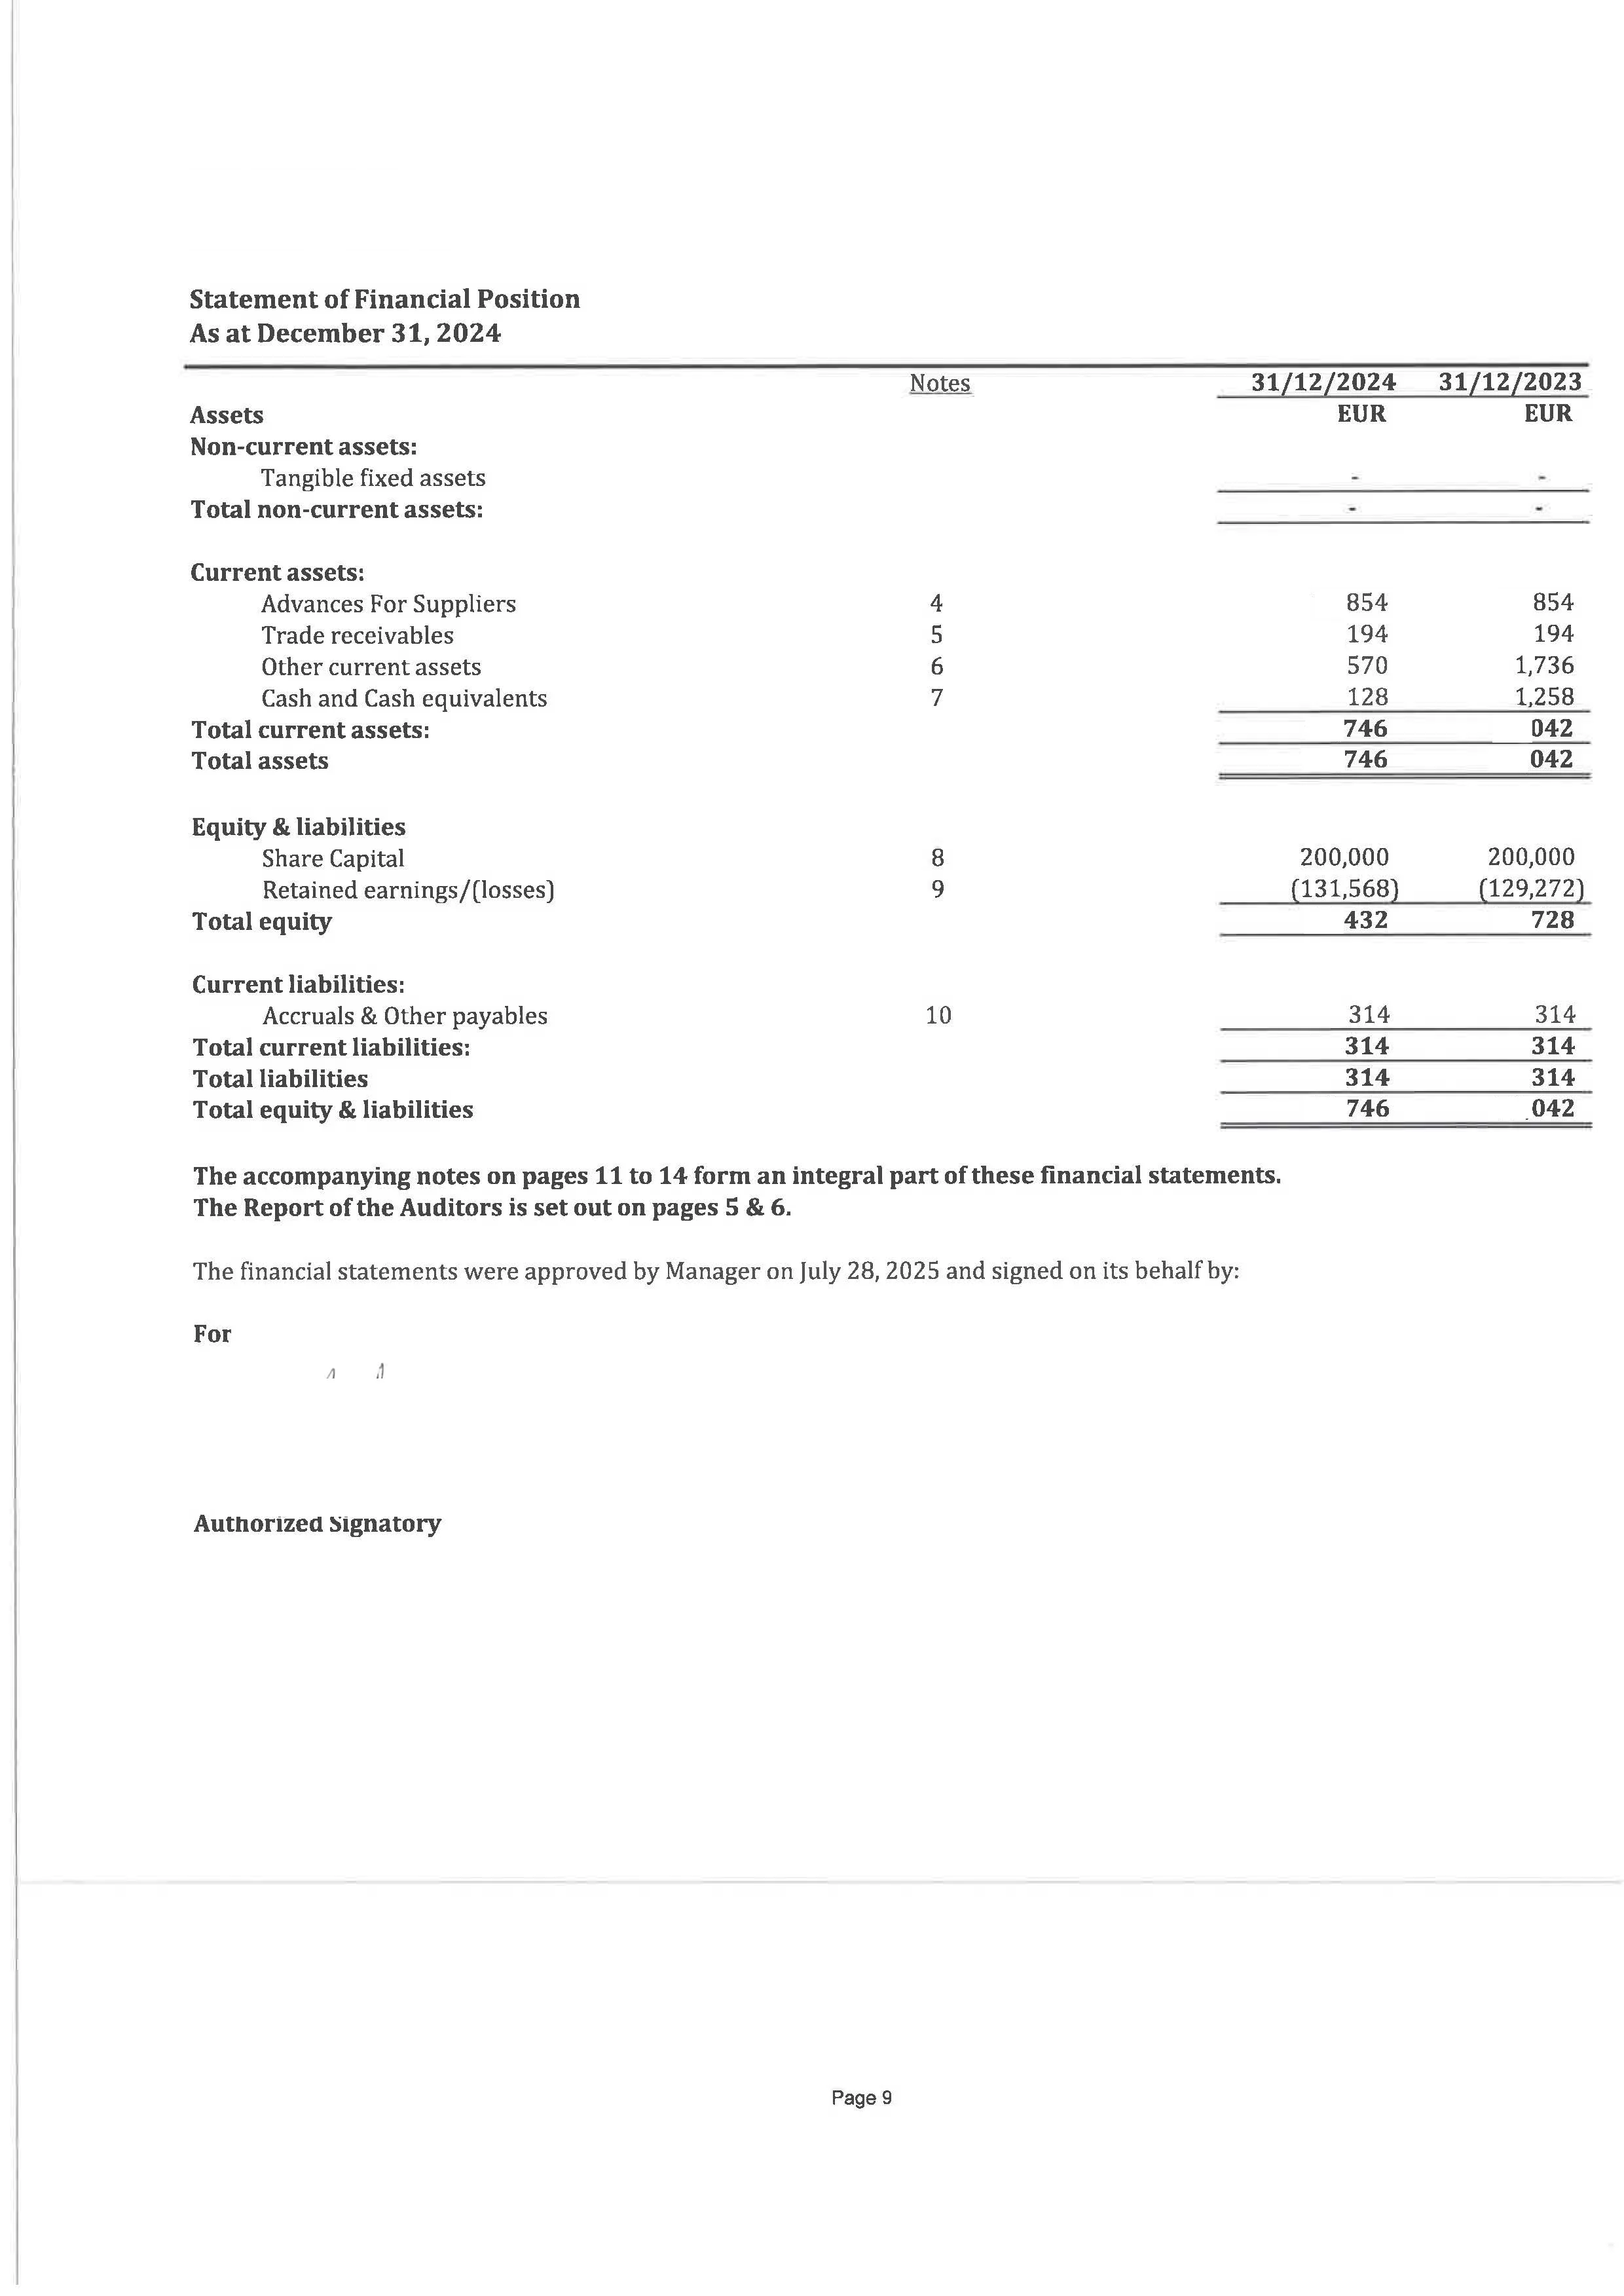
Presents the Company’s financial position as at the reporting date.
Provides information on the Company’s assets, liabilities, and equity, enabling an assessment of its asset structure and sources of financing.
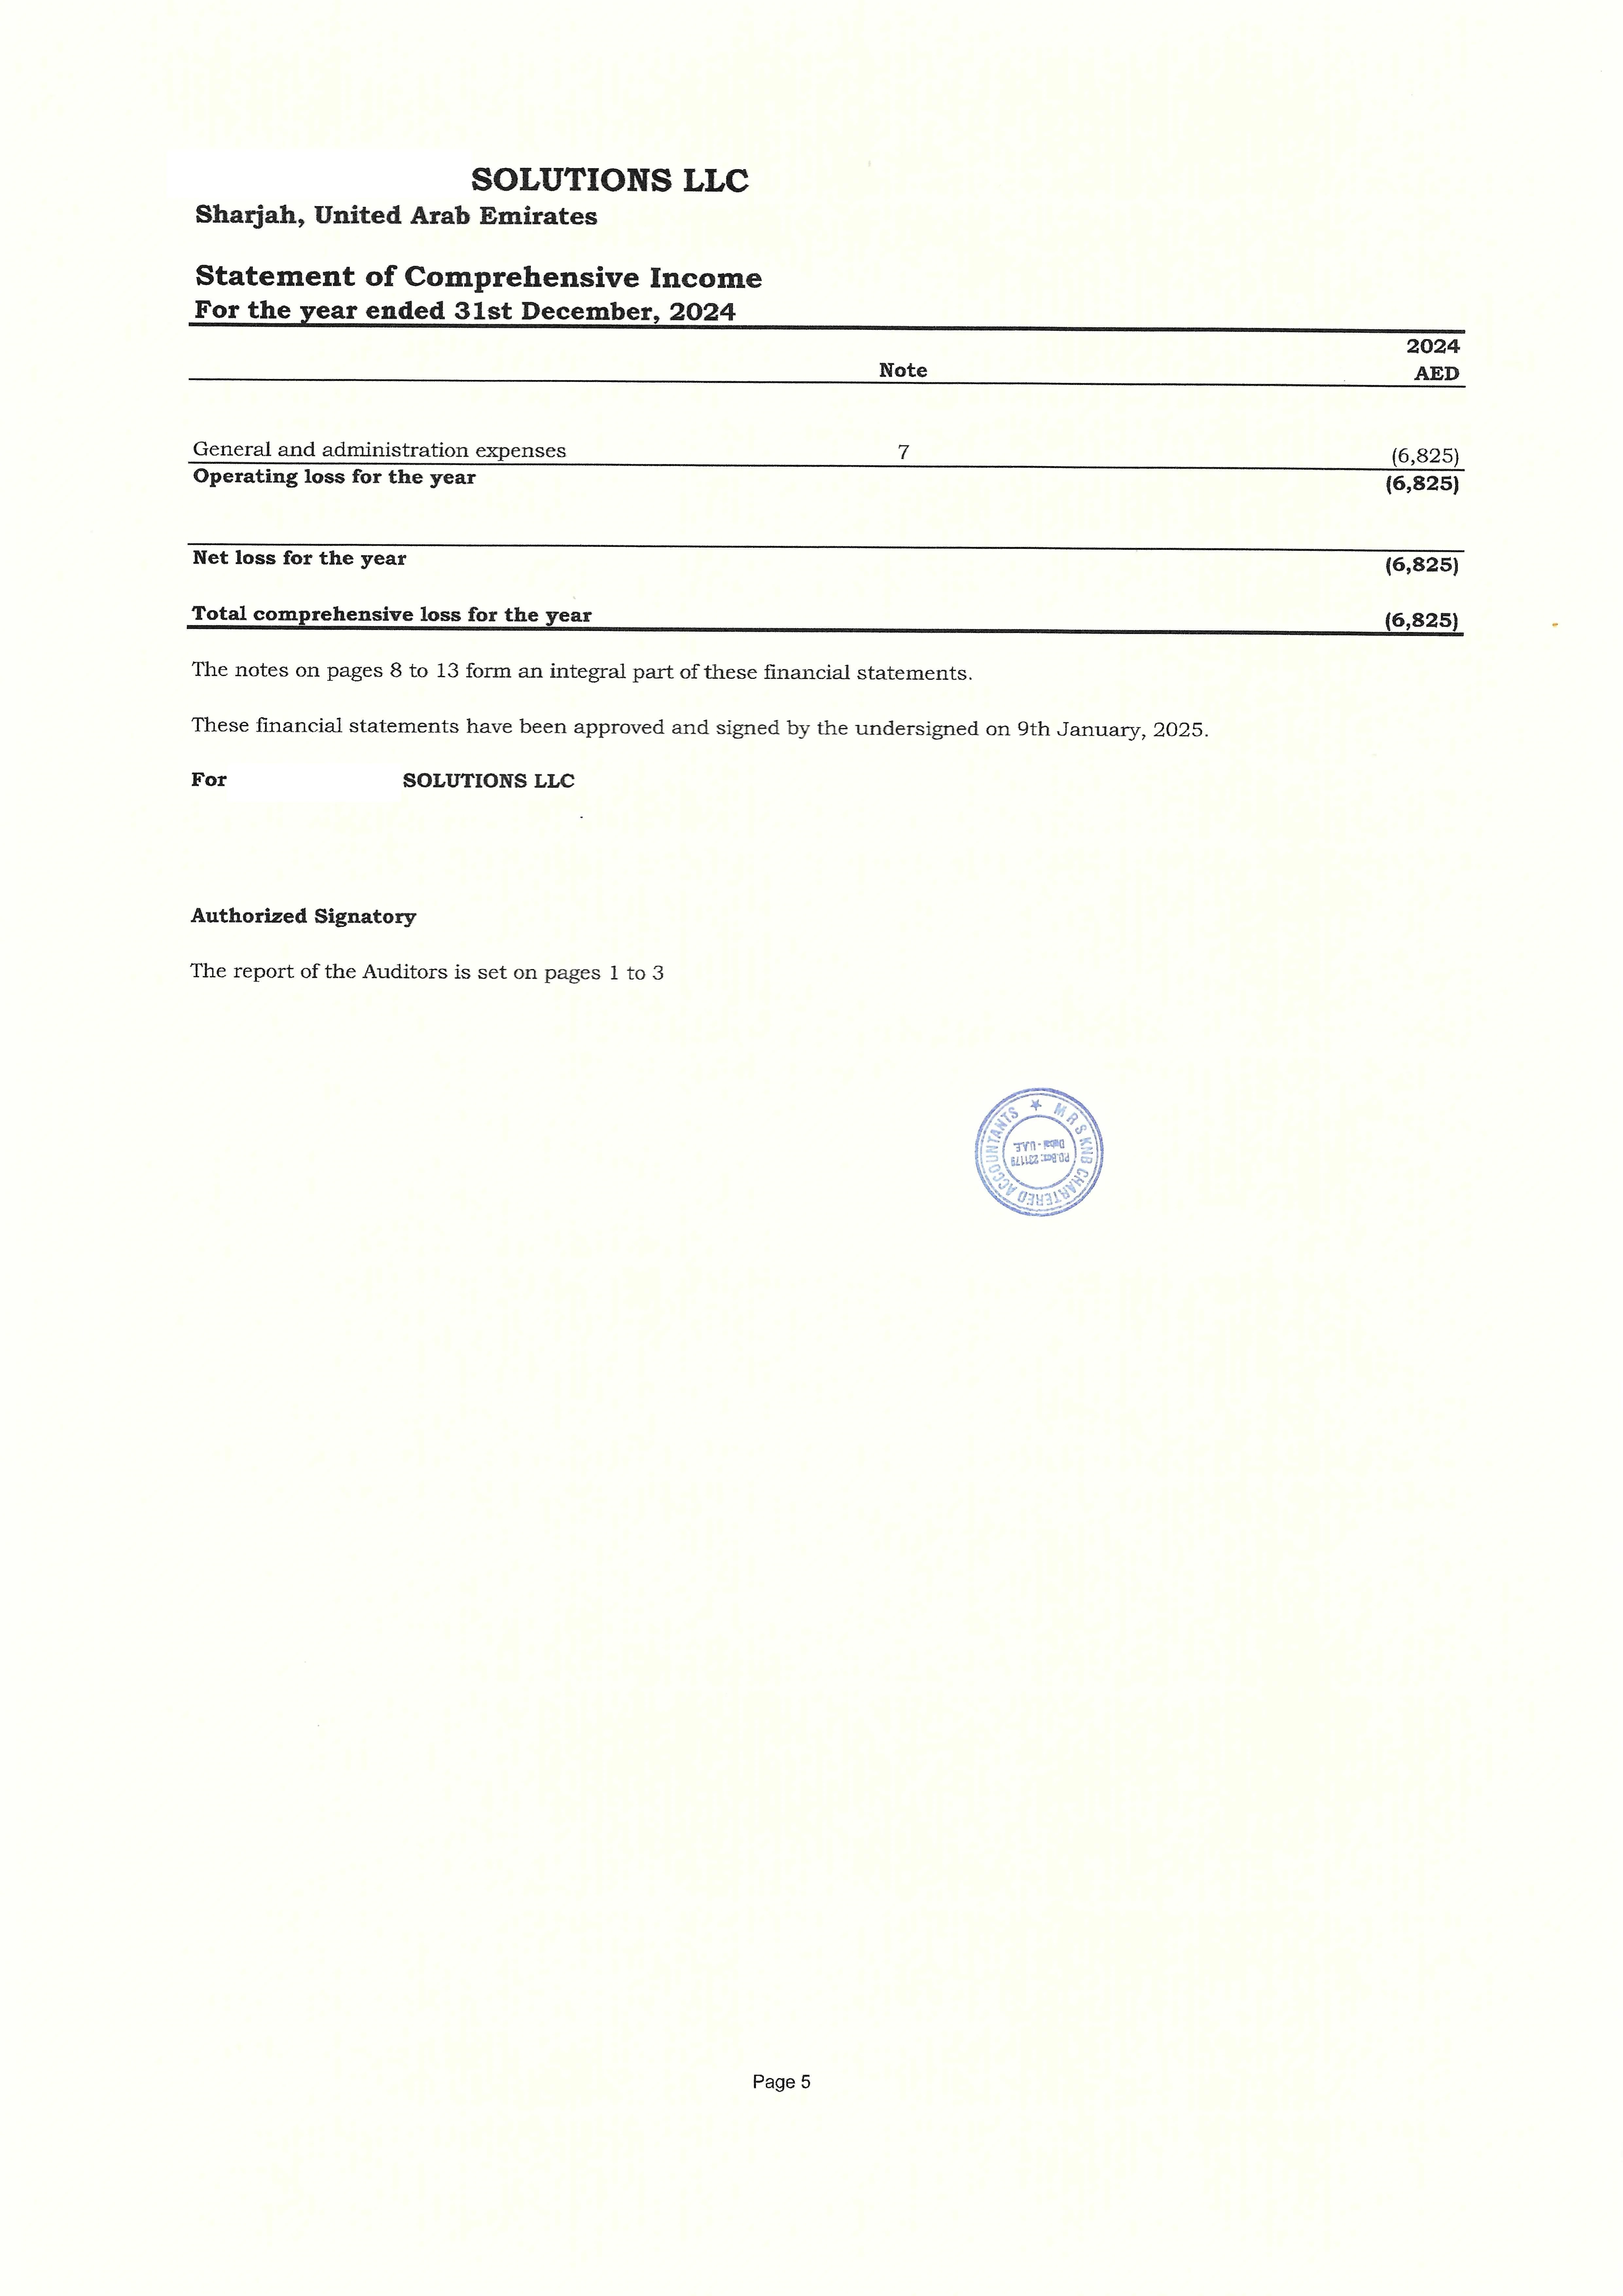
Presents the Company’s financial performance for the reporting period.
Provides information on revenue, expenses, profit or loss, and other comprehensive income in accordance with International Financial Reporting Standards (IFRS).
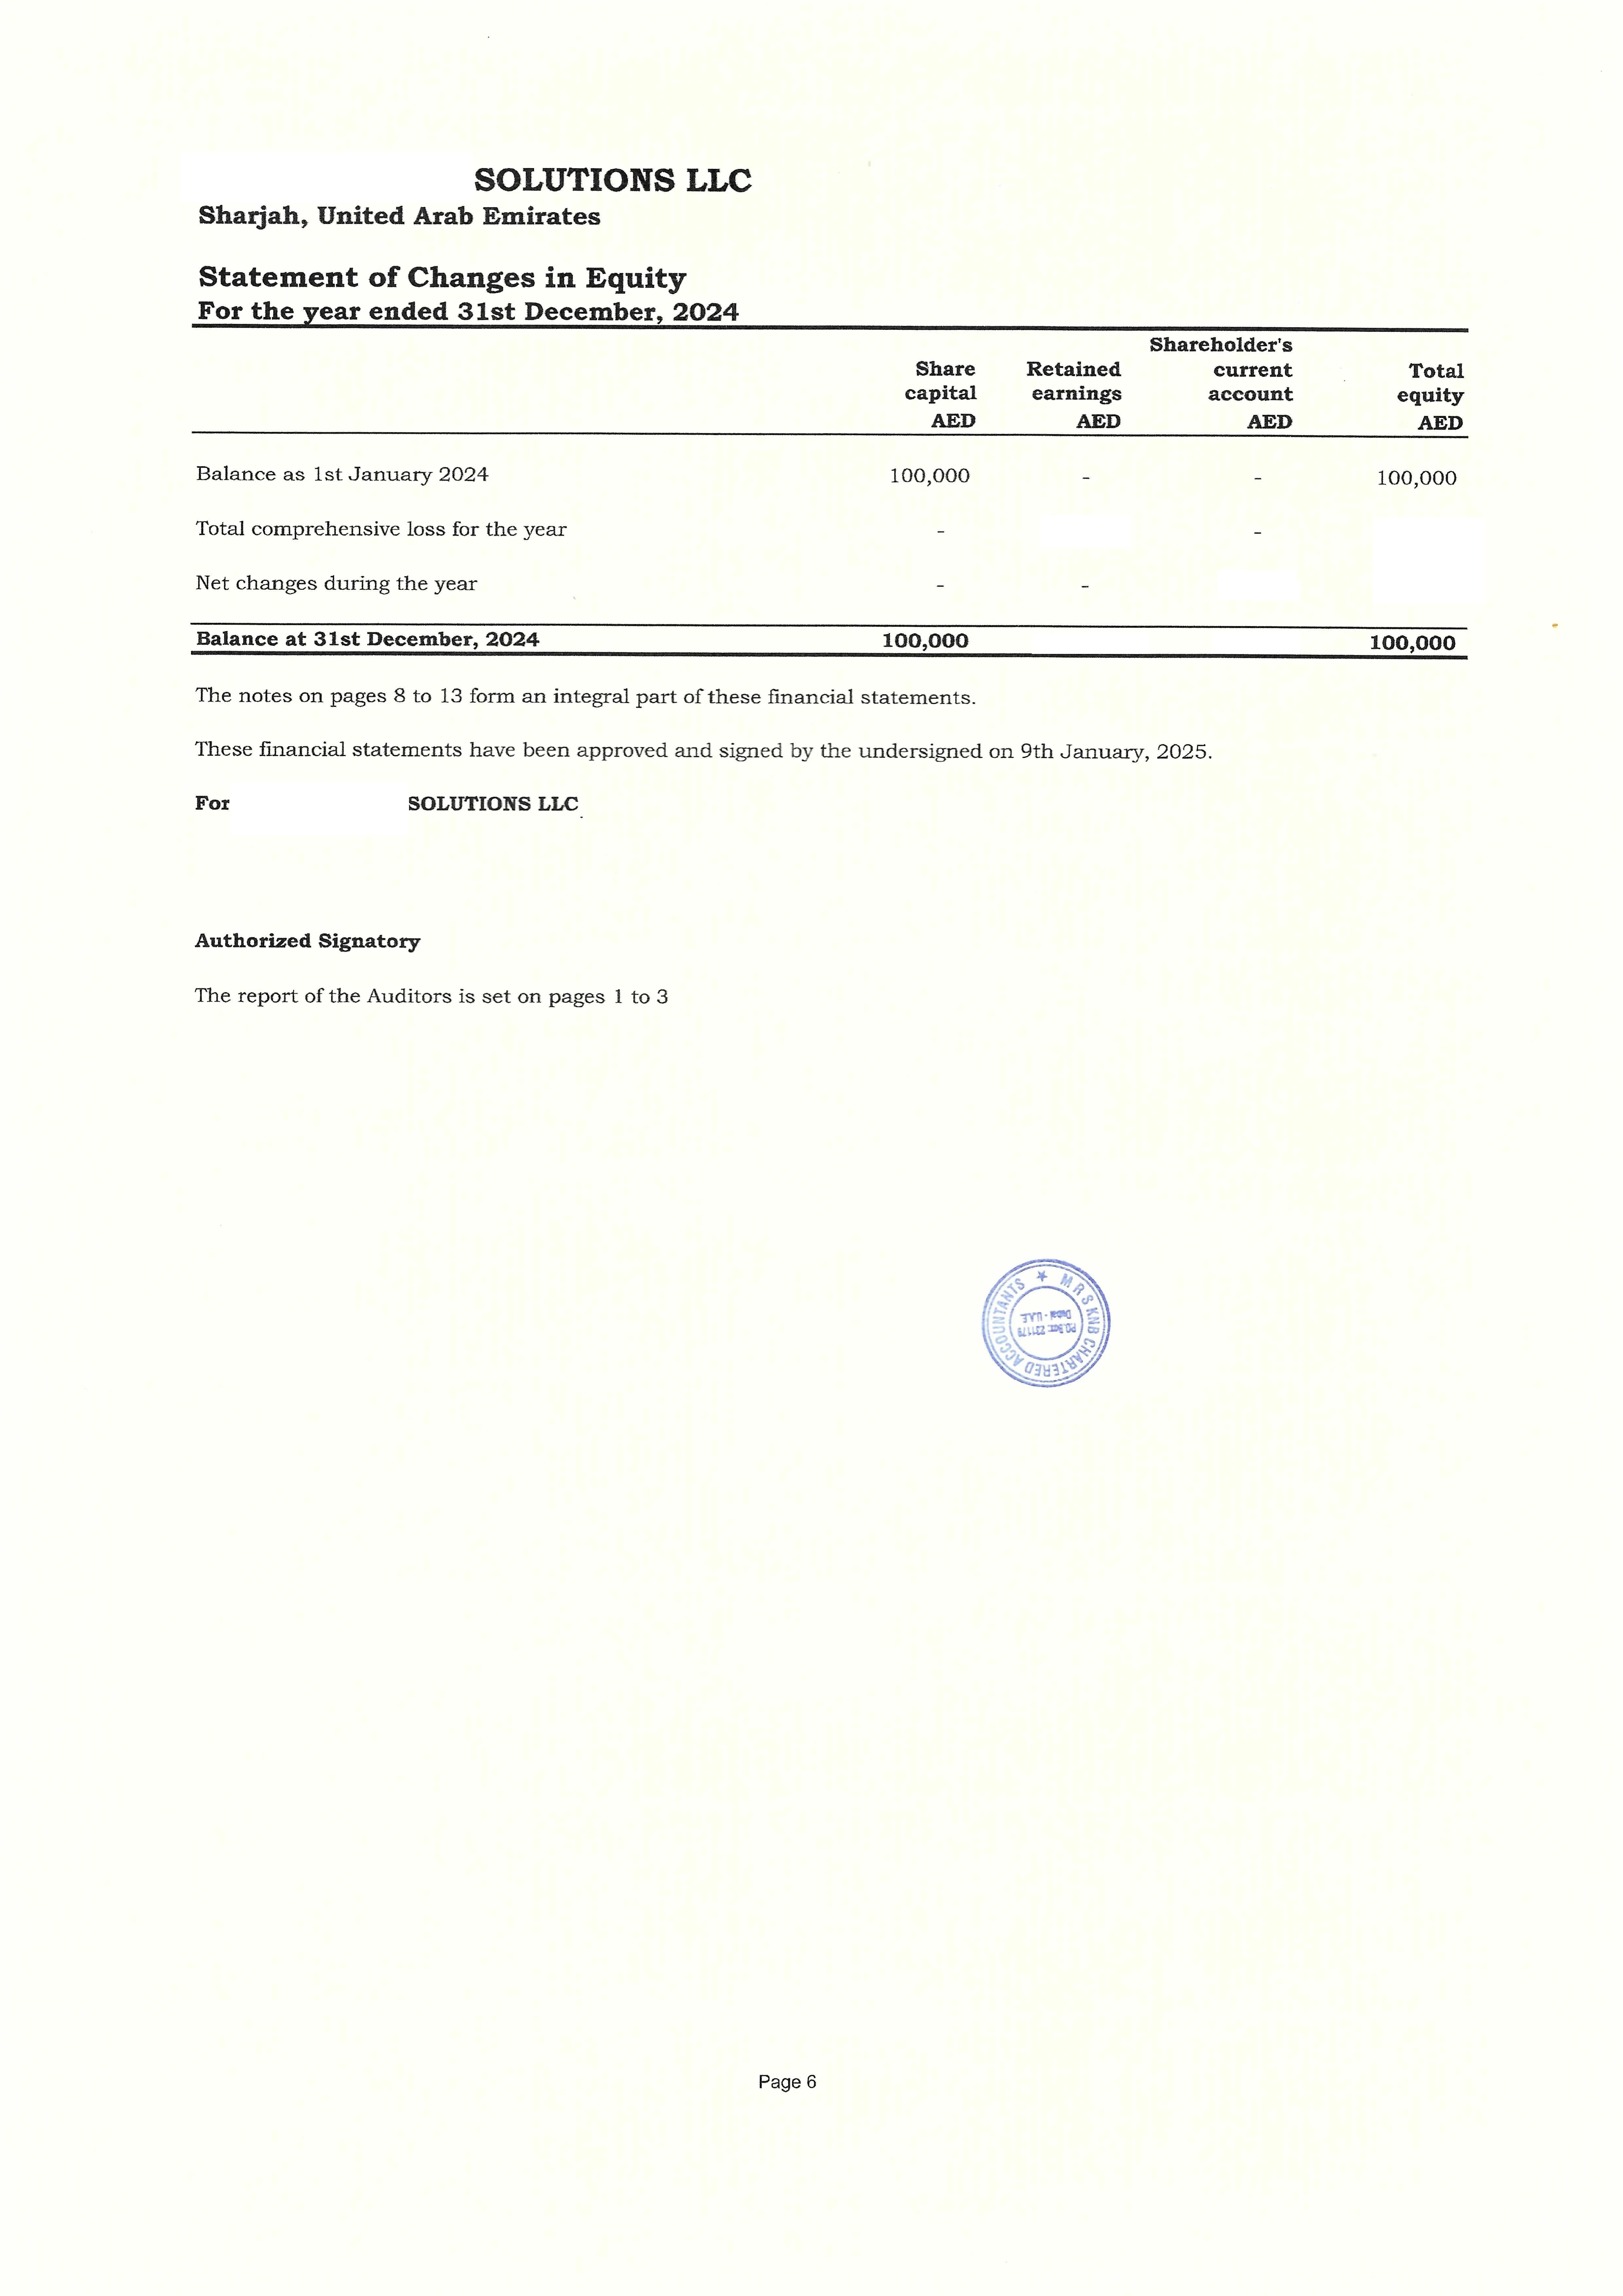
Presents changes in the Company’s equity during the reporting period.
Provides information on profit distributions, dividend payments, additional capital contributions by shareholders, and other changes in equity.
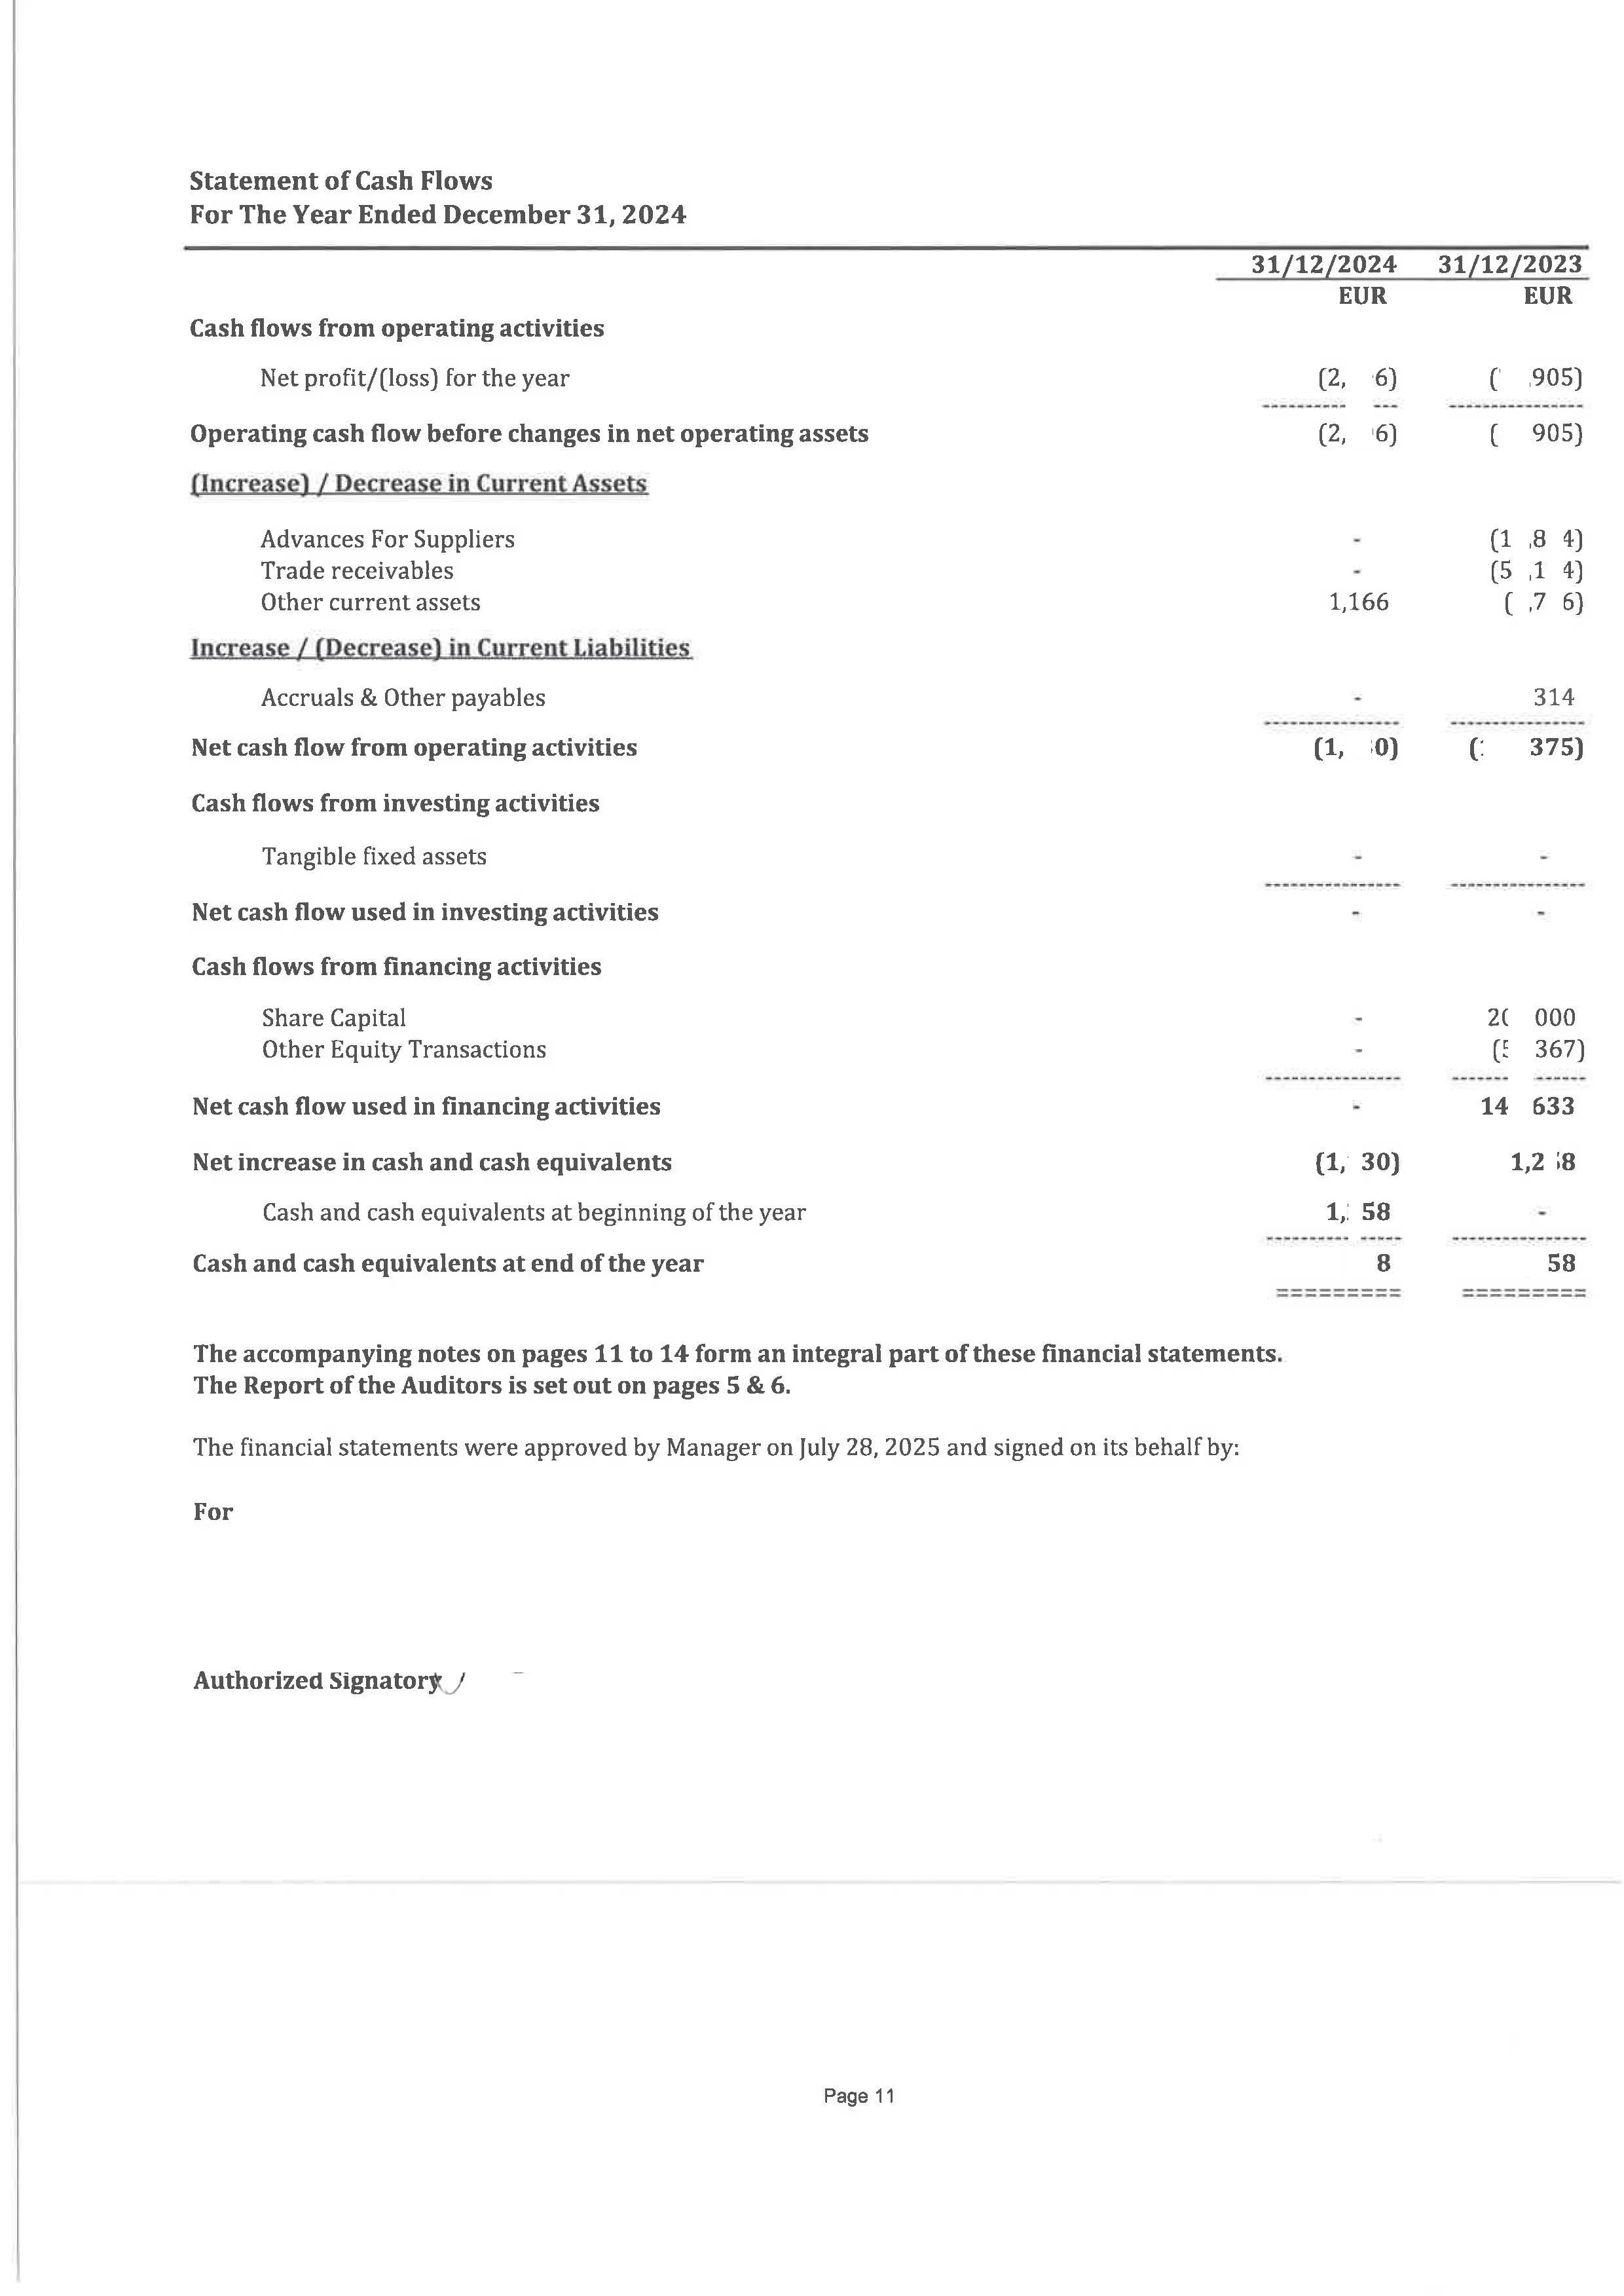
Provides information on cash inflows and outflows from operating, investing, and financing activities.
Enables an assessment of the Company’s ability to generate cash flows and meet its financial obligations.
In accordance with Federal Decree-Law No. 32 of 2021, companies are required to maintain records under international accounting rules. The implementation of the IFRS framework implies that consolidation criteria are governed by IFRS 10, under which a UAE parent company is recognized as a controlling entity if it:
Failure to comply with consolidation requirements will result in the independent auditor issuing a Qualified Opinion, which triggers additional tax audits by the Federal Tax Authority (FTA) and can lead to a refusal to renew the trade license.
In line with IFRS guidelines, a UAE parent company may be exempt from preparing consolidated financial statements if it is itself a subsidiary of a higher-tier ultimate holding company, and its ultimate beneficial owners have agreed to the non-consolidation.
In accordance with Federal Decree-Law No. 47 of 2022 on Corporate Tax, a unique form of consolidation is available: a parent company can consolidate its subsidiaries into a single Tax Group to file a single tax return, pay a unified tax, and offset losses.
Tax Consolidation Conditions:
An audit in the Emirates may only be conducted by an independent licensed auditor who is:
The EAAA is responsible for the registration of auditors and professional association membership. The objectives of the Association include:
The report serves as the foundation for filing the annual corporate tax return with the Federal Tax Authority.
Auditors bear full professional and legal liability for the accuracy and authenticity of the issued auditor’s report.
Beyond regulatory compliance, an audit carries significant practical value for company operations. Audited financial statements may be required for:
The financial statements submission in the UAE is directly integrated with the corporate tax return, which is filed electronically via EmaraTax, the unified state portal of the Federal Tax Authority (FTA).
Financial statements are not submitted to the tax authority as a separate, standalone document. Instead, they serve as the underlying basis for the tax calculation, and all relevant financial metrics are entered into the tax form directly from the prepared financial accounts.
When completing a standard tax return, uploading the actual financial statement file is not always mandatory, but the company is legally required to have it finalized and available. During a random tax audit by the FTA, the financial statements are the first documents requested by tax inspectors.
The Federal Tax Authority views the financial statements (and the auditor’s report, if an audit is mandatory) as the primary documentary evidence verifying the figures declared by the taxpayer.
The corporate tax return in the UAE is completed electronically via the EmaraTax portal. While uploading financial statement files is not always mandatory, the company must always have a complete package of (audited) financial statements finalized to support all data declared in the return.
Net accounting profit reflected in the financial statements under IFRS serves as the underlying basis for the tax calculation.
The accounting profit is adjusted as follows:
The final amount obtained after all tax computations and adjustments is subject to corporate income tax.
The absence of commercial operations does not exempt a company from its accounting and reporting obligations.
An official “dormant” status does not exist within the UAE legal framework.
As long as a company holds an active trade license, it is recognized as an active legal entity and is required to:
The company’s balance sheet must still reflect its share capital (if paid up), incorporation and annual license renewal expenses, as well as bank maintenance fees (if an account was opened).
The requirement to verify a dormant balance sheet through a licensed independent auditor depends entirely on the jurisdiction where the company is registered.
An audit is required if the dormant company is registered on the Mainland or within a strict Free Zone (such as DMCC). The registrar will not renew the trade license for the following year until an auditor’s report is uploaded into the system, even if it reflects only basic administrative expenses.
An audit is not required if the company is registered as an offshore entity (RAK ICC, JAFZA Offshore) or within specific Free Zones (such as Shams, IFZA, RAKEZ) that do not mandate audits for license renewals, provided the company’s annual turnover remains below the statutory threshold of AED 50,000,000.
The obligation to register with the Federal Tax Authority (FTA) and secure a Tax Registration Number (TRN) depends directly on the volume of taxable supplies and imports over the previous 12 months (or the forecast for the next 30 days).
| Mandatory Registration | turnover exceeding AED 375,000
The application must be submitted to the FTA within 30 days of crossing this threshold. |
| Voluntary Registration | Turnover or taxable expenses exceeding AED 187,500. |
If a foreign (non-resident) company makes taxable supplies of goods or services within the UAE to individuals or corporate entities that do not account for this tax themselves, the threshold is zero, and registration is required from the very first transaction.
Companies registered as VAT taxpayers are required to file quarterly VAT returns with the Federal Tax Authority (FTA). Enterprises with an annual turnover exceeding AED 150,000,000 must file returns on a monthly basis.
The statutory deadline for filing the return and paying the tax is the 28th day following the end of each tax period.
Submitting a quarterly VAT return is mandatory even if the company had no commercial operations during the reporting period (nil return).
All filings are processed through the FTA’s EmaraTax portal. Late submissions trigger administrative fines starting at AED 1,000 per return for the first violation. For repeated infractions within a rolling 24-month period, the penalty escalates to AED 2,000 per missed return.
Late tax payments incur a penalty of 2% of the unpaid tax amount on the very first day of delay, followed by 4% per month (starting from the 7th day after the deadline) until the debt is fully liquidated.
UAE companies operate under a state-issued trade license, which is valid for one year and requires annual renewal by the respective Free Zone Authority or the Department of Economic Development. Failing to renew the trade license on time results in the freezing of the corporate bank account and the accumulation of administrative fines.
In addition to license renewals, companies are required to
Violation
Fines and Penalties
Late registration for corporate tax
AED 10 000
Late submission of the corporate tax return
AED 500 per month for the first 12 months of delay;
AED 1,000 per month starting from the 13th month.
Late payment of corporate tax
14% per annum for each month or part of a month of delay.
Submission of incorrect data in a tax return
AED 500
Failure to cooperate with a tax officer during a tax audit
AED 20 000
Deliberate tax evasion, underreporting of income, or misrepresentation of tax thresholds
Imprisonment and/or a fine of up to 3 times the amount of the unpaid tax.
Deliberate submission of false information or documents to the Tax Authority
Deliberate submission of false information or documents to the Tax Authority
Deliberate concealment or destruction of documents or data required to be stored and submitted to the Tax Authority
Imprisonment and/or a fine of up to 3 times the amount of the unpaid tax.
Obstructing Tax Authority employees in the performance of their official duties
Imprisonment and/or a fine of up to AED 1,000,000.
No, classic UAE offshore companies (registered within registries such as RAK ICC or JAFZA) are completely exempt from the obligation to submit financial statements to the Registrar or undergo an annual audit. However, they are legally required to maintain internal bookkeeping records and retain primary financial documentation for at least 7 years to comply with potential official regulatory requests.
Yes, companies in the UAE have the legal right to choose any foreign currency as their functional currency for bookkeeping and preparing independent auditor’s reports. The only operational restriction applies to the EmaraTax portal: when completing the annual corporate tax return, all final figures must be converted and declared strictly in UAE Dirhams (AED) using the official Central Bank of the UAE exchange rate as of the reporting date.
Qualifying Free Zone Person (QFZP) status allows an eligible Free Zone company to legally apply a 0% tax rate on profits generated from qualifying international and inter-zone trade. To secure and maintain this status, the company must fulfill statutory criteria: maintain adequate economic substance within the UAE, refrain from generating income from excluded activities, comply with transfer pricing rules, and undergo a mandatory annual audit.
If a company has had absolutely zero commercial transactions throughout the entire financial year, submitting a nil corporate tax return is entirely lawful. The critical requirement is to file the return on time, within 9 months following the end of the reporting period.
While the return will be processed as correct, corporate owners should note that a balance sheet can rarely be perfectly empty, as it must still reflect unavoidable baseline expenses such as annual license renewals and bank maintenance fees.
No. While day-to-day bookkeeping and accounting can be outsourced to any in-house specialist or corporate services firm, conducting an independent audit and issuing an official Audit Report is restricted. Only independent, licensed auditors registered with the UAE Ministry of Economy and explicitly accredited by the Registrar of the specific jurisdiction (for Free Zone enterprises) have the legal authority to sign an auditor’s report.
International Financial Reporting Standards (IFRS) serve as the mandatory baseline framework for accounting and financial reporting across the UAE. For small and medium-sized enterprises that meet the statutory thresholds, a simplified framework known as IFRS for SMEs is permitted to ease disclosure burdens.
An audited financial report is not required during the annual trade license renewal process in several popular jurisdictions, including IFZA (International Free Zone Authority), Meydan Free Zone, Shams (Sharjah Media City), SPC Free Zone (Sharjah Publishing City), KEZAD (Khalifa Economic Zones Abu Dhabi), and Ajman Free Zone (AFZ). The authorities of these zones do not require an auditor’s report to be uploaded to their internal registry to extend a commercial license.
However, businesses must remain compliant with overarching federal mandates that apply regardless of individual Free Zone rules: