Accounting & Bookkeeping
Maintenance of accounting records and systematic archiving of documents
Price
200 USD/hour

Accounting & Bookkeeping
Mandatory. Must be maintained by an accountant registered with the TFAC.
Records must be retained for 5 to 7 years.
Financial Statements Preparation
Annually
Accounting Standards
Thai Financial Reporting Standards (TFRS), based on IFRS
Consolidated Financial Statements
Mandatory if there are subsidiary companies, and the company is recognized as a holding
Dormant Reporting Option
Permitted, but does not exempt from annual audits and filings
Filing Financial Statements with the Registry
Yes
Filing Financial Statements with the Tax Authority
Yes, submitted as part of the Corporate Income Tax Return.
Statutory Audit
Mandatory for all companies. Conducted by a certified Thai public accountant (CPA).
Tax Returns
Annual return (PND 50), half-year return (PND 51), and monthly returns for VAT, withholding tax, and payroll tax.
Investment Reporting (BOI)
Annual reporting is required for companies approved by the Board of Investment.
Annual Return / Corporate Reporting
Annual general meeting of shareholders must be held, and an updated list of shareholders must be submitted.
Limited liability companies must maintain continuous accounting records, including invoice registration, journals, payroll, tax computations, and primary document retention in Thailand for at least 5 years.
Tax authorities can extend this retention period up to 7 years.
Throughout the financial year, the company must fulfill regular monthly and half-year obligations:
Annual financial statements are prepared under Thai Financial Reporting Standards (TFRS) in the Thai language, and must be completed by an accountant registered with the Federation of Accounting Professions (TFAC).
Holding structures require consolidated statements.
A financial audit is mandatory for all Thai companies without exception, even for dormant entities with zero operational activity.
A licensed independent Thai Certified Public Accountant (CPA) must perform the audit.
The audited accounts must be uploaded to the DBD e-Filing system within 1 month from the date of approval at the general meeting of shareholders.
Based on the audited financial statements, the annual corporate income tax return is completed.
The annual return, along with the independent auditor’s report and the financial statements, must be submitted to the Revenue Department via the e-Revenue portal within 150 days from the financial year-end date.
The company must hold its Annual General Meeting of Shareholders (AGM) within 4 months from the financial year-end.
Following the meeting, an updated list of shareholders (Form BOJ.5) must be submitted to the DBD within 14 days.
Only specialists with verified qualifications who hold active membership with the Federation of Accounting Professions (TFAC) are legally permitted to maintain a company’s books in Thailand. Educational requirements depend on the size of the business:
| Small and Medium-Sized Enterprises (SMEs) (Registered capital ≤ 5 million THB, total assets ≤ 30 million THB, and annual turnover ≤ 30 million THB) | The accountant must hold at least a Higher Vocational Certificate (HVC) in accounting. |
| Large Businesses and Holdings (exceeding any of the SME criteria). | The accountant must hold a Bachelor’s Degree in Accounting or higher. |
Appointing an individual who lacks a TFAC license or the required degree constitutes a regulatory offense, subjecting both the company and its directors to a statutory fine of up to 10,000 THB.
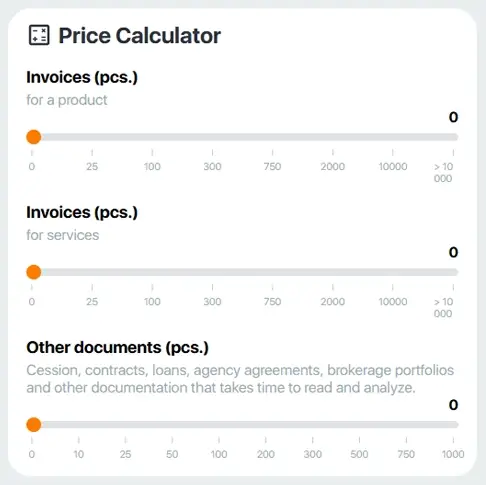
The interactive calculator provides an estimated cost for accounting, bookkeeping, and statutory audit services.
Total fees depend on annual gross turnover, transaction volume, invoice frequency, the format of primary documentation submissions, and the overall scope of required advisory services.
Statutory audits are performed by licensed local auditors registered with TFAC.
All accounting ledgers, journals, balance sheets, invoices, and payment receipts must be stored at the company’s registered office address in Thailand. The standard statutory retention period is at least 5 years from the financial year-end closing date. However, the Revenue Department may extend this period up to 7 years during in-depth tax audits or if the company carries forward tax losses from previous years.
Books must be kept exclusively in the national currency, Thai Baht (THB). All entries in the general ledger and journals must be written in the Thai language, and incoming foreign invoices must include a translation of key transaction details.
Bookkeeping must comply with Thai Financial Reporting Standards (TFRS), which are categorized into two frameworks:
Foreign-owned entities are also permitted to adopt full international financial reporting standards (IFRS) if required.
A standard set of financial statements in Thailand includes the following components:
Large holding groups that follow the Full TFRS framework must also include a Statement of Cash Flows.
The initial reporting period begins on the exact date of corporate incorporation and must conclude within the following 12 months.
Most businesses use the standard calendar year from January 1 to December 31 as their financial year.
A company may select an alternative closing date (such as March 31 or June 30), but changing an established reporting period requires prior formal approval from both the Revenue Department and the DBD.
Financial statements must be prepared in the national currency, Thai Baht (THB), and written in the Thai language.
Companies holding subsidiaries with a ownership stake exceeding 50% are required to prepare consolidated financial statements for the corporate group.
The finalized auditor’s report serves as the mandatory foundation for tax return submissions to the Revenue Department.
For public companies listed on the Stock Exchange of Thailand (SET), financial statements are subject to mandatory quarterly reviews by licensed auditors.
| Department of Business Development (DBD) | The Revenue Department |
| Audited financial statements must be formally approved at the Annual General Meeting of Shareholders (AGM) within 4 months from the financial year-end date (by April 30 for a standard calendar year).
Directors must upload the approved financial reporting package and the auditor’s report to the DBD e-Filing system within 1 month from the AGM date (by May 31 for a standard calendar year). |
A copy of the audited financial statements and the independent auditor’s report must be attached to the Annual Corporate Income Tax Return (Form PND 50). This return must be submitted via the e-Revenue portal within 150 days from the financial year-end closing date (by May 31 for a standard calendar year). |
Thai entities must submit the following tax forms through the electronic e-Filing system by the 23rd day of each subsequent month:
Form PND 3 for payments made to resident individuals, and
Form PND 53 for payments made to resident corporate entities.
Thai regulatory authorities (the Department of Business Development and the Revenue Department) implement a mirror penalty framework.
For any compliance violation, administrative fines and statutory sanctions are levied simultaneously on both the corporate entity and personally on each authorized director with signing capacity.
Intentional data concealment or systematic non-compliance triggers direct criminal prosecution.
Yes, a statutory audit is mandatory for all registered corporate entities in Thailand. Financial statements must be examined and certified by an independent Certified Public Accountant (CPA). Public companies are subject to additional requirements, including mandatory audits and quarterly reviews of their financial reporting.
The standard financial year in Thailand runs from January 1 to December 31. However, a company may apply for an alternative accounting period, subject to approval from the Department of Business Development (DBD).
Yes, full compliance is mandatory. Thai legislation does not grant compliance exemptions for inactive companies. Even if a company has zero bank transactions and no commercial operations, it is still required to file monthly nil tax returns. Furthermore, at the end of the fiscal year, the company must engage a licensed Thai auditor (CPA) to prepare a nil balance sheet and submit it alongside the audit report to both the Department of Business Development (DBD) and the Revenue Department.
No, this is legally prohibited. Pursuant to the Accounting Act B.E. 2543, the individual responsible for bookkeeping must be an accountant officially registered with the Department of Business Development (DBD) and a member of the Federation of Accounting Professions (TFAC). It is impossible to qualify as an official accountant without holding Thai citizenship and passing the local professional accreditation.
If a company misses the filing deadline (which is 1 month from the date of the Annual General Meeting of shareholders), the Department of Business Development (DBD) automatically issues fixed penalties to both the corporate entity and each director personally. If the fines remain unpaid and the statements are not filed within a few months, the DBD will officially refer the case to the Economic Crime Division of the Royal Thai Police. Consequently, the director will be issued a formal police summons to appear at the police station for questioning.