1.
Private Company Limited by Shares
The most popular legal form for SMEs. Shareholders (up to 50) have limited liability restricted to their share capital contribution. Shares cannot be freely transferred or offered to the public.

Access to tier-one banks, global investment networks, and major international markets, enabling seamless business expansion on a global scale.
The entire process can be completed remotely. Your company will be fully incorporated within 1 to 5 business days without requiring your physical presence in Hong Kong.
Hong Kong operates on a territorial system of taxation, meaning companies are only taxed on profits derived directly from within Hong Kong.
Hong Kong is a fully cooperative jurisdiction and is not blacklisted by major international bodies, including the EU, FATF, and OECD.
Information regarding ultimate beneficial owners (UBOs) is not accessible in the public state registry. Full residential addresses and passport details of directors are kept in a secured, non-public section of the Registry and can only be disclosed under specific legal authorization.
There is no mandatory minimum authorized or paid-up share capital required to incorporate.
Unlike classic zero-tax offshore jurisdictions, Hong Kong levies a corporate profit tax if the business income is generated locally within the territory.
Opening corporate bank accounts with traditional Hong Kong banks involves strict compliance procedures and can be challenging for non-residents.
A business owned by two or more co-owners who share personal liability for the firm’s obligations. Regulated under the Partnership Ordinance (Cap. 38).
Consists of general partners (who manage the business and bear unlimited liability) and limited partners (investors whose liability is capped, but who cannot manage operations).
An extension of a foreign corporation, not a separate legal entity. The parent company retains full liability. Registered as a “Non-Hong Kong Company” under the Companies Ordinance.
A non-commercial entity restricted to marketing, market research, and customer support. It cannot generate revenue or execute contracts. Registered solely with the Inland Revenue Department (IRD).
A fiduciary arrangement where assets are managed by a trustee for the benefit of beneficiaries. Extensively used for private wealth and estate planning.
An individual conducting business under their own name, bearing full personal liability for all business obligations and debts.
Introduced in 2020 specifically for private equity and venture capital investment funds looking to structure under Hong Kong law.
A corporate fund structure with a variable share capital, designed specifically for collective investment schemes.
You can check the uniqueness of a name for free through the electronic search service of the Companies Registry. It is also recommended to check the name against the trademark database of the Intellectual Property Department.
Minimum 1 director
Individual or corporate
Resident or non-resident
! At least one director must be an individual
Director data is reported to the local agent and partially entered into the public registry
Mandatory for all companies
Individual or corporate entity that is a resident of Hong Kong
Professional service providers must hold a license (TCSP)
A sole director cannot also act as the secretary
One or more shareholders (up to 50)
Individuals and corporate entities, residents or non-residents of Hong Kong
A sole shareholder can be a director of the company
Shareholder data is reported to the local agent and entered into the public registry (address only)
Information about the beneficial owner is reported only to the Secretary. Only an authorized government authority can request such information from the Secretary.
In addition, beneficiary information may be requested by the bank when opening an account.
Significant controllers include individuals and legal entities that:
For individuals:
For legal entities:
The company is required to enter the information into the Register within 7 days after it is confirmed by the significant controller. The same timeframe applies for updating any changes to the data.
Failure to comply with the registry requirements may result in a fine of 25,000 HKD for the company and each responsible person. For ongoing non-compliance, a daily fine of 700 HKD applies. A significant controller who fails to provide information or provides false data may, upon conviction, face a fine of up to 300,000 HKD and imprisonment for up to two years.
The legal system of Hong Kong is entirely independent of the legal system of Mainland China. Unlike the civil law system in Mainland China, Hong Kong’s legal system is based on English Common Law.
At the top of the hierarchy of laws is the Basic Law of Hong Kong (the Constitution of Hong Kong), adopted in 1990. Hong Kong has its own administration, legislature, independent judiciary, and a court of final appeal.
The primary corporate legislation is the Companies Ordinance, Cap. 622.
To register a company, a specific set of documents must be prepared:
After verifying the documents, the company receives two key certificates:
⏱ Processing timeframes:
For future use outside of Hong Kong (e.g., for banking purposes or when working with foreign partners), the set of corporate documents is apostilled. The set typically includes the incorporation form NNC1 (to verify details of directors, secretary, and address), Certificate of Incorporation, Business Registration Certificate, Articles of Association, first resolutions of shareholders and directors, and corporate registers (optional).
If the company plans to engage in activities that require official authorization (banking, insurance, financial services, catering, tourism, etc.), the relevant licenses must be obtained.
To begin actual business operations, an account must be opened:
After the account is opened, the company can fully operate, execute contracts, and settle transactions with partners and clients.
The total cost of incorporation consists of registration fees, annual maintenance fees (payable one year in advance at the time of registration), legalized corporate documents package, and courier delivery to the destination.
for 1 year, Power of Attorney not included
Resolution to issue a Power of Attorney
Nominee Director’s Consent Letter
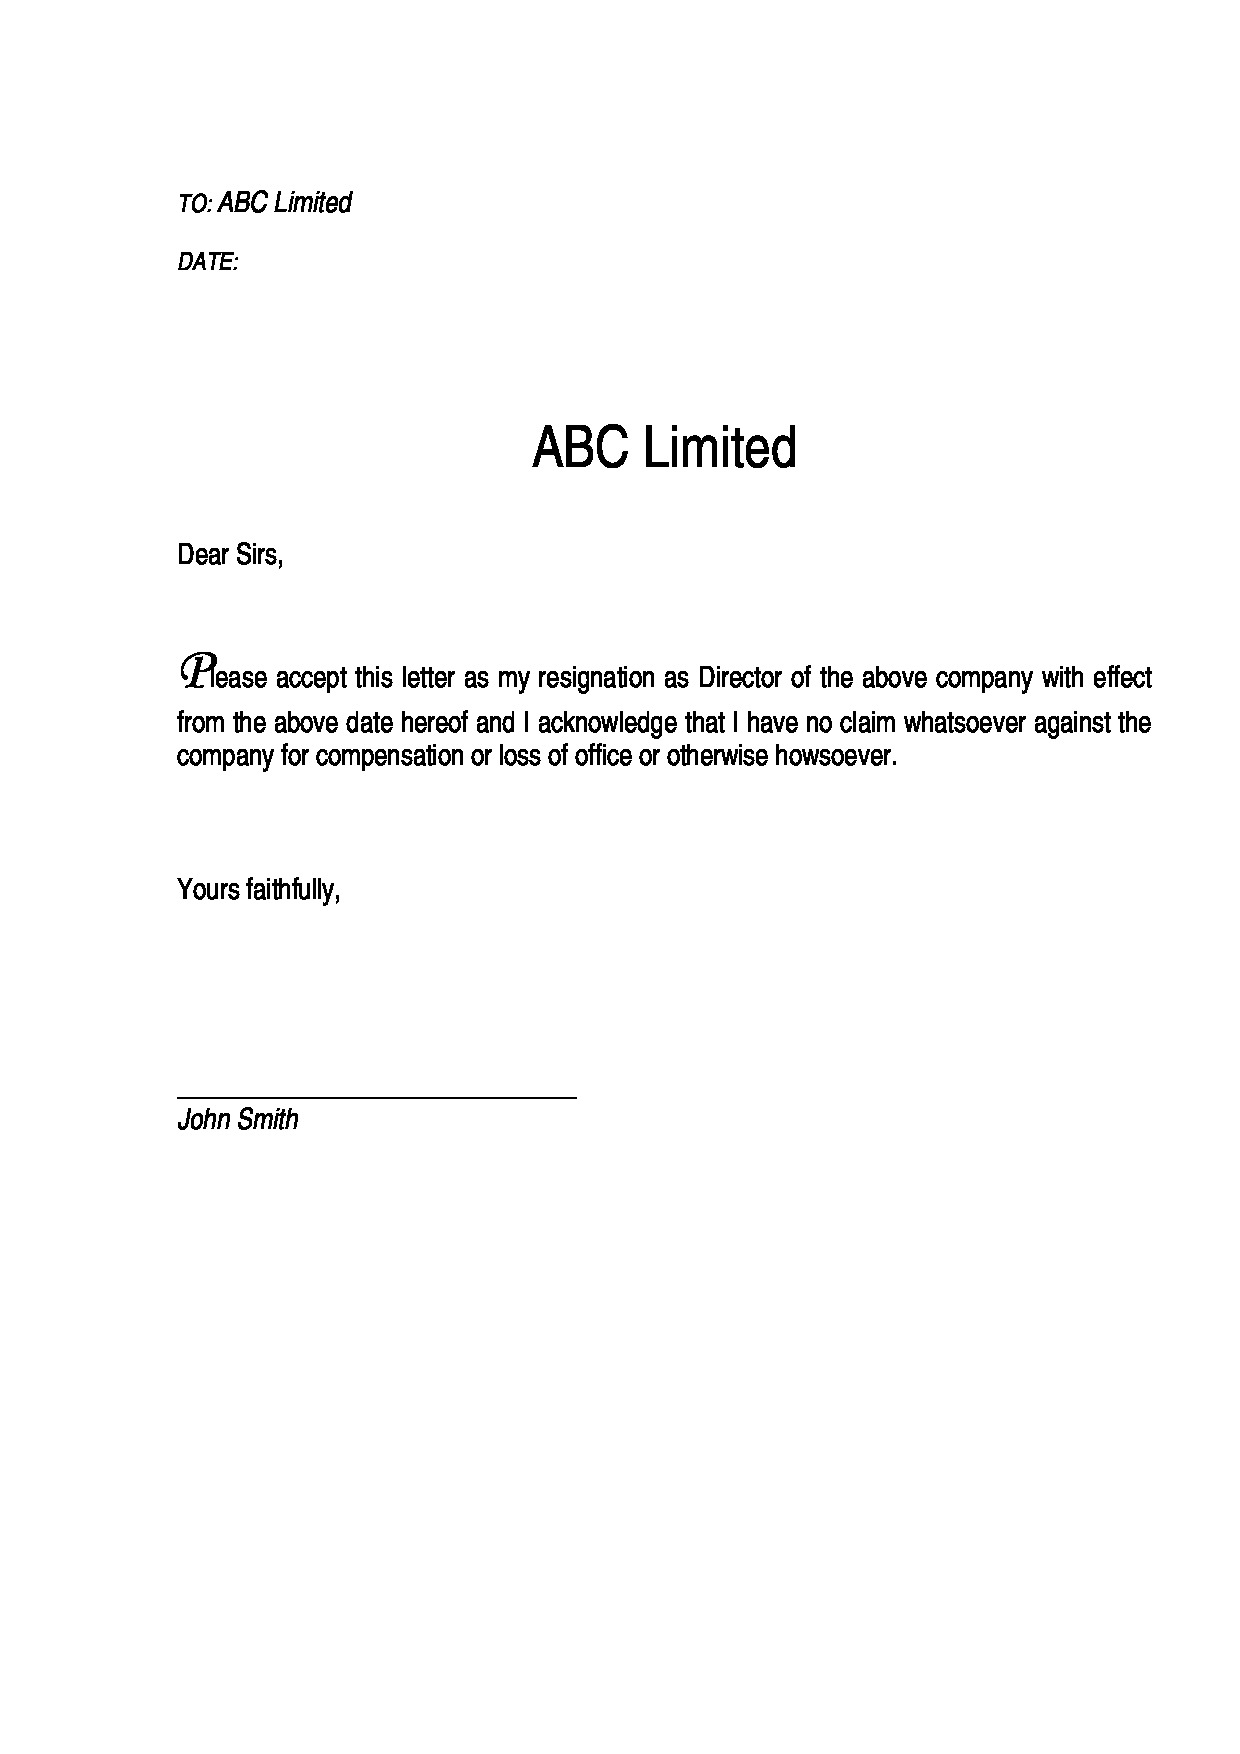
Director Resignation Letter (undated)
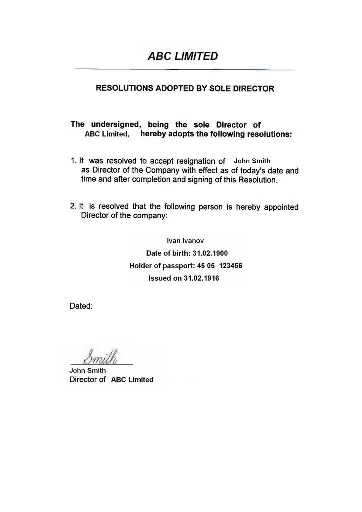
Resolution effecting the change of Director (undated)
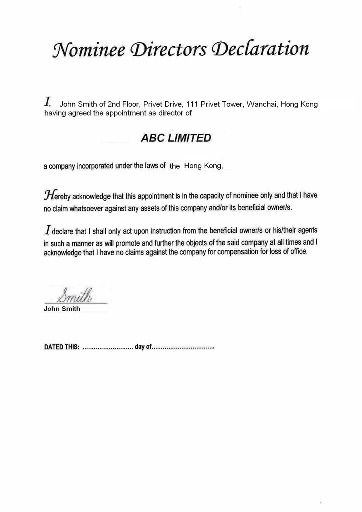
Nominee Director’s Declaration of nominee services
if the nominee shareholder and nominee director are represented by the same individual
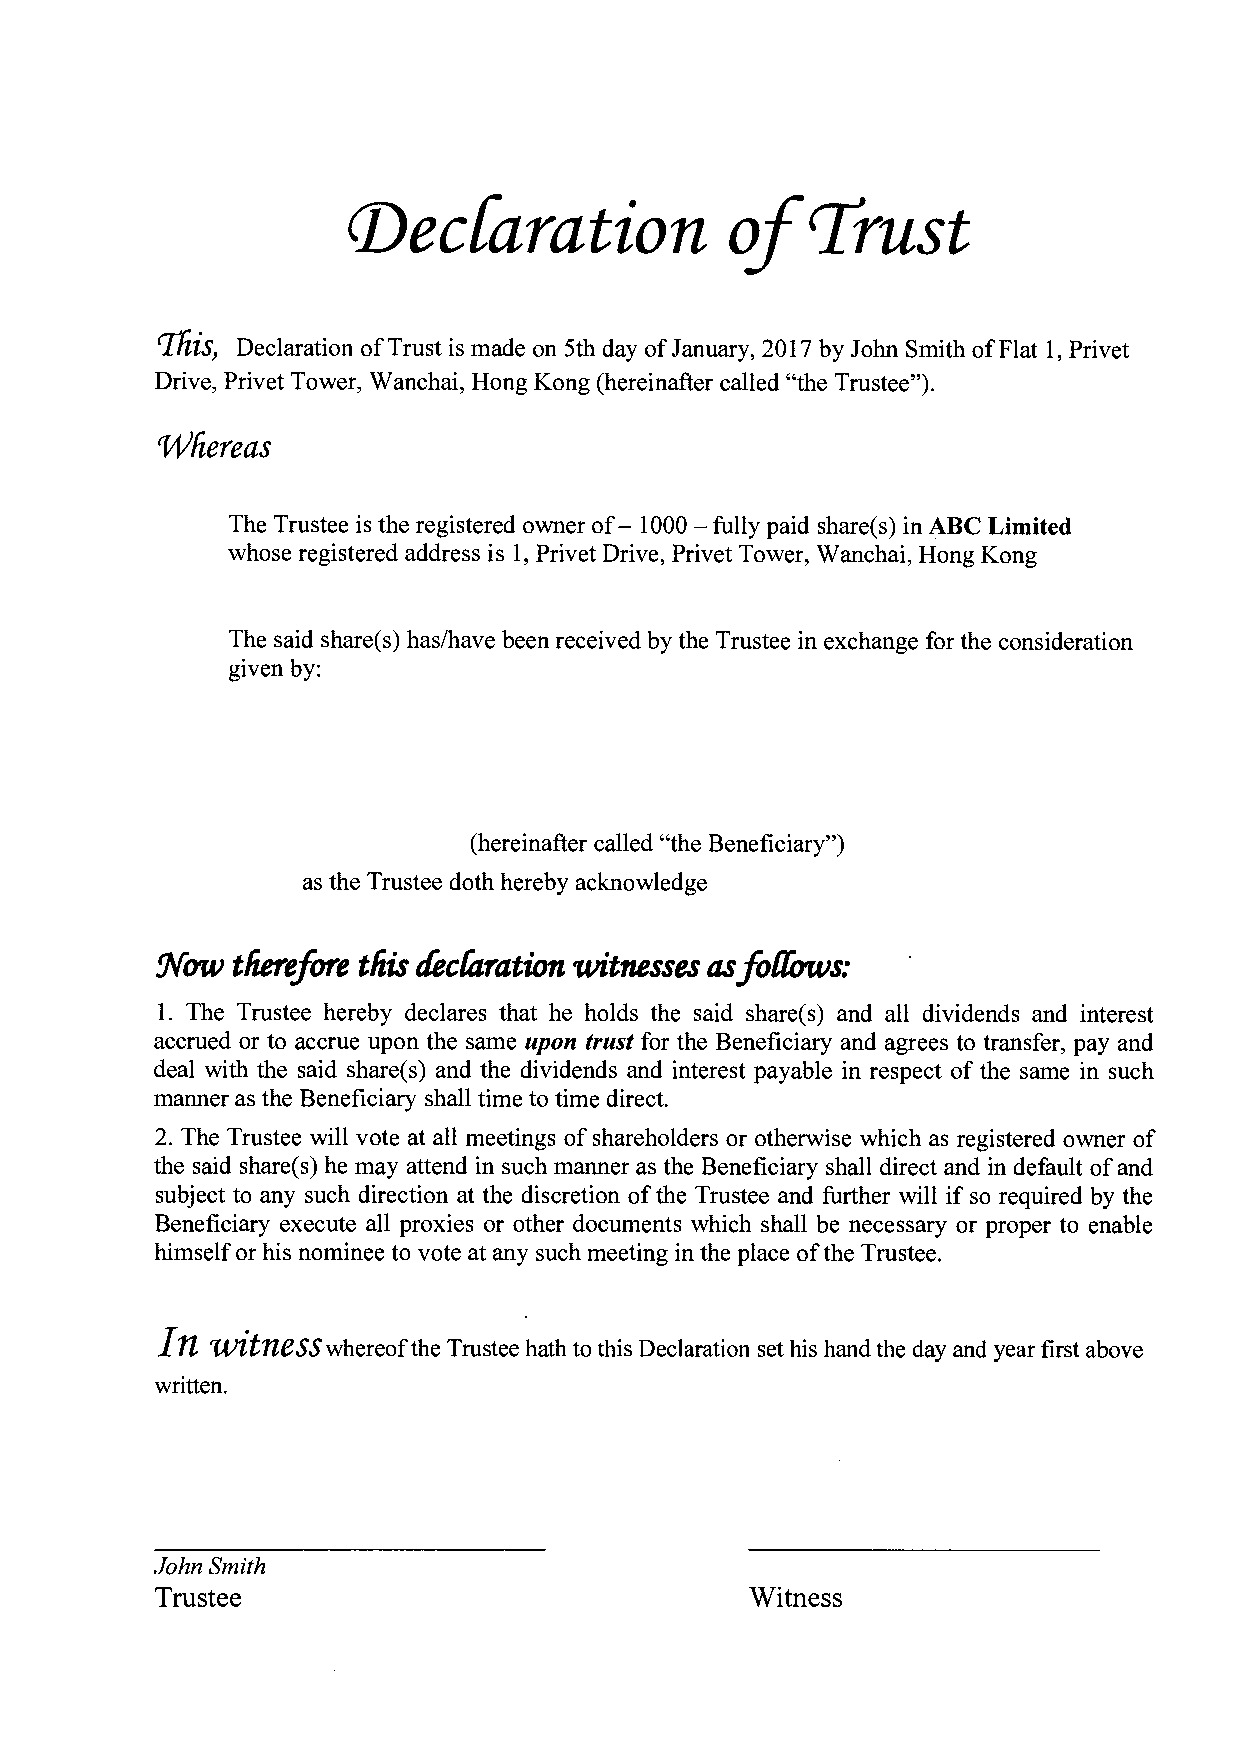
Deed of Trust
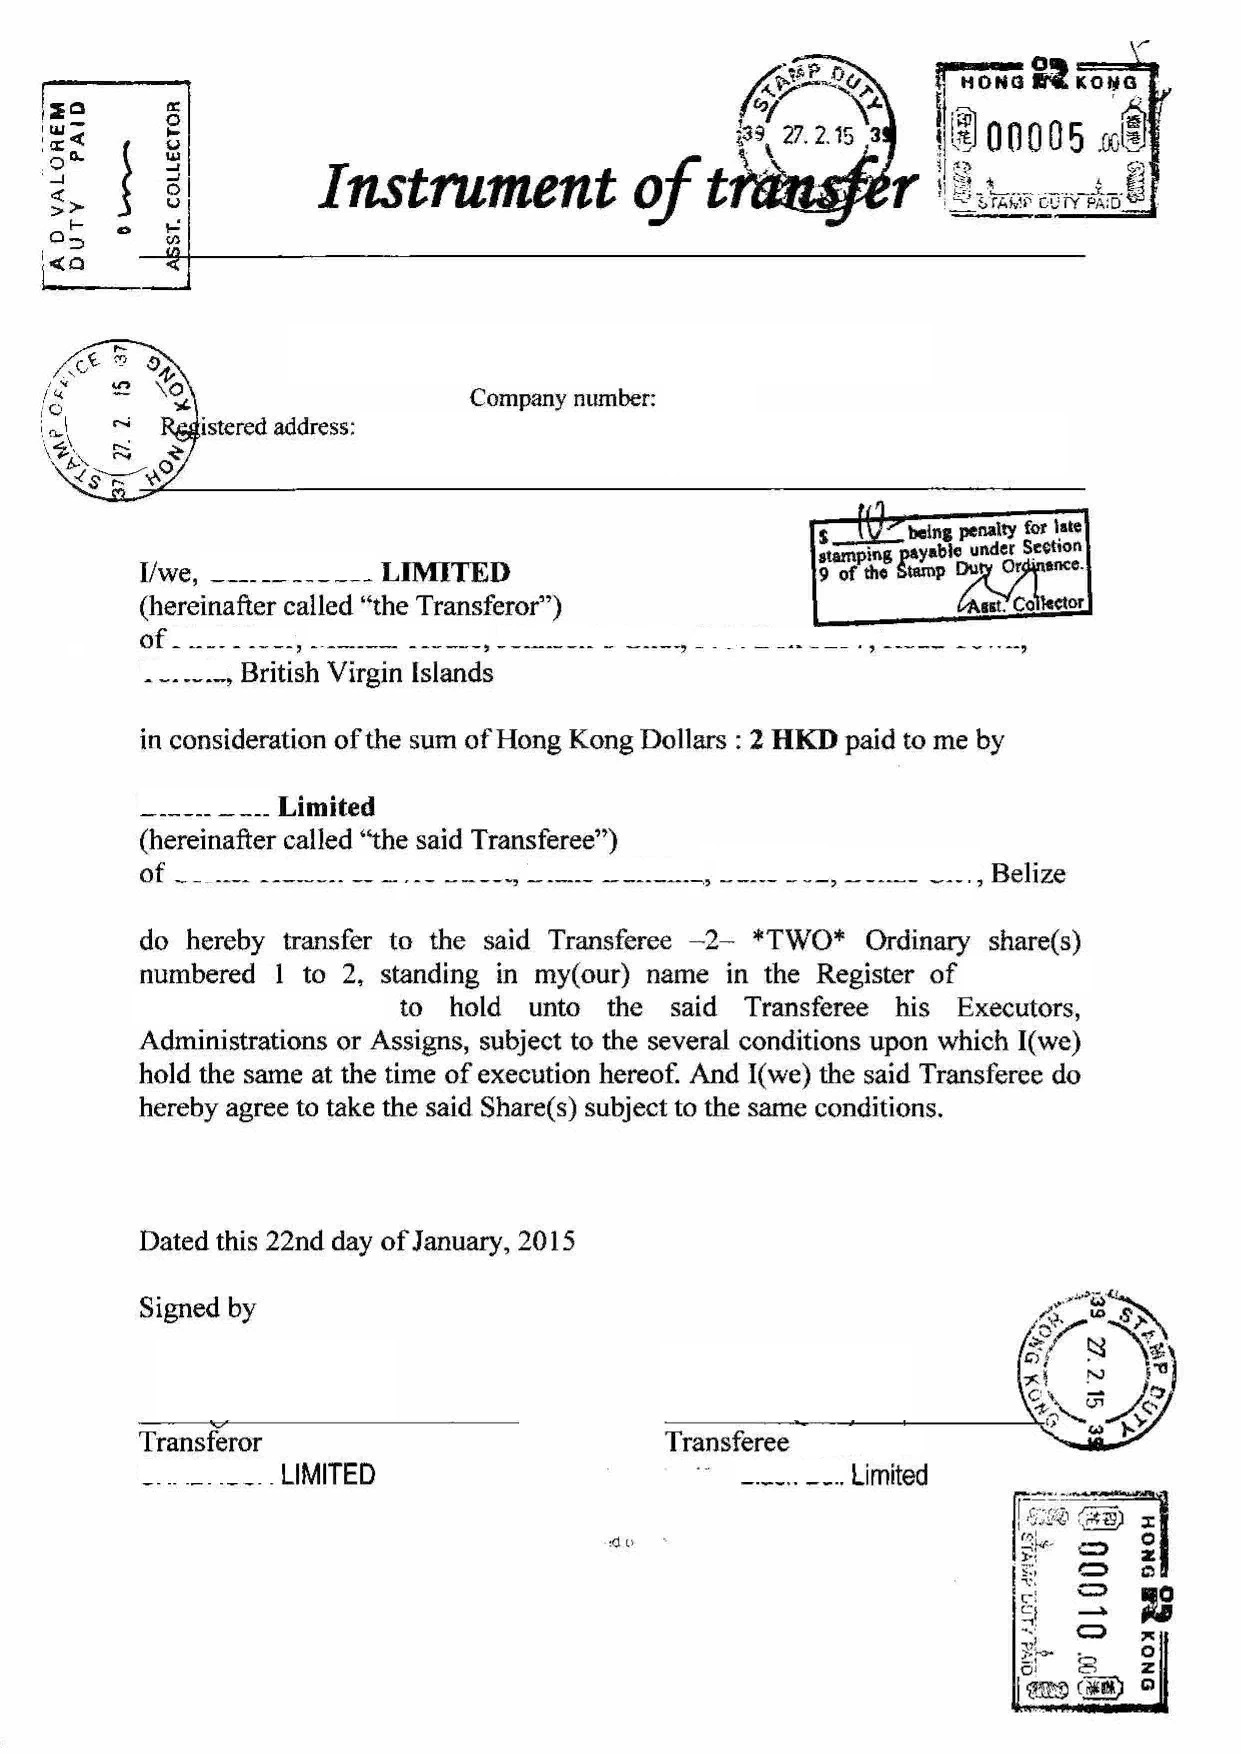
Instrument of Transfer (undated)
Payable in cases of: company registration, company renewal, company liquidation, transfer to a new agent, issuance of a Power of Attorney to a new attorney, change of director / shareholder / beneficial owner (except for changes to a nominee director / shareholder), signing of documents
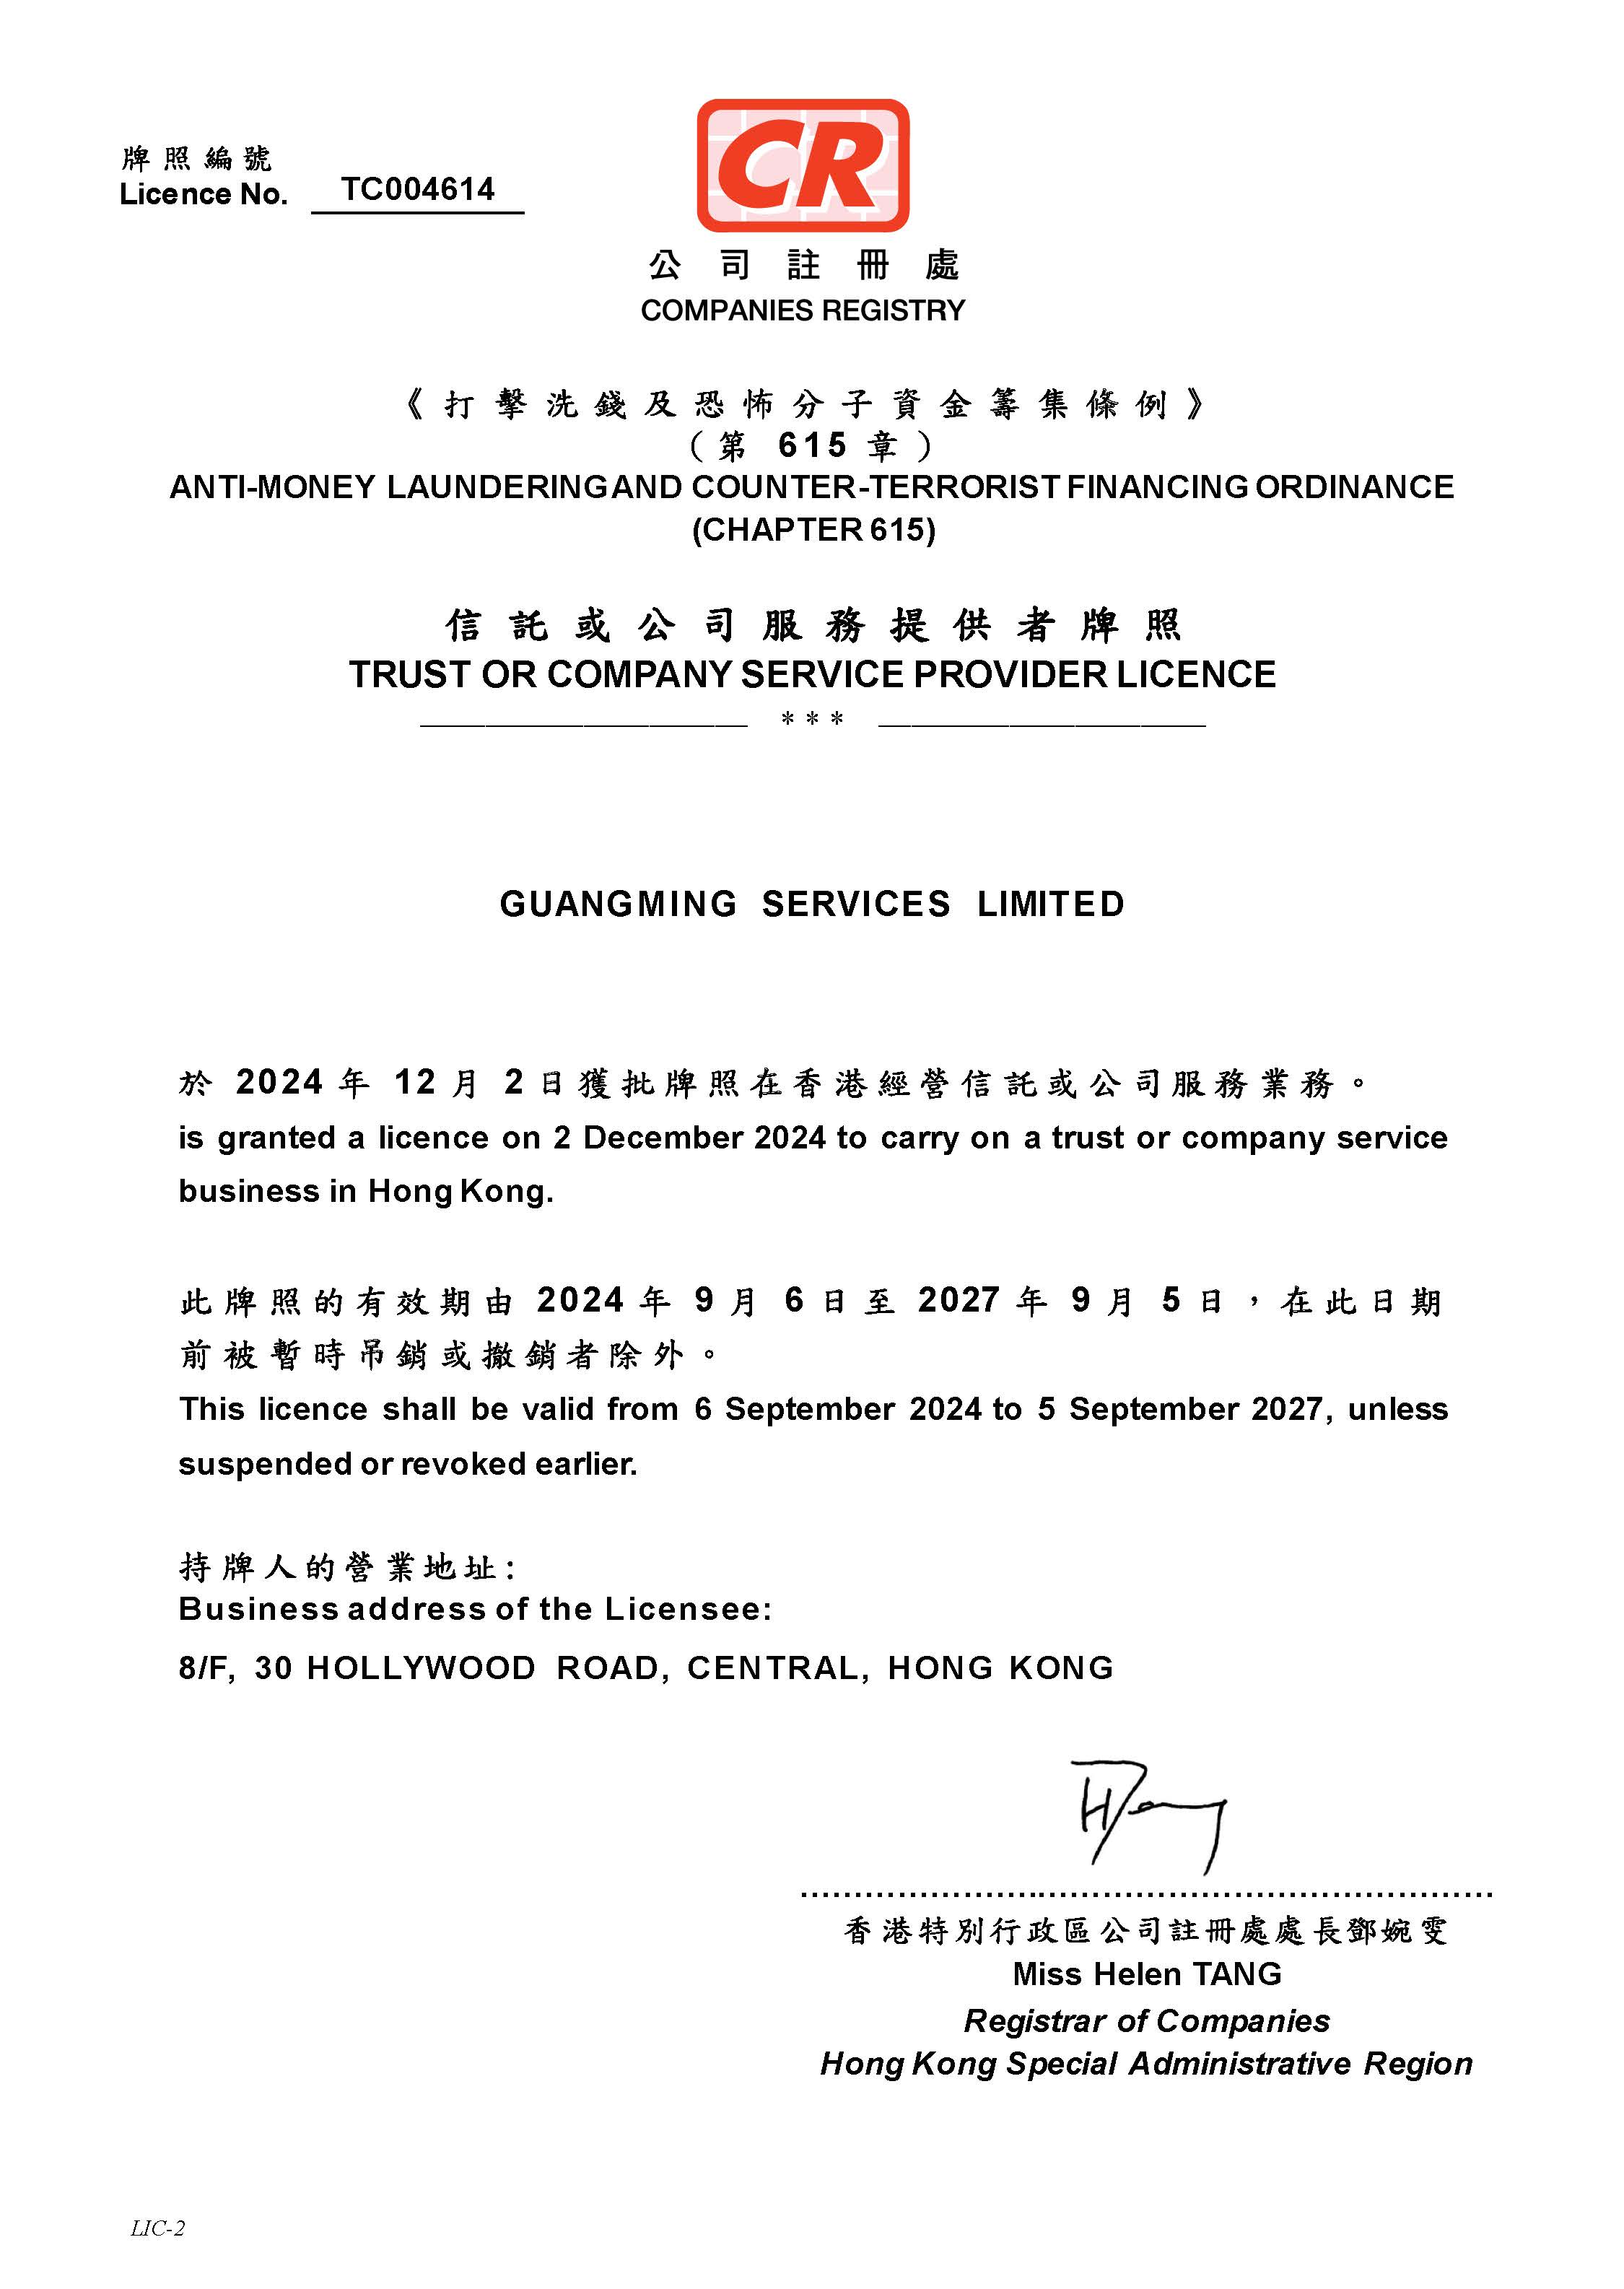
GSL is a licensed Trust or Company Service Provider (TCSP) in Hong Kong and operates in full compliance with AML/CTF statutory requirements.
The Secretary is an “Officer” of the company and is subject to penalties alongside the company itself.
Failure to perform secretarial duties may lead to administrative and/or criminal liability.
| Late filing of Annual Return (NAR1) | up to $50,000 + | up to $1,000/day |
| Absence of Significant Controllers Register (SCR) | up to $25,000 + | $700/day |
| Failure to notify changes to address/directors | up to $25,000 + | $700/day |
| Breach of document storage regulations | up to $25 000 + | $700/day |
| False statements in statutory documents | up to $300,000 and/or 2 years imprisonment |
Our duties as Secretary include notifying the client company of its obligation to comply with statutory requirements. Once such a notification has been issued, liability shifts from the Secretary directly to the company director and/or beneficial owner.
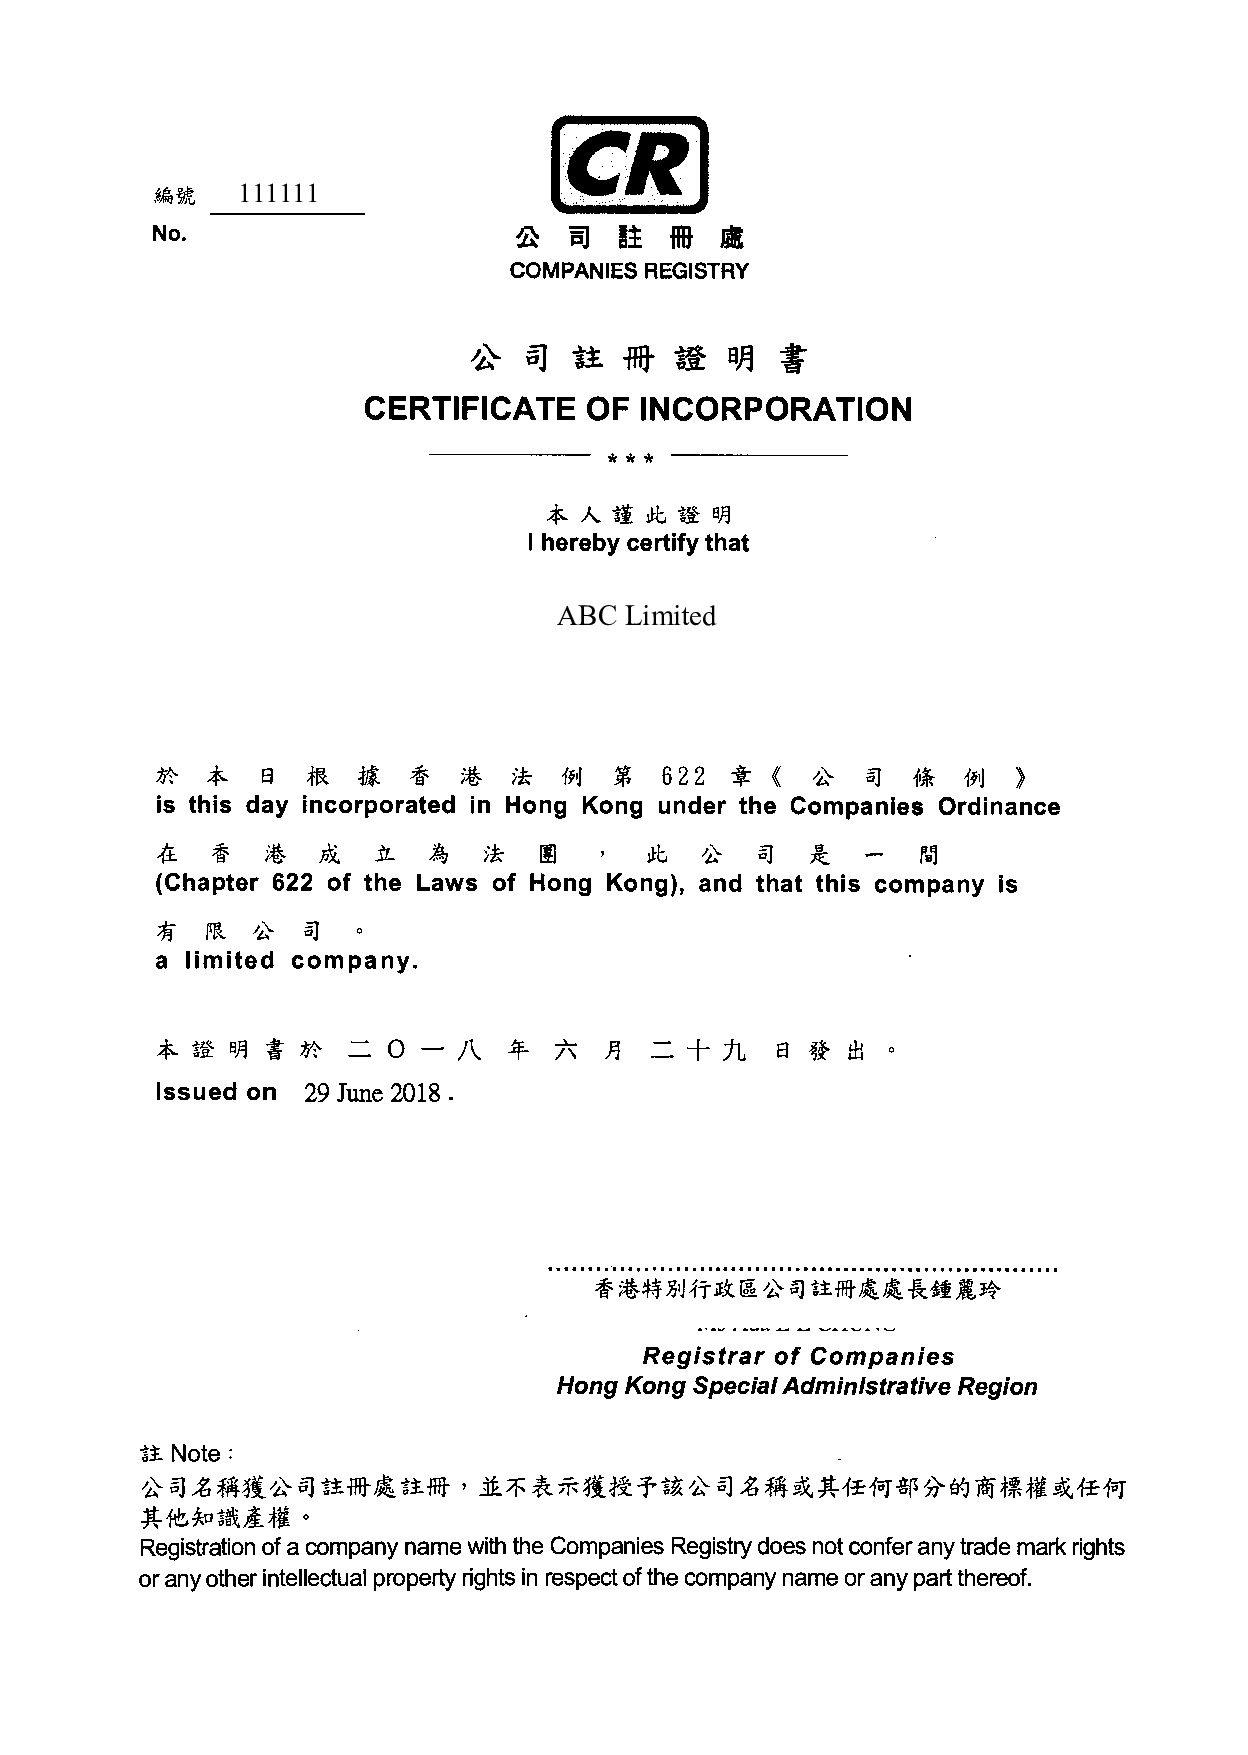
Confirms the registration of the company
Issued by the Companies Registry in accordance with the Companies Ordinance of Hong Kong, Cap. 622
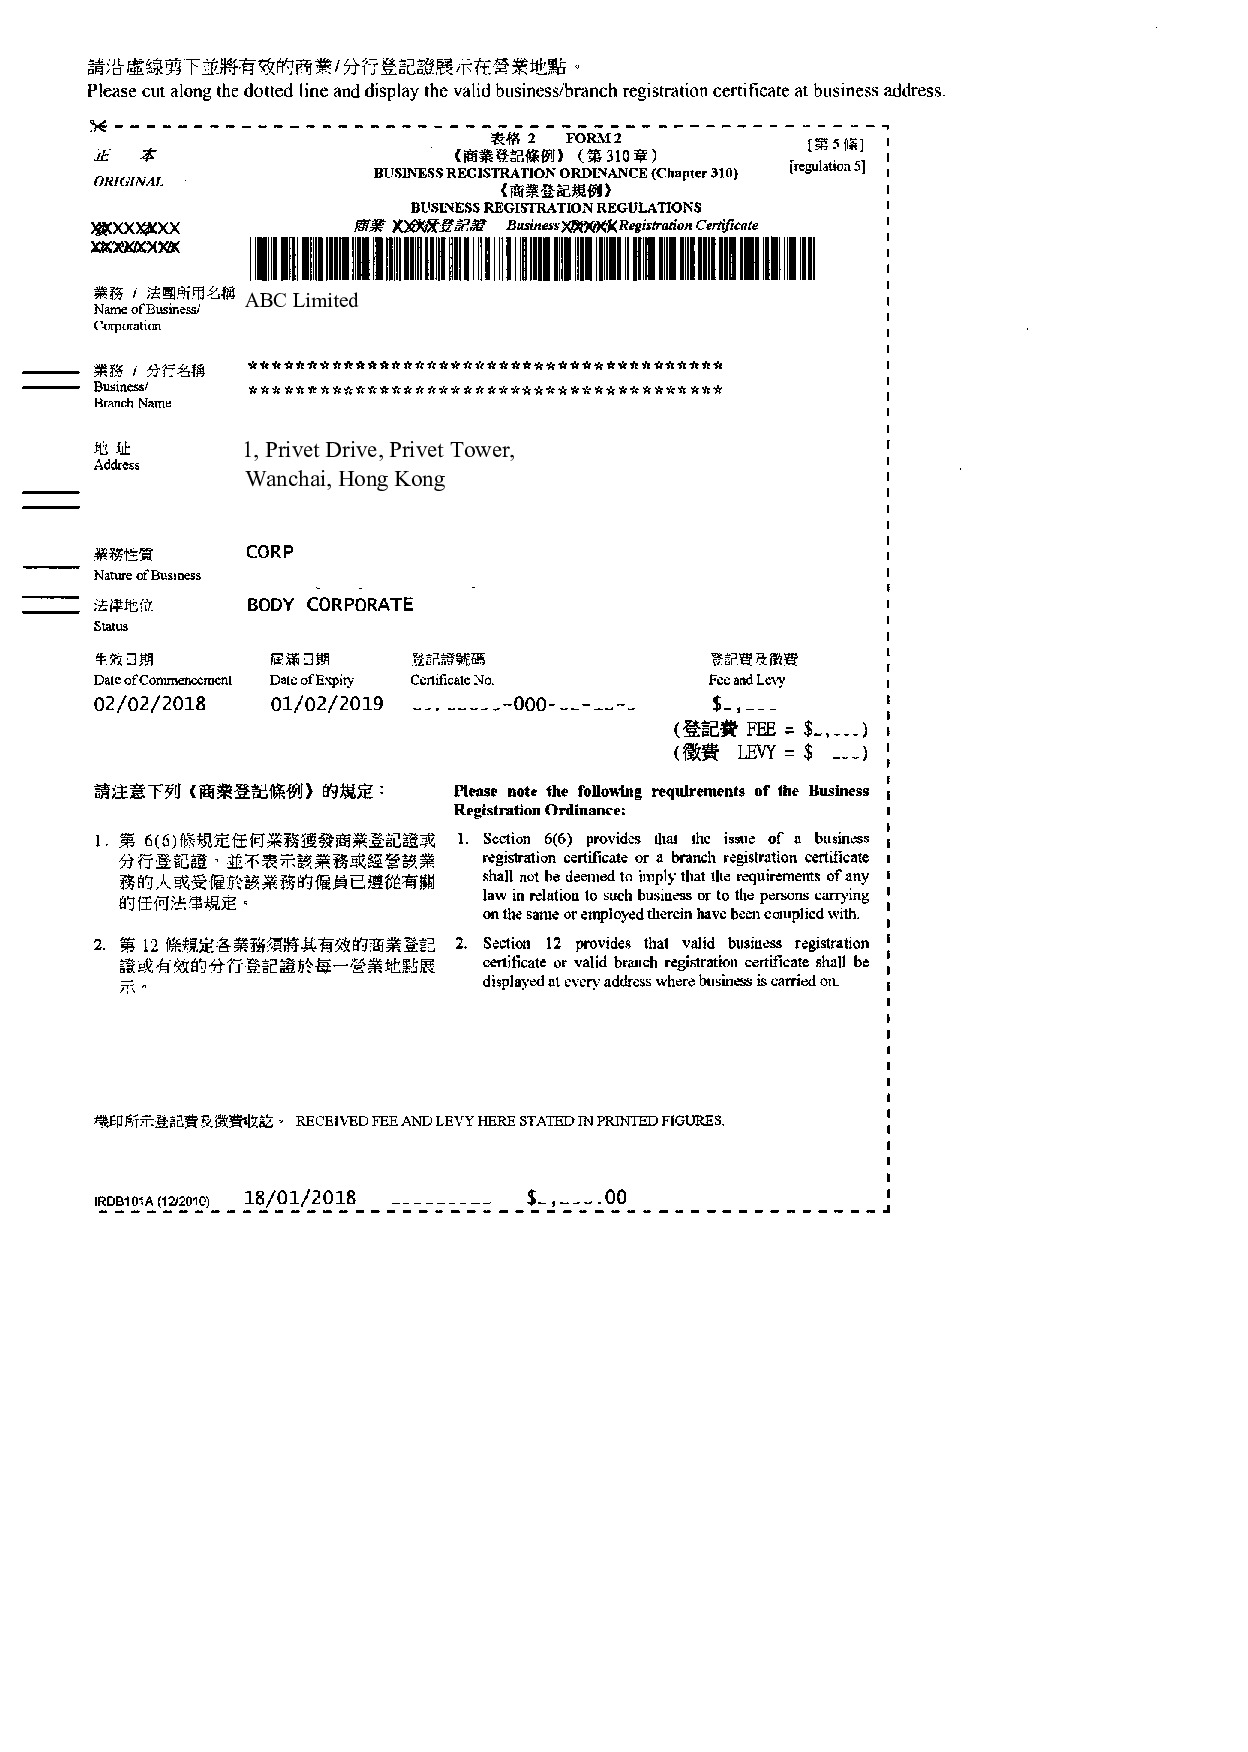
Confirms registration for conducting commercial activities
Issued by the Inland Revenue Department in accordance with the Business Registration Ordinance, Cap. 310
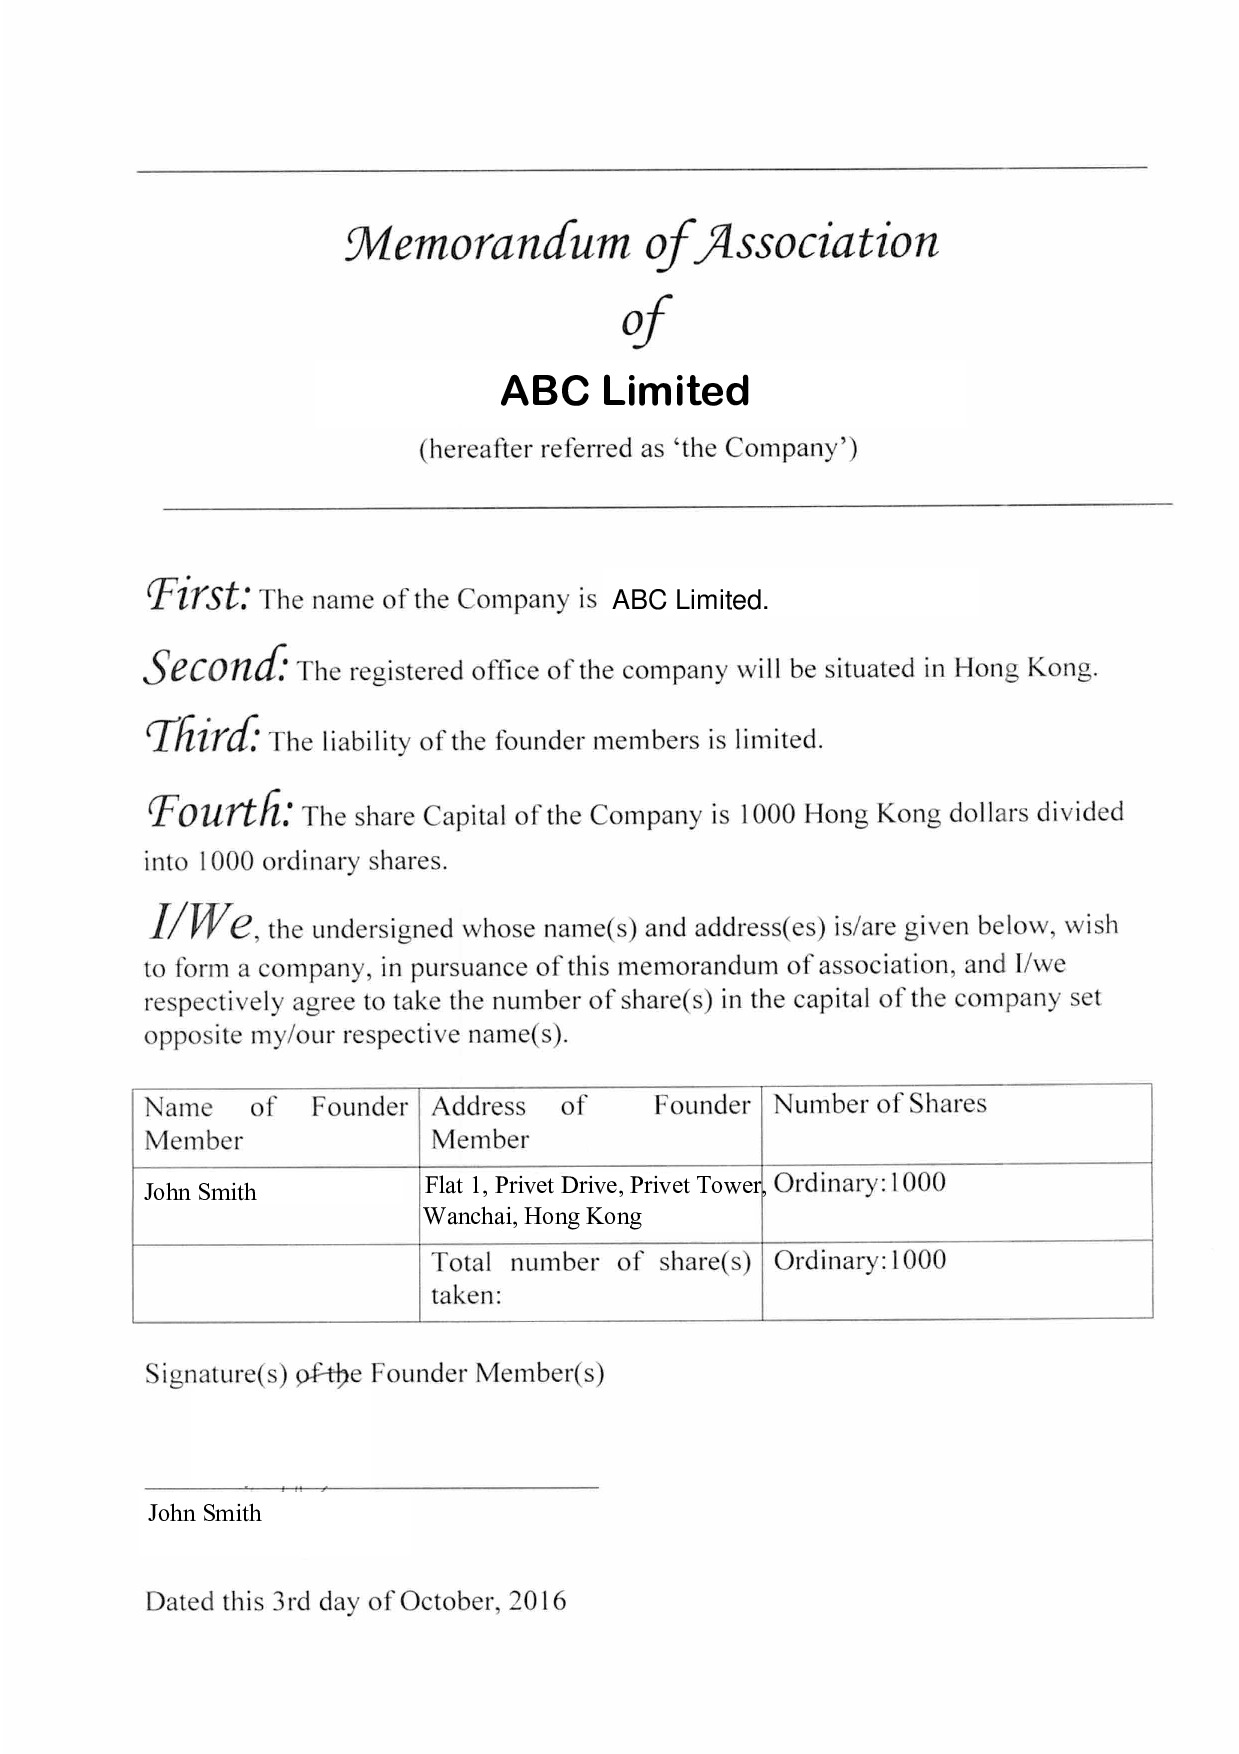
Defines the internal structure of the company, the rights and obligations of shareholders and directors, as well as the procedure for making corporate decisions
Approved by the company founders and submitted to the Hong Kong Companies Registry upon incorporation
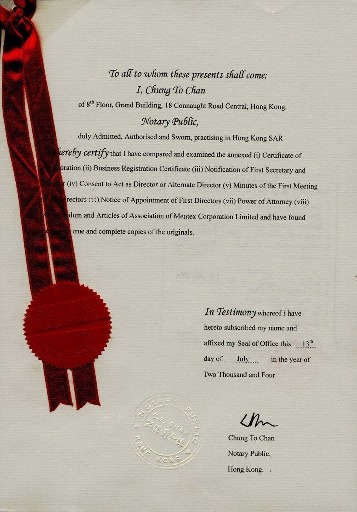
Confirms the authenticity of corporate documents for their use outside of Hong Kong
The copy is certified by a notary public, and the apostille is affixed by the High Court of Hong Kong
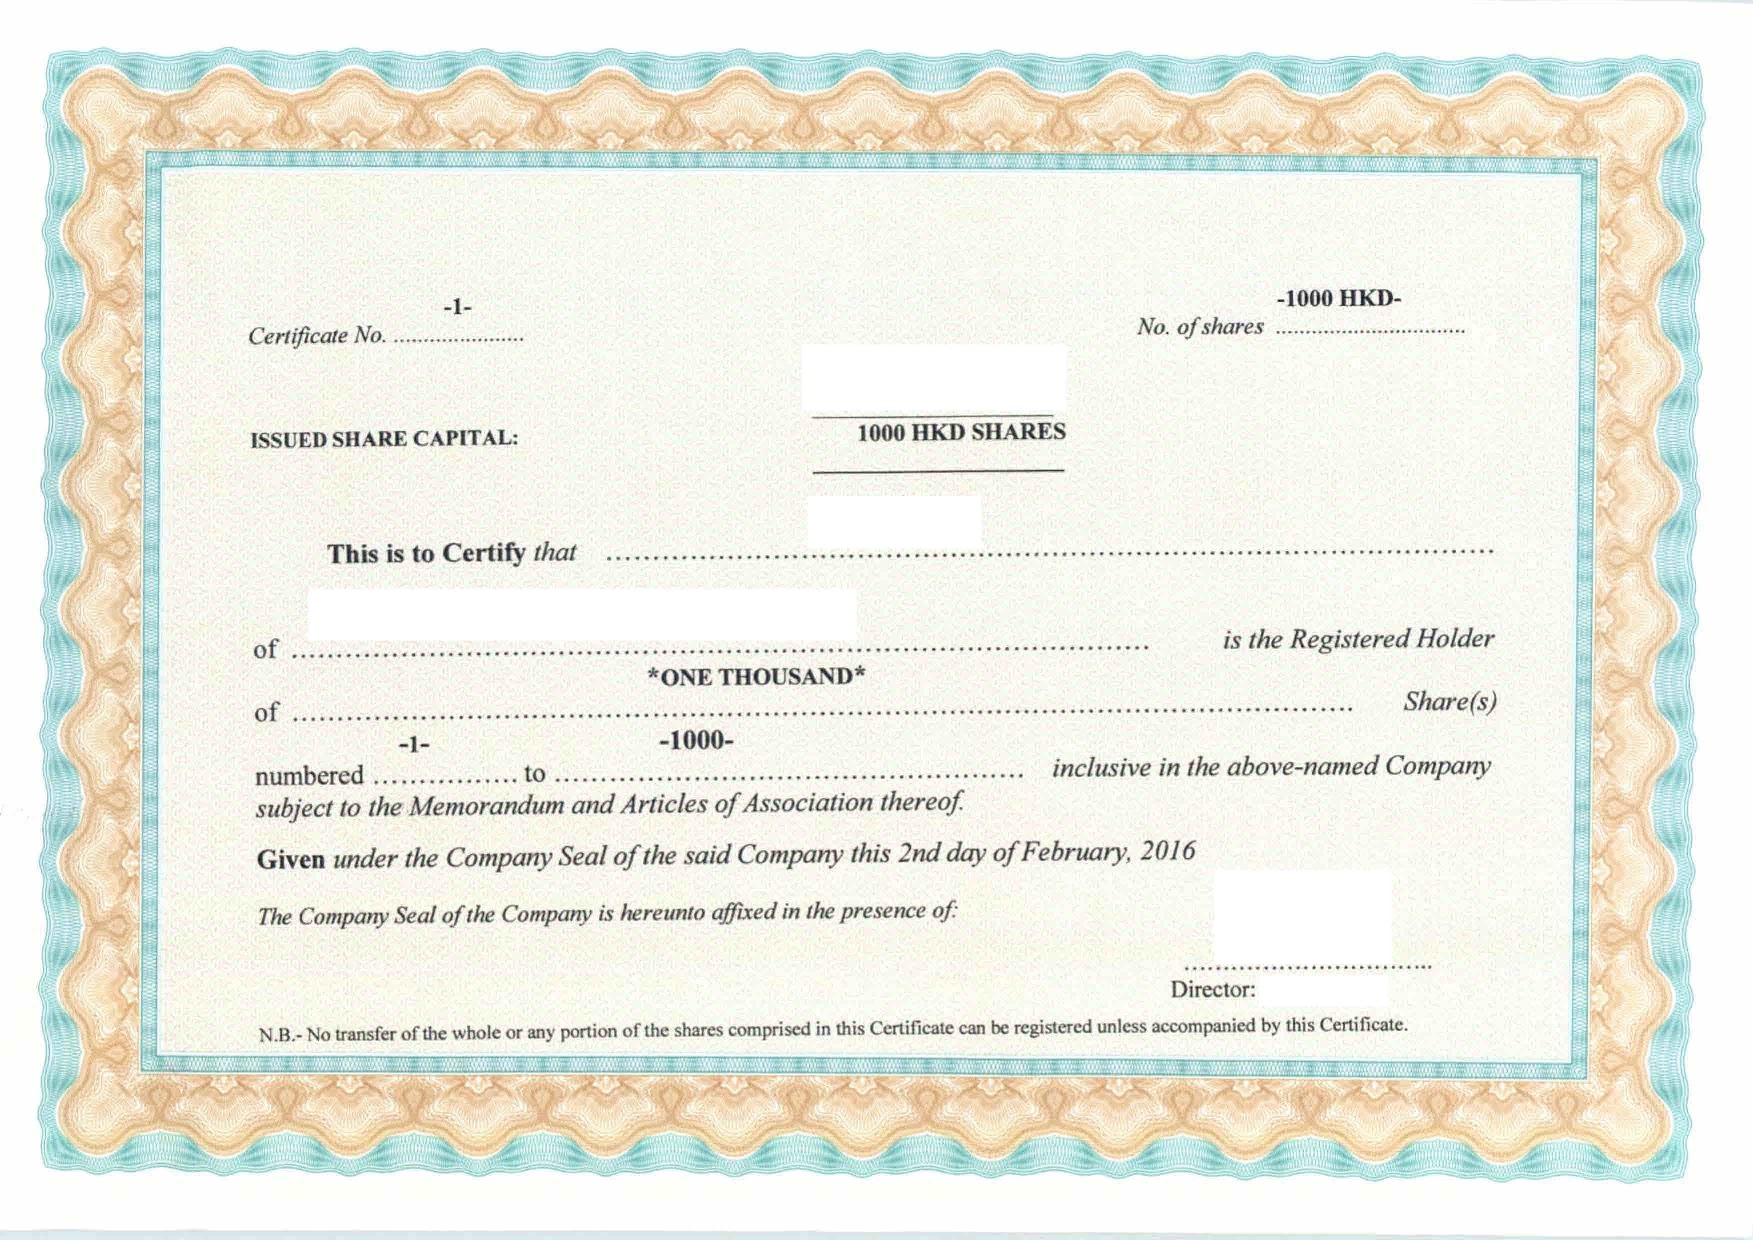
Confirm the shareholder’s right to the specified number of shares
Issued by the company and signed by the directors or authorized individuals
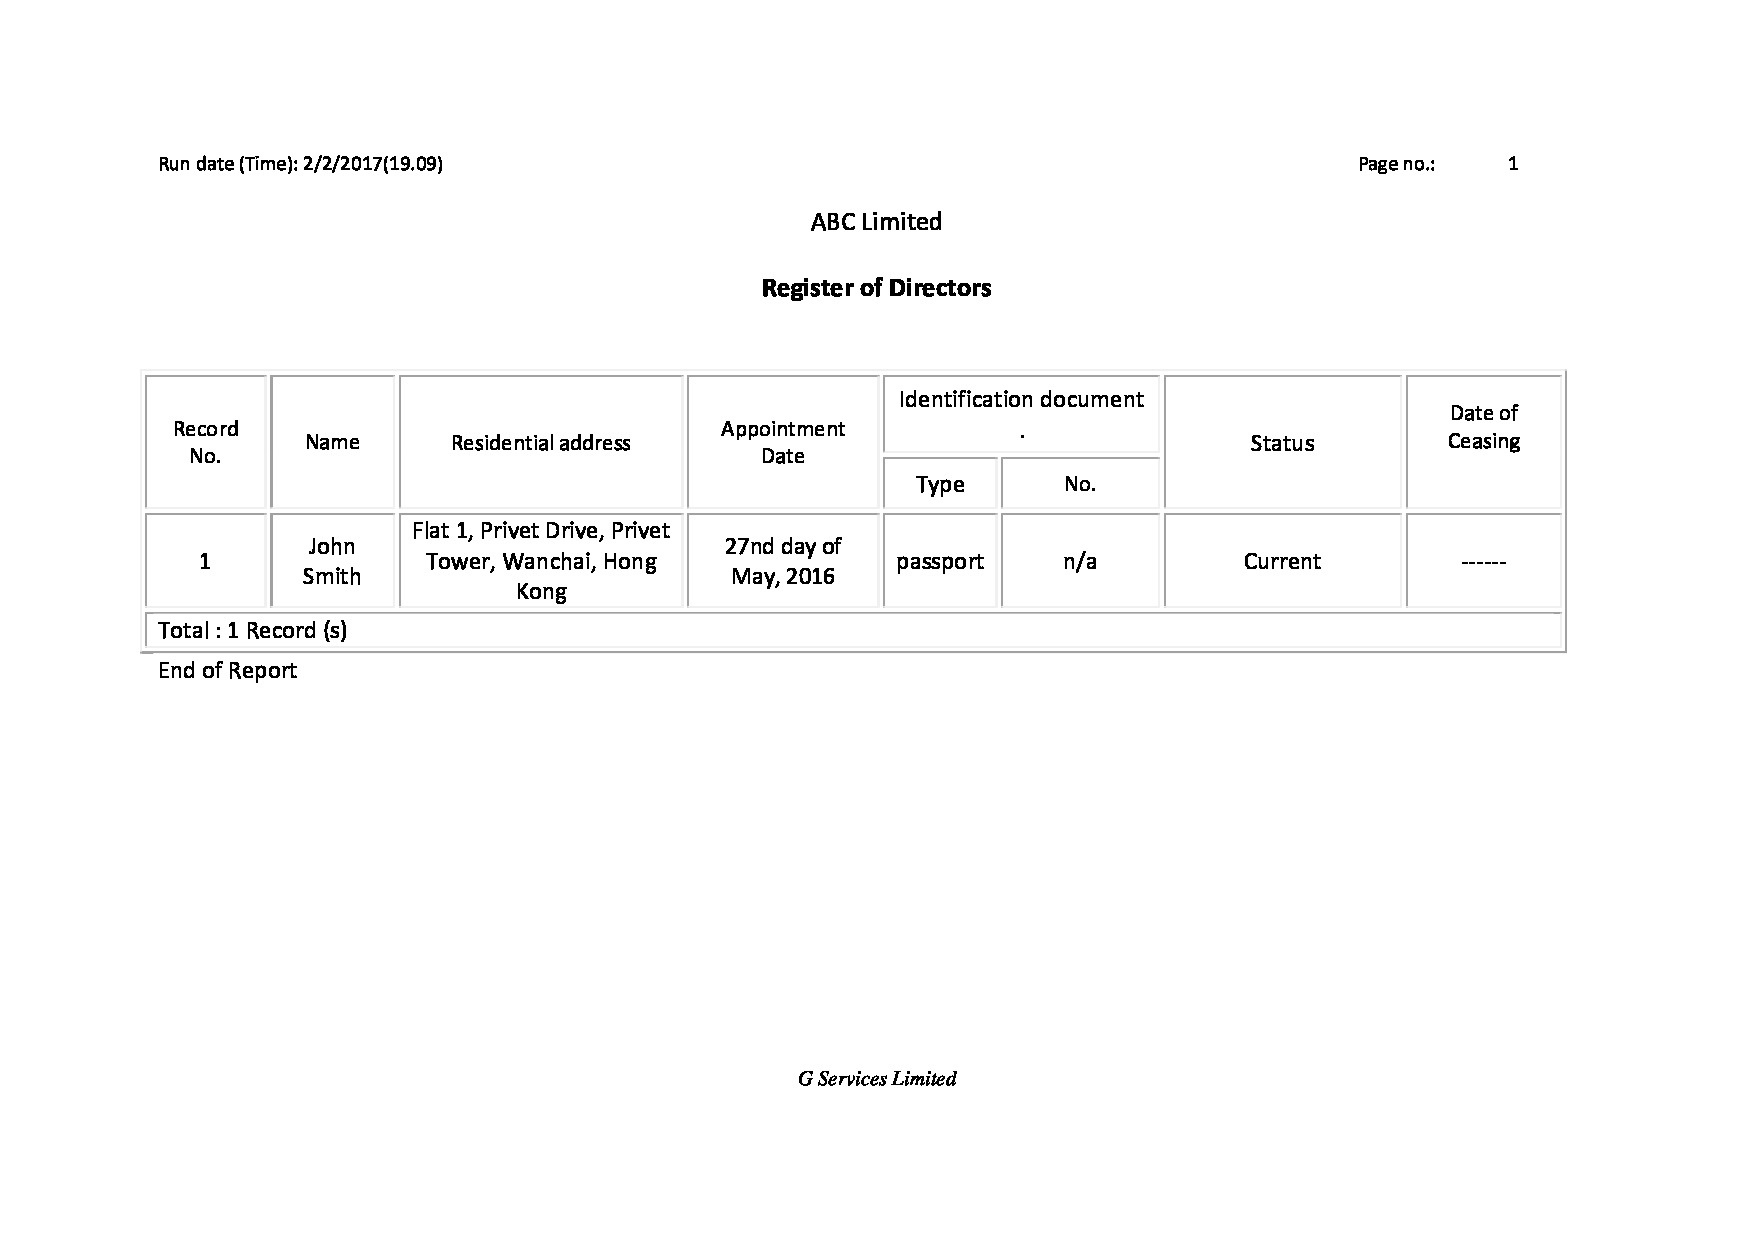
Maintained by the company in accordance with the Companies Ordinance, Cap. 622
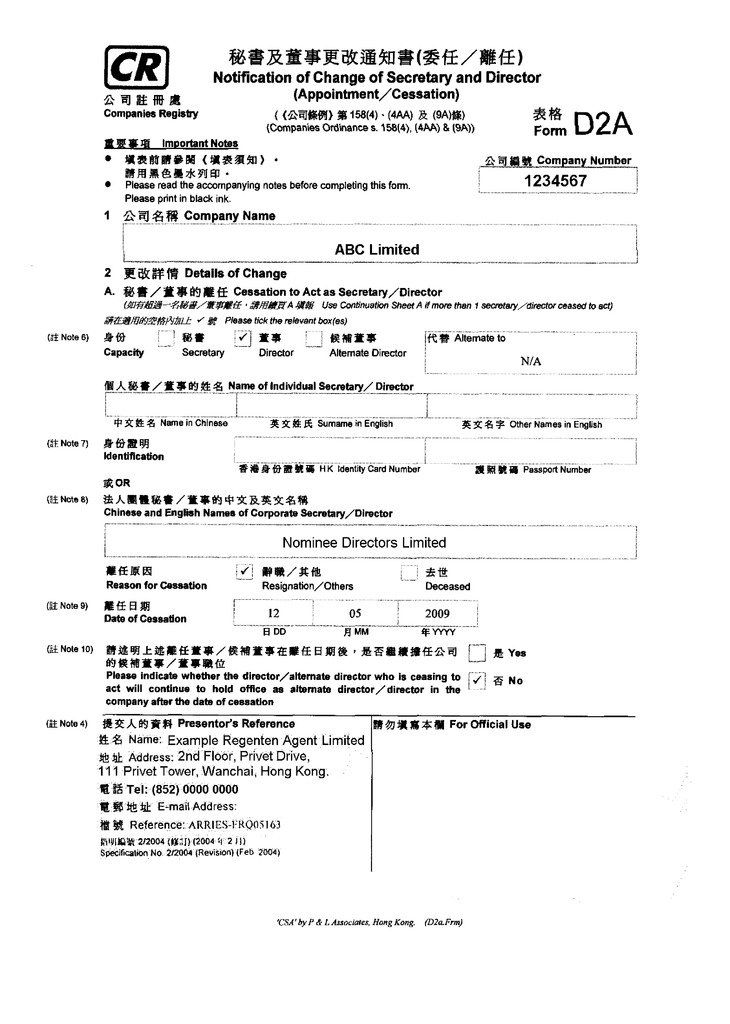
Contains information about the company directors, including their personal data and appointment dates
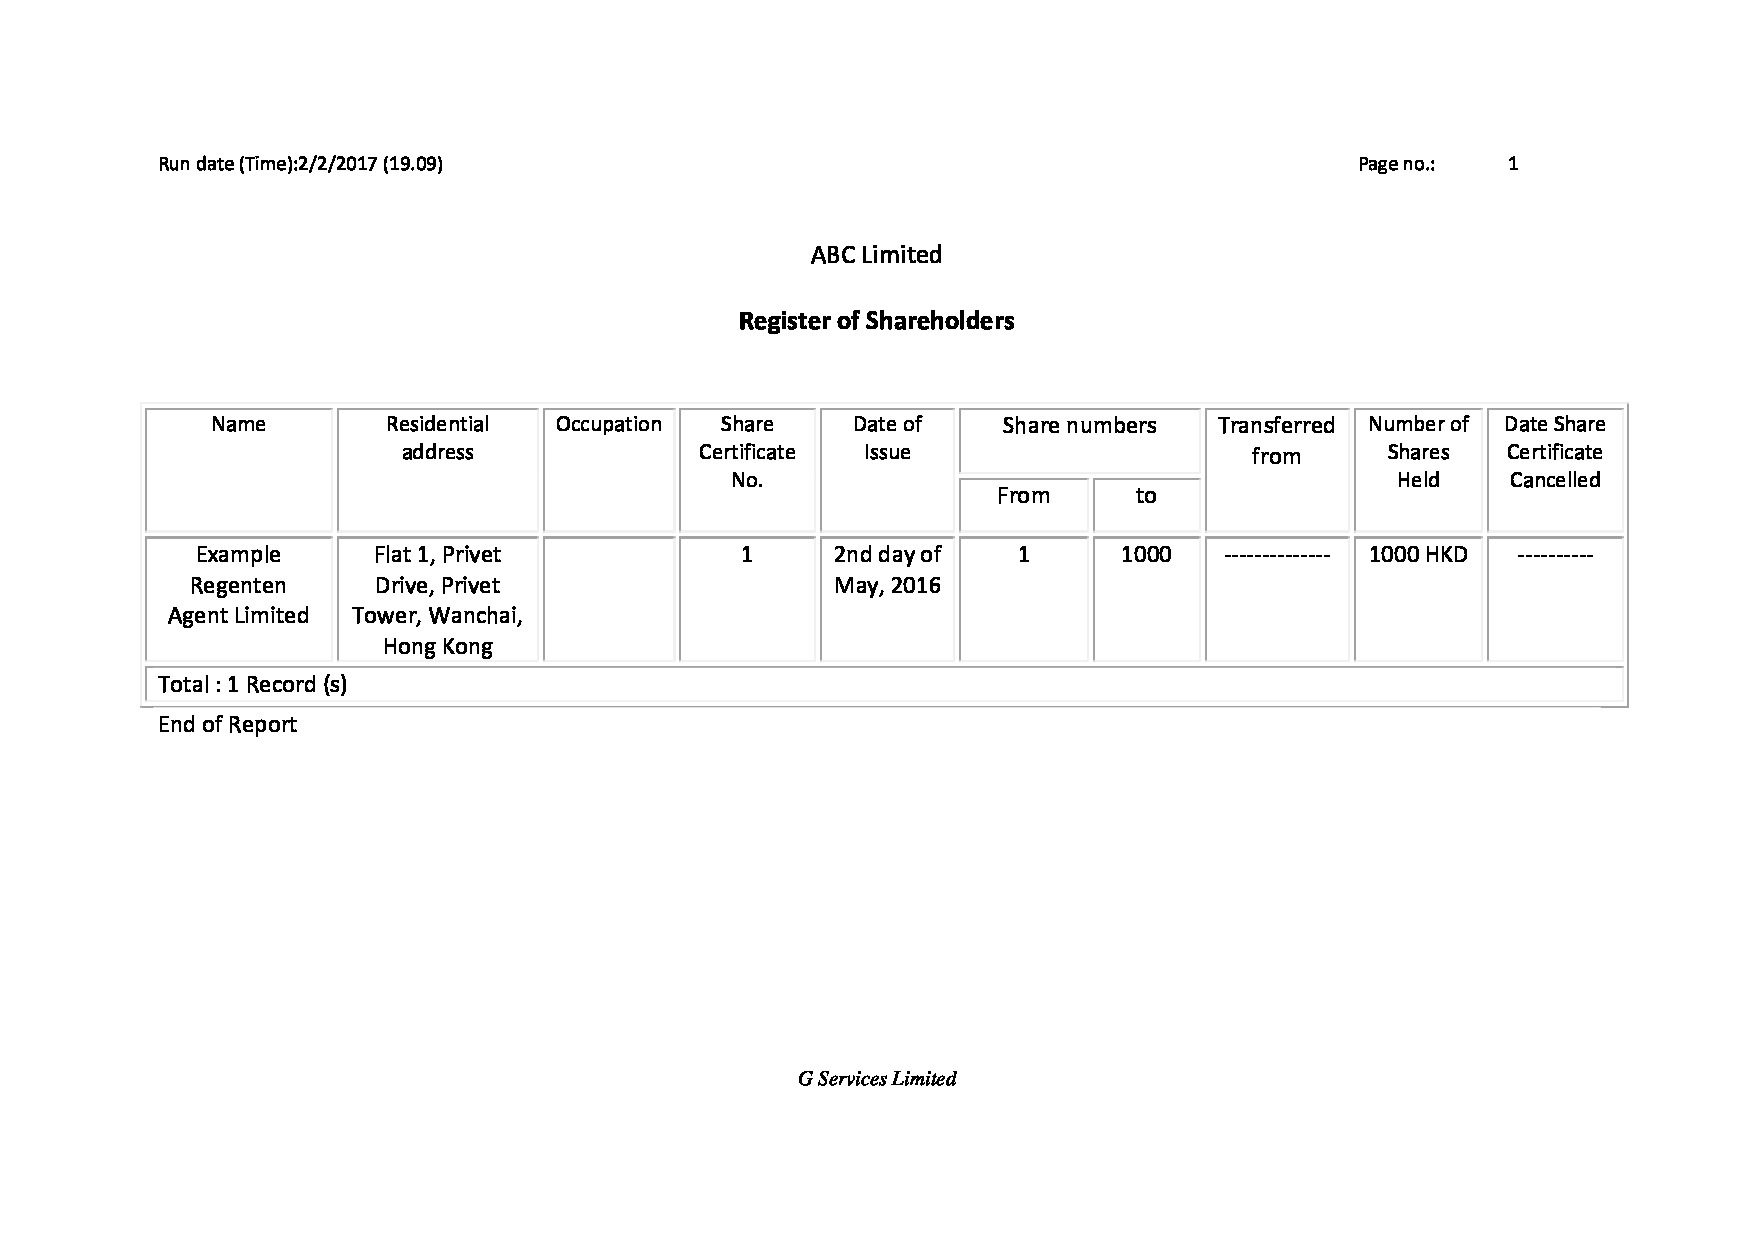
Contains details of the shareowners, including their names, addresses, and number of shares
Maintained by the company in accordance with the Companies Ordinance, Cap. 622
A free port with a highly developed transportation and brokerage infrastructure, convenient access to trade finance products, and an advantageous geographical location for transshipment and re-export within the region. Taxes are levied only on profits derived from Hong Kong; there is no VAT and no capital gains tax. Corporate registration and a bank account are typically sufficient for trading.
Convenient international payment and banking infrastructure, simple incorporation process, and a favorable tax base for international sales. Well-suited for platforms, SaaS (Software as a Service), online retail, and digital services. The sale of goods/services not “derived” from Hong Kong may be exempt from local tax (territorial principle), though the VAT/customs regulations of the buyer’s country must be considered.
Favorable tax environment (no tax on dividends and no capital gains tax), a mature banking and legal ecosystem, and a network of double taxation treaties. Frequently used for holding overseas assets and distributing dividends. However, utilizing double taxation treaties may require a physical presence (economic substance).
Preferential access to the Mainland China market and the opportunity to conduct business on favorable terms under the Closer Economic Partnership Arrangement (CEPA), subject to meeting specified criteria, including obtaining Hong Kong Service Supplier status.
Activity: for currency exchange, international money transfers, and related money services.
Regulator: Customs and Excise Department (oversight within the AML framework).
Operational Obligations: maintaining transaction records, conducting client due diligence, filing suspicious activity reports, record retention, and regulatory inspections.
Consequences of Non-compliance: fines, suspension or revocation of registration, and potential criminal liability.
Key Difficulties When Opening an Account:
Hong Kong remains one of the leading financial jurisdictions, however, bank requirements for clients have significantly tightened, especially for non-residents. Priority is given to companies with an active business in Asia and clients with proven economic substance.
Offer a full range of services, including multi-currency accounts and trade finance.
Strict compliance and a high probability of rejection for non-residents.
Fast onboarding and simplified procedures.
Limited functionality compared to traditional banks.
The client conducts international trade, importing sports goods primarily from China and several European countries. Due to the increasing complexity of calculations in USD and EUR, the client required a foreign company to facilitate operations, including transactions in RMB.
Given the mixed geography of partners (China and Europe), registering a company in Hong Kong was the most logical choice, as it serves as a neutral and well-understood international trade and financial hub. To ensure fast and guaranteed account opening, we submitted an application to a payment system in Kazakhstan. As part of the onboarding procedure, a coworking space lease agreement was arranged in Hong Kong as the most cost-effective way to provide proof of physical address. Later, an additional account was opened for the company in a Montenegrin bank.
The client received a fully operational structure for conducting business with Chinese and European partners. Having two accounts for the company and the ability to process transactions in RMB diversified the client’s payment infrastructure, making settlements more flexible, stable, and predictable.
The client required a company to trade cryptocurrency on major crypto exchanges using their own funds, with the subsequent goal of opening a corporate account.
We suggested registering a company in Hong Kong because cryptocurrency operations are permitted there without requiring a license, and the resulting income is not subject to tax provided there is no business activity or management within Hong Kong territory. Furthermore, the reputation of the jurisdiction increases the probability of successful account opening.
GSL registered the Hong Kong company after preliminary discussions with the client regarding both the advantages (absence of licensing and, under certain conditions, zero taxation) and the disadvantages of the chosen option (higher audit costs for companies with crypto assets and limitations in choosing banks and payment systems willing to onboard clients with such activities).
The bank where the Hong Kong company maintained its current account requested proof of presence (substance) in Hong Kong, specifying that this required not only a physical office but also employees.
The office was provided through a sublease agreement with our secretarial company. An employee provided by us was officially hired for the position of an office manager. This involved official employment of the worker, including notification to the tax authorities, registration, and mandatory contributions to the pension fund (MPF).
The company maintained its crucial bank account by confirming the presence of a real economic substance in the country of registration to the extent required by the bank. At the same time, the costs of organizing this presence were kept to a minimum. Subleasing the office helped avoid expenses related to searching for premises, and the administrative nature of the employee’s role allowed for a minimum salary payment without creating a risk of management being exercised from Hong Kong territory, which would make the company tax resident.
A well-known legal consulting firm is opening an office in Hong Kong to register and service local companies and is deploying personnel to work there.
Since the employees were being hired by a newly established Hong Kong company, another legal entity from the client’s corporate group acted as a sponsor. GSL organized the collection and translation of all necessary documents for the employees, their families, the employer, and the sponsor, reviewed the employment contracts for compliance with local legislation, and refined the business plan. GSL specialists completed and submitted the applications with the full package of documents to the Immigration Department, tracked the status, and promptly provided additional information upon request.
The immigration authority approved the issuance of work visas for the company’s employees and dependency visas for the moving family members. GSL successfully managed the complex visa process, which in Hong Kong is not a mere formality with a guaranteed outcome and is characterized by a large volume of documents and required clarifications.
The dissolution of a local private company under the Companies Ordinance (Cap. 622) can be achieved via formal liquidation (winding up) or a simplified administrative procedure known as deregistration. Alternatively, a company may be dissolved involuntarily if the Registrar exercises its statutory power to strike the company off the register.
1. Voluntary Deregistration
Deregistration is a simplified, cost-effective exit route designed strictly for defunct, solvent private companies. To qualify for this procedure under Section 750, a company must satisfy the following cumulative criteria:
It is also required to obtain a written Notice of No Objection from the Commissioner of Inland Revenue. This is only granted if there are no outstanding tax returns or liabilities due to the Hong Kong Government.
Once submitted, the Companies Registry publishes a notice in the Gazette. If no objections are received within 3 months, a final notice is published, and the company is officially dissolved.
2. Involuntary Striking Off (Section 744 / 746)
Striking Off is a statutory enforcement action initiated by the Registrar of Companies, if there is reasonable cause to believe the company has ceased operations or failed to maintain corporate compliance (e.g., filing backlogs, no active Company Secretary, or failure to maintain a registered office address).
Some businesses deliberately stop making filings to force a strike-off. However, until the company is officially struck off and dissolved, it remains in breach of statutory duties.
The dissolution of a company via a strike-off does not release directors or shareholders from their liabilities. Outstanding penalties accumulate, and directors remain exposed to direct prosecution and potential disqualification.
To restore a previously dissolved company to the state register, an application for restoration must be submitted to the court within 12 years from the publication date of the striking-off notice in the official gazette. If the court determines that the legal requirements are met, it issues a restoration order to be submitted to the Registrar of Companies.
Upon registration, the company is deemed to have continued in existence as if it had never been struck off.
The court can also issue specific directions to restore the company and all affected parties to the exact legal and financial position they would have held if the dissolution had never occurred.
All Hong Kong companies are required to annually prepare and submit audited financial statements with a directors’ report, a Profits Tax Return, and an Employer’s Return to the Inland Revenue Department.
Exception: “dormant” companies (no bank transactions, contracts, or invoices) submit only the tax return.
Active companies are required to prepare audited financial statements regardless of whether they conduct business within Hong Kong or abroad.
The first financial period spans 12–18 months from the company’s incorporation date, with subsequent periods lasting 12 months each. The audited financial statements must be prepared prior to filing the tax return, as they are a mandatory attachment to the return.
The tax year ends on March 31. On the first business day of April, the Inland Revenue Department issues tax returns. The deadline for a company to submit its return is 1 month from the date indicated on the return, with an option to extend the deadline depending on the reporting date (based on codes N, D, M specified in the return). For new companies, the first return is issued 12–18 months after incorporation and must be submitted within 4 months.
The Employer’s Return is also issued by the Inland Revenue Department on the first business day of April and must be submitted within one month.
Hong Kong provides two regimes for financial reporting: the reporting exemption (simplified) and the full regime. The simplified reporting framework can be applied by:
Simplified reporting reduces disclosure requirements and exempts directors from preparing a business review. Companies that do not meet these criteria must prepare full financial statements, including more comprehensive financial data and analytical information regarding the company’s operations.
Consolidated financial reporting is mandatory if there are subsidiary companies (more than 50% ownership or actual control). An exception applies if the parent company already prepares consolidated financial statements.
Financial statements are prepared in accordance with the Hong Kong Financial Reporting Standards (HKFRS) or the Standards for Small and Medium-Sized Entities (SME-FRS), which are aligned with IFRS.
Financial Statements include:
There are no penalties for the late submission of financial statements themselves, however, their absence blocks the submission of the tax return. Late filing of the tax return is punishable by a fine ranging from HKD 1,200 to HKD 10,000 + a triple tax penalty on the amount due.
If the company has previously generated a profit, the Inland Revenue Department may assess a provisional tax at a rate of 16.5% even in the absence of current activity.
Late submission of the Employer’s Return incurs a fine of up to 10,000 HKD + the issuance of court summons + a triple penalty on the undercharged tax amount.
Hong Kong applies a territorial system of taxation: only income derived from sources within Hong Kong is subject to tax. There is no VAT, no capital gains tax, no dividend tax, no withholding tax on interest and dividends, and no foreign exchange control. Hong Kong combines low base rates with targeted tax incentives designed to support businesses, innovation, and international structures.
Yes, a Hong Kong company can hire foreign employees to work both within Hong Kong and abroad. To work within Hong Kong, work visas must be obtained. When hiring employees working outside of Hong Kong, the company must submit a remuneration/salary return to the Inland Revenue Department, and the employees will be exempt from Salaries Tax provided their stay in Hong Kong does not exceed 60 days during the financial year.
The cost of opening a company in Hong Kong depends on the type of company registered and the nature of the business activity you will engage in. The minimum service package costs $2,500 USD and includes: turnkey company registration, a registered office for a year and secretarial services, payment of all necessary duties and fees, as well as an apostilled set of incorporation documents.
The registration process for a new company in Hong Kong takes on average 1 to 4 business days, provided all documents are prepared correctly and submitted electronically. After receiving the certificate of incorporation, an additional 7-9 days are required to prepare the full set of statutory documents, perform notary certification, legalization, and, if necessary, apostilling for use outside of Hong Kong.
Yes, in Hong Kong, foreign citizens and non-residents can incorporate a company under the same conditions as local individuals. There are no restrictions regarding the citizenship or place of residence of the founders.
The registration process is entirely remote and includes several stages: choosing a company name, preparing statutory documents, submitting an application to the Companies Registry, and registering with the Inland Revenue Department (IRD). If the company’s business activity requires licensing (e.g., financial services, logistics, education), the relevant permits must be additionally obtained.
The Unique Business Identifier (UBI) is introduced to provide a single, unambiguous identification for legal entities in inter-departmental data exchange and business relations, reducing errors arising from using multiple numbers and simplifying administration.
In Hong Kong, the Business Registration Number (BRN), i.e. the first 8 digits of the Business Registration Certificate number—has been adopted as the UBI. For companies incorporated starting from December 27, 2023, this number is also specified as the registration number on the Certificate of Incorporation.
A name registered with the Companies Registry does not grant an automatic right to a trademark. Registering a company name as a trademark with the Intellectual Property Department (IPD) is possible if the trademark meets the eligibility criteria, meaning it distinguishes the applicant’s goods or services from others, is not descriptive or generic, does not mislead consumers, and does not infringe upon third-party rights.
It is recommended to conduct a preliminary search in the database of registered and pending trademarks using the IPD online system (http://ipsearch.ipd.gov.hk) to avoid overlap and the risk of infringement disputes.
The registration procedure consists of two stages:
No, the audited Directors’ Report for the financial year differs in its purpose and content from the company’s Annual Return and is not equivalent to it. The Directors’ Report discloses information about the company’s business operations, principal risks, uncertainties, and likely future development, that is the information material for shareholders to assess the company’s state (under Section 390 of the Ordinance and Schedule 5).
The Annual Return is a separate declaration on Form NAR1 submitted in the prescribed manner to the Companies Registry; these two documents serve different purposes and do not substitute for one another.
Company directors are required to prepare a Directors’ Report for the financial statements for each financial year, including a consolidated report in the case of a holding company. Exemptions are provided for certain categories of companies (e.g., wholly-owned subsidiaries).
Failure to comply with the obligation to prepare a directors’ report may result in fines of up to 150,000 HKD, and in cases of willful violation, potential imprisonment for up to 6 months.
Hong Kong legislation clearly defines the duties of directors, which are aimed at protecting the interests of the company and its members. First and foremost, directors owe a fiduciary duty—they must act honestly, in good faith, and in the best interests of the company as a whole, rather than for personal gain. Furthermore, directors are required to exercise due diligence when performing their functions.
Directors must ensure:
Failure to perform these duties entails both civil and criminal liability: penalties include fines, disqualification from holding a directorship, and, in certain cases of fraud or severe negligence, personal liability for the company’s debts.
The Business Registration Certificate is issued by the Inland Revenue Department for a term of 1 or 3 years. Additionally, the filing of the Annual Return serves as confirmation of the company’s renewal for the following year, displaying the structure and key data of the company: share capital, address, secretary, directors, and shareholders, as of each anniversary of the company’s incorporation date.
Furthermore, a Certificate of Continuing Registration (CCR) can be obtained from the Registry—this is an official confirmation that the company specified in the document remains on the register of incorporated legal entities as of the date of issue.
The certificate states the current names and the date of incorporation or redomiciliation; the document is widely accepted as proof of the company’s good standing before local and foreign authorities and institutions. An application for the certificate can be submitted online via the Registry’s e-Services Portal (www.e-services.cr.gov.hk). Once processed, the CCR is typically ready within 6 hours of ordering.
The Significant Controllers Register can be inspected by the significant controllers themselves, as well as by law enforcement agencies within their powers (including the Companies Registry, Customs and Excise Department, Hong Kong Monetary Authority, police, Inland Revenue Department, and Securities and Futures Commission).
The company is required to appoint a representative to assist with the inspection of the Register. Such a representative can be a shareholder, director, or another employee of the company who is an individual and a Hong Kong resident, or a certified auditor, lawyer, or a licensed trust and company service provider.
If access to the register is not provided upon request of a law enforcement agency, the relevant officer may apply to the court, and the court may order the company to permit the inspection and/or allow copying of the register, including issuing orders against third parties where the Register is stored. Refusal or failure to provide the Register results in criminal liability for the company and responsible officers: a fine of up to 25,000 HKD and an additional daily fine of 700 HKD; similar sanctions apply for non-compliance with the procedures for entering and updating information.
In Hong Kong, it is possible to establish both discretionary and specific trusts. Trust documents are not subject to registration. The law establishes no requirements for a trust to file an annual return, audited financial statements, etc., provided it does not conduct business within the territory of Hong Kong.
Unlike most offshore jurisdictions, Hong Kong has not reformed its trust legislation to become a more attractive territory for establishing trusts. In this regard, perhaps the only interesting tool is a private trust company, which can be used for private (typically family) purposes.
A private trust company in Hong Kong must comply with all requirements established for companies limited by shares, and is not entitled to use the word “trust” or “trustee” in its name or provide trust services to the general public.
Thus, the main function of a private trust company is that it acts as a trustee in relation to a single family or a group of interconnected trusts. Depending on the situation of a particular family or its goals and objectives, a private trust company in Hong Kong offers a number of advantages: it allows founders to plan the future ownership structure of a family business, retain control over the management of investments transferred to the trust, and ensures financial confidentiality.
Unlike traditional trust structures where the founder typically relinquishes control over the trust assets, a private trust company in Hong Kong allows the founder and their family to remain involved in the management, investment, and disposal of the trust assets, while ensuring the protection of the trust beneficiaries’ interests.
Yes, as a rule, a meeting is required. Under the Companies Ordinance (Cap. 622), a company is required to hold a general meeting as its annual general meeting for each financial year within 9 months after the end of the reporting period (for private companies). For cases involving the first extended or shortened period, the deadlines for holding the meeting are calculated separately.
However, holding an annual general meeting is not required if:
The Employer’s Return of Remuneration and Pensions is an employer’s declaration on Form BIR56A, which employers submit to the Inland Revenue Department (IRD) regarding payments to employees for salaries, allowances, and pensions for the financial year (together with Form IR56B—an individual certificate of income for each employee).
A request to submit the return usually arrives within 12-18 months after the company’s registration; the return itself must be submitted within one month from the date the request is received.
The cost of submitting the return ranges from $365 USD for a company without employees (a nil return, submitted once) to $830 USD for 4-5 employees. In companies with employees, the return is submitted annually. Furthermore, when hiring a new employee, a notification is submitted ($280 USD) within 3 months from the date the employment contract is signed.
Failure to submit the return incurs a fine of 2,400 HKD ($310 USD), and in cases of regular failure to submit the return, the company may be struck off the register by a court decision.