1.
Private Company Limited by Shares
The most common type for small and medium-sized businesses. Shareholders (no more than 50) bear risk only up to the amount of their contributions. Shares cannot be freely offered to the general public.

Cyprus gives companies access to the European Single Market and operates under EU-wide standards for regulation and investor protection
Corporate law is based on English common law, while tax and financial regulations are harmonised with EU requirements
Cyprus imposes no withholding tax on dividends, interest, or royalties (subject to conditions), nor on capital gains
A network of treaties with over 70 countries allows for the further optimisation of taxation of various types of income
All procedures can be completed remotely; no need to travel to Cyprus to have the company registered
Cyprus is not included in the lists of non-cooperative jurisdictions maintained by the FATF or the OECD.
Even a very basic structure requires significant annual investment
Cyprus banks are cautious regarding residents from non-European countries; they often request additional documentation, take their time reviewing account applications or refuse to open accounts altogether
An individual conducting business under their own name, bearing full personal liability for all business obligations and debts.
Joint operation of a business by two or more partners who bear personal liability for the partnership’s obligations. Regulated by the General and Limited Partnership and Business Names Law, Cap. 116.
Consists of at least one general partner who bears unlimited liability and manages the business, and limited partners (contributors) with limited liability who have no management rights.
A branch is not a separate legal entity and bears liability jointly with the parent company. A foreign company’s branch is registered as an ‘overseas company with a place of business’ in Cyprus under the Companies Law.
A legal arrangement for holding and managing assets for the benefit of beneficiaries. It is used in private wealth management and estate planning.
Department of Registrar of Companies and Intellectual Property of the Ministry of Commerce, Industry and Tourism of the Republic of Cyprus
Whether a proposed company name is available can be checked free of charge via the online Organisation and Name Search service at the Registrar of Companies website. It is also advisable to check the name by doing a search in the trademark database of the Intellectual Property Section.
Minimum 1 director
Individual or corporate
Resident or non-resident
! To be a tax resident of Cyprus and eligible to apply the double taxation treaties, a Cyprus company must be managed and controlled from Cyprus, meaning the majority of its directors must be residents.
Director’s details are provided to the local agent and entered into the public register
Mandatory for every company
Individual or corporate entity
Resident or non-resident
The secretary cannot be:
Not applicable to a single-member private limited company
One or more shareholders (up to 50)
Individuals and corporate entities, residents or non-residents
A sole shareholder can act as the company’s director
Shareholder’s details are provided to the local agent and entered into the public register
Details of the beneficial owner are provided to the local agent and the auditor and may be disclosed by them only in cases prescribed by law and in accordance with a specific procedure.
In addition, the beneficial ownership information will be requested by the bank when opening an account.
A beneficial owner is defined as an individual who ultimately exercises control over a company. The ultimate control is understood as direct or indirect (through another company, a trust, etc.) shareholding of 25% + 1 share or more than 25% interest in the company’s share capital.
If it is impossible to identify the beneficial owner based on the shareholding/interest, additional criteria may be applied:
If it is still impossible to identify the beneficial owner, or if there are reasonable doubts about the authenticity of the beneficial control exercised by the identified individuals, the company’s director must prepare and retain a report on the steps taken to identify the beneficial owner, while the director’s details are entered into the register.
Separate criteria apply to trusts and foundations.
The introduction of the register of beneficial owners in Cyprus resulted from the transposition into national law of the EU’s 5th Anti-Money Laundering Directive. The Directive originally provide for a public register, a requirement Cyprus implemented by making beneficial ownership information available upon payment of a fee (EUR 3.50 per company) in the following – somewhat limited – format:
However, in November 2022, Cyprus suspended public access to the beneficial ownership register in compliance with a ruling by the Court of Justice of the European Union (CJEU). The Court determined that granting members of the general public access to information about beneficial owners of legal entities violated fundamental privacy and data protection rights under the EU Charter.
Full and unrestricted access to the information contained in the register is only available to competent and supervisory authorities of the Republic.
Cyprus relies on the English common law system, in which case law and precedents play a key role, ensuring flexibility and predictability in the application of the law.
At the same time, EU law is incorporated into national legislation, with EU rules taking precedence over conflicting national legal acts.
The primary corporate legislation is the Companies Law, Cap. 113.
A Cyprus company formation agent (Administrative Service Provider / ASP) is required under the terms of its licence to run a compliance check on individuals and legal entities within the structure of the companies under its administration. This entails collecting KYC documents relating to company directors and shareholders (unless nominee officers are used), the attorney (if a power of attorney is required), and the beneficial owner.
To register a company, a specific set of documents must be prepared:
The Memorandum defines the company’s basic structure, specifying its name, objects, share capital and its division into shares of a specific value, as well as other provisions relating to the company’s structural organisation. The Articles define the relationships between the various participants in the company and outline the procedures for convening shareholder meetings, making decisions, and transferring shares, including any applicable restrictions.
The Articles of Association may be of a standard form (Table A of the First Schedule to the Companies Law) or bespoke.
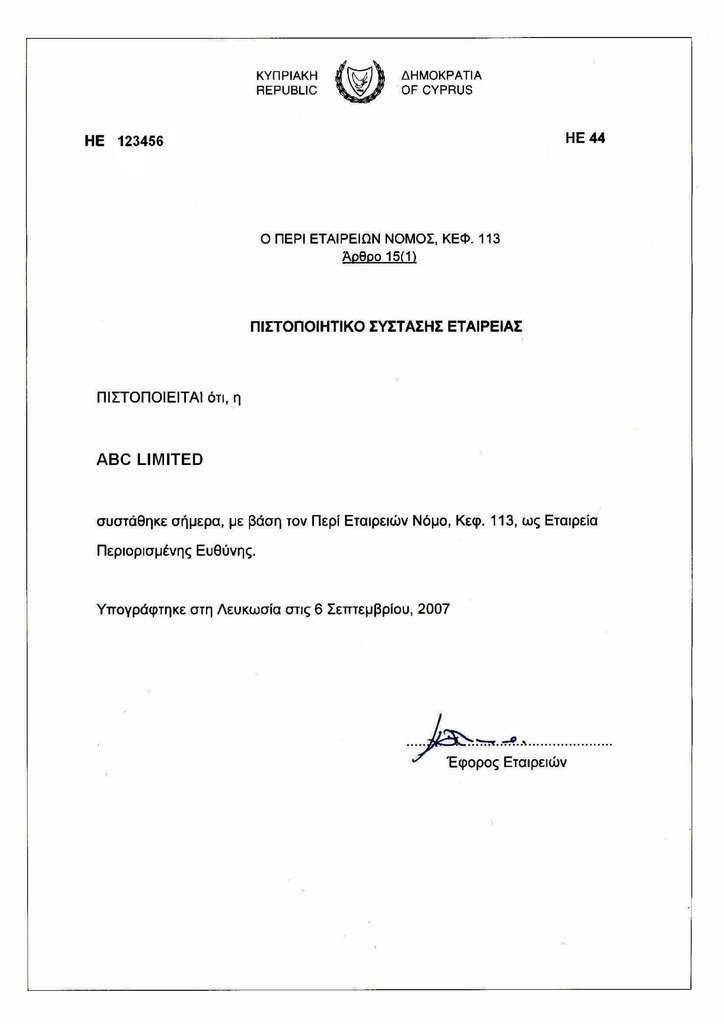
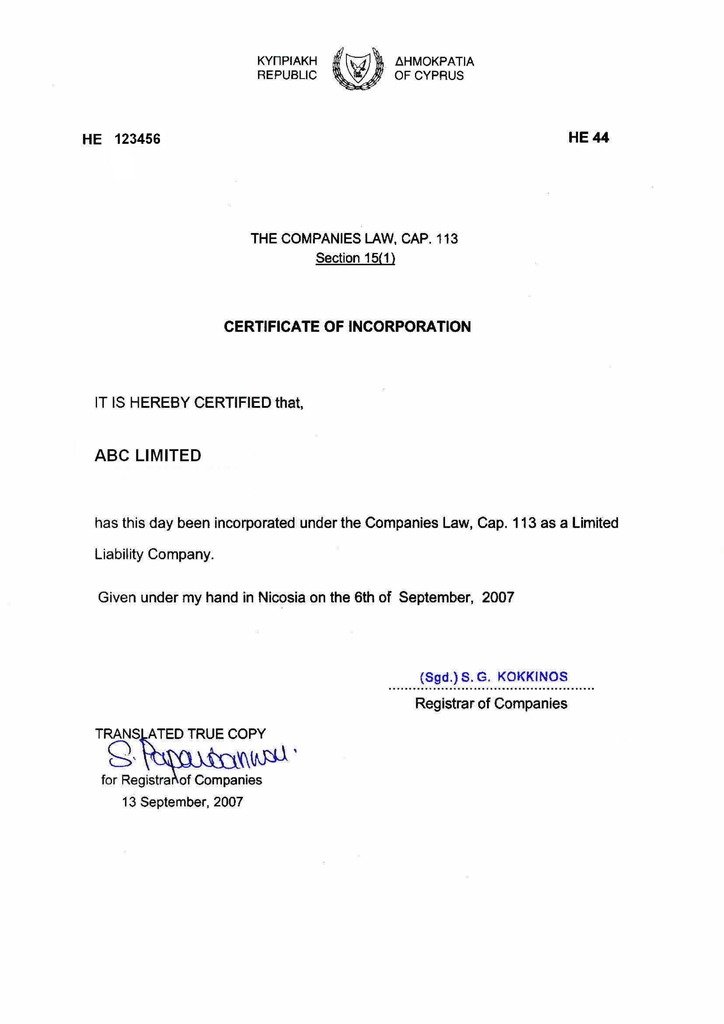
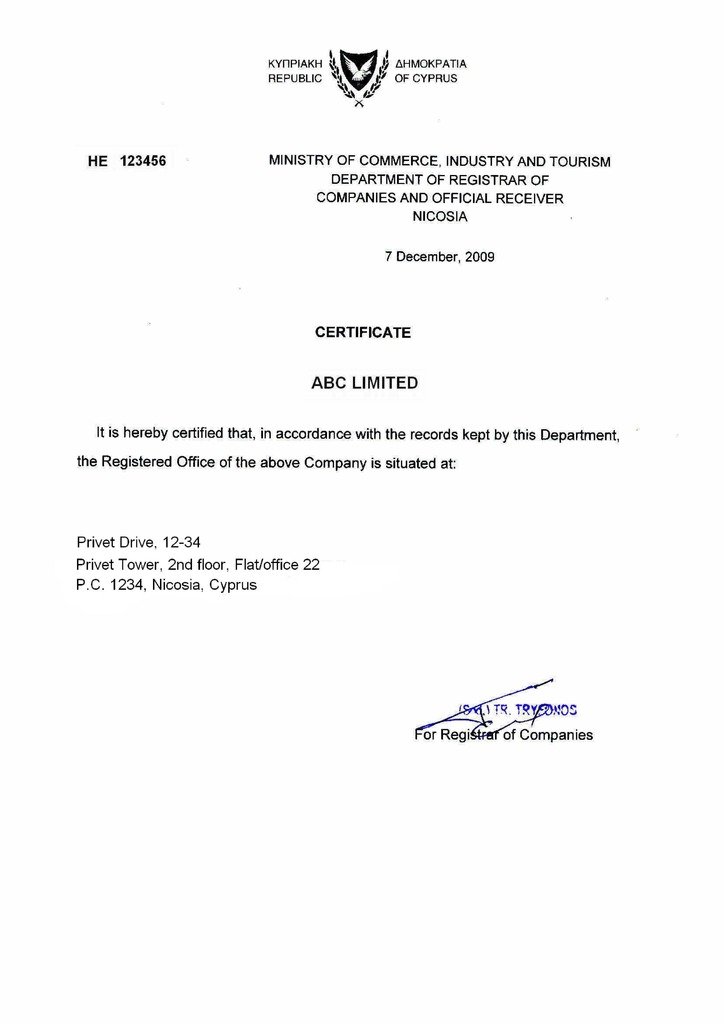
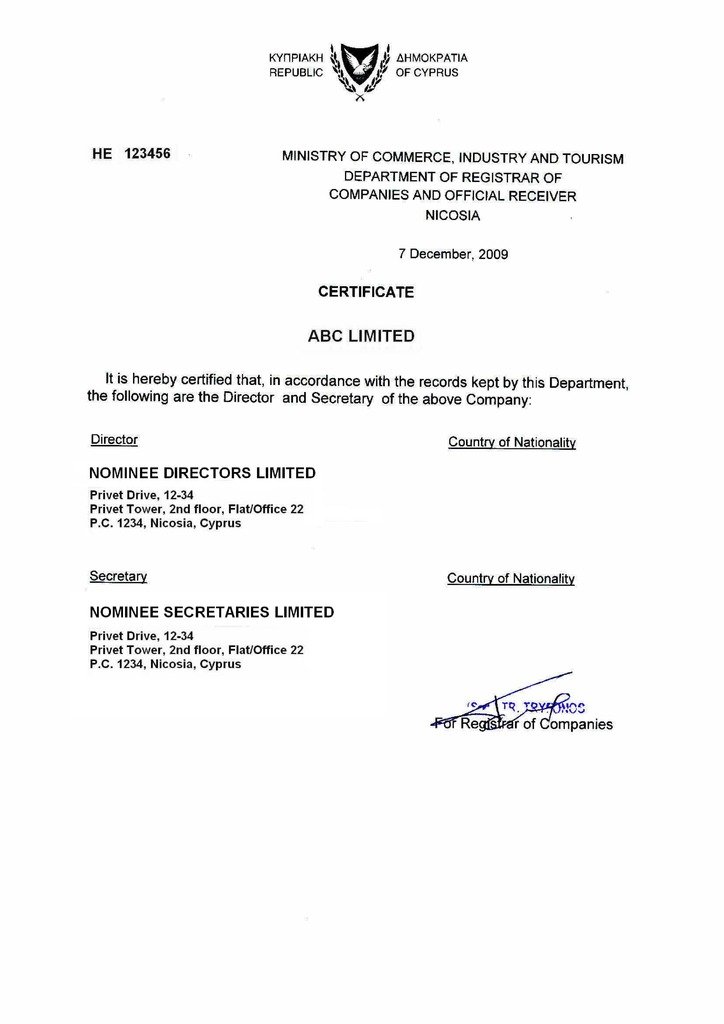
After reviewing the filings, the Registry issues the following documents to the company:
Processing times:
For use outside Cyprus (e.g., with banks or foreign partners), key corporate documents are apostilled. The post-incorporation package normally includes the following apostilled documents (provided separately, as they cannot be bound together):
The following documents are not apostilled and are provided to the client in their original form:
If a company plans to do business that requires an authorisation or licence (banking, insurance, financial services, catering, tourism, etc.), it must first apply for such authorisation or licence.
In order to truly become operational, a company opens a bank account:
Once the account is opened, a company can operate fully, making transactions and settlements with counterparties and clients.
The total cost of incorporation consists of registration fees, annual maintenance fees (payable one year in advance at the time of registration), legalised corporate documents package, and courier delivery to the destination.
(for 1 year, including an apostilled Power of Attorney)
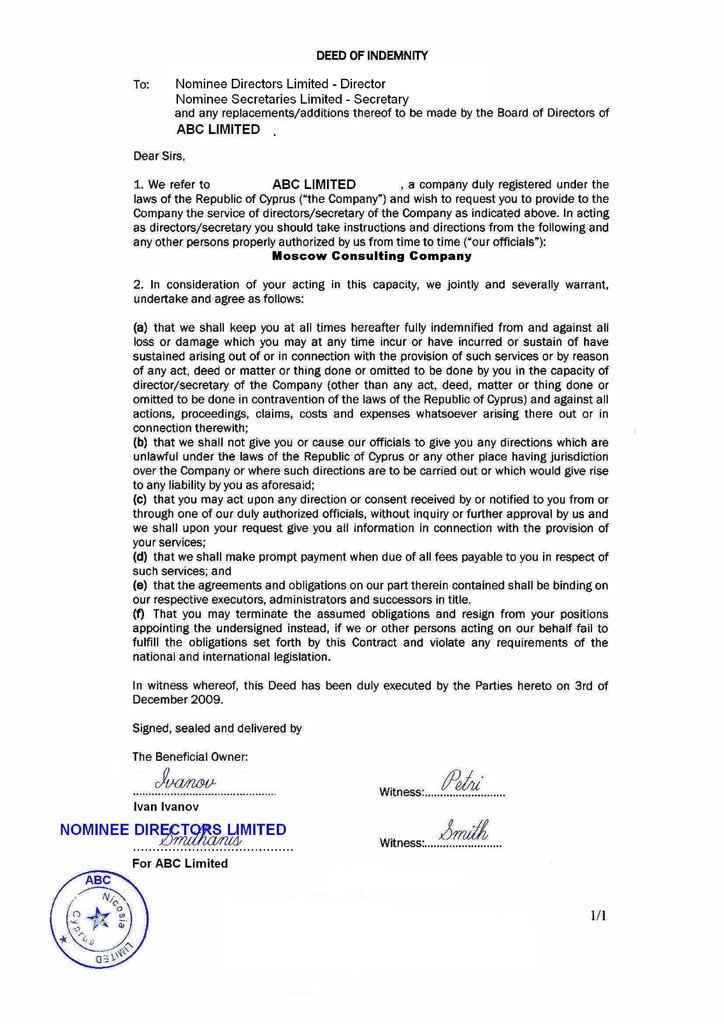
Deed of Indemnity
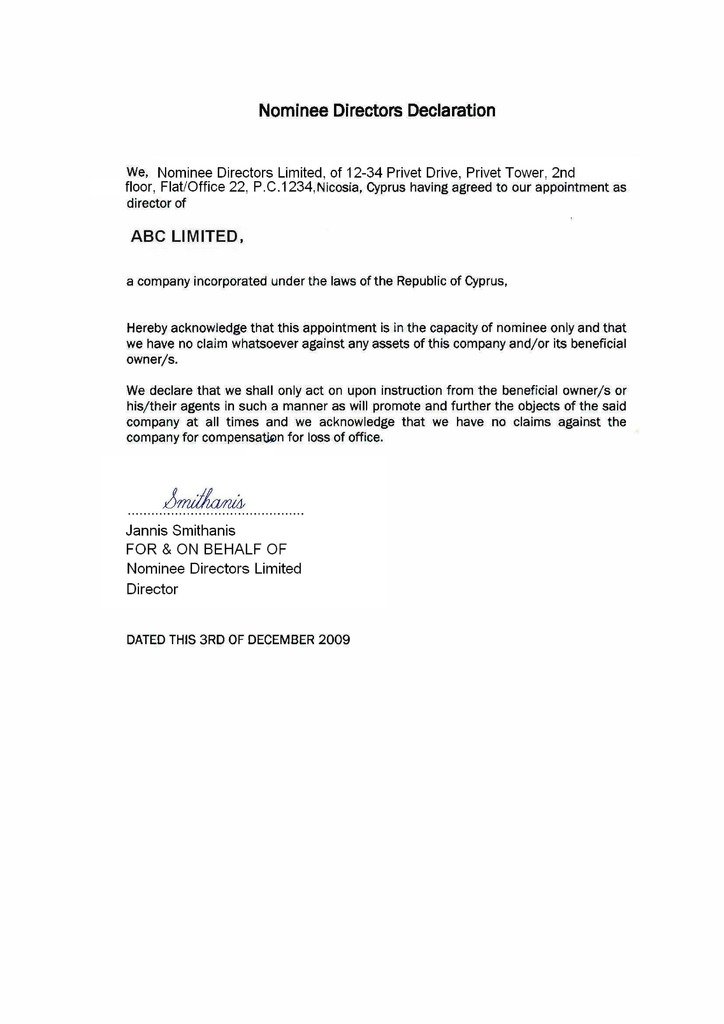
Nominee Director’s Declaration
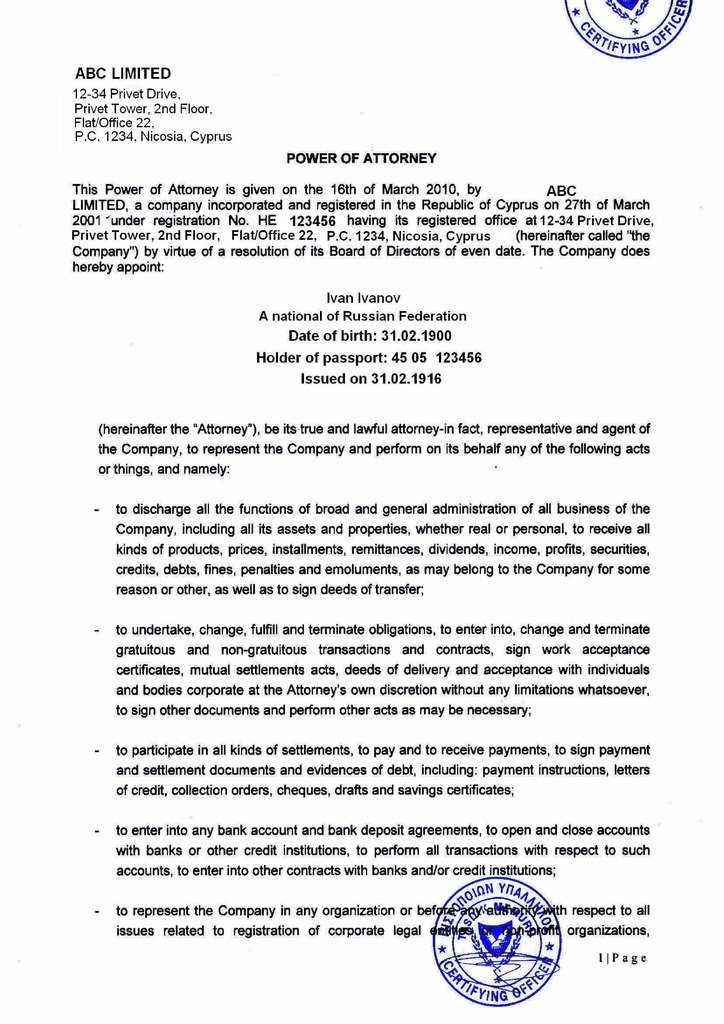
Power of Attorney
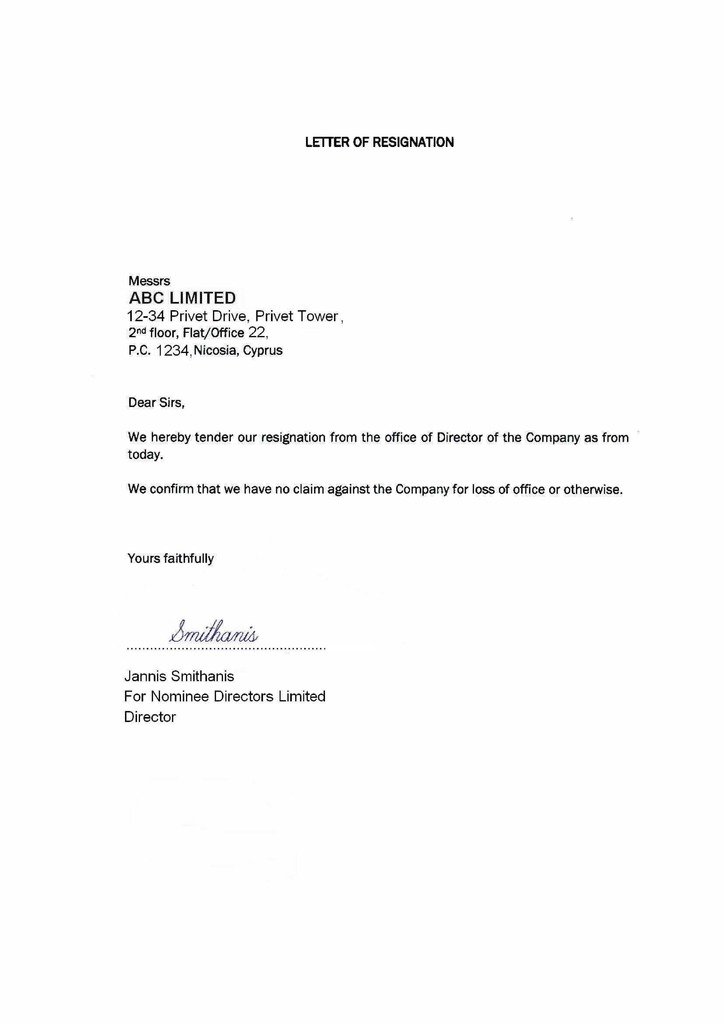
Director Resignation Letter
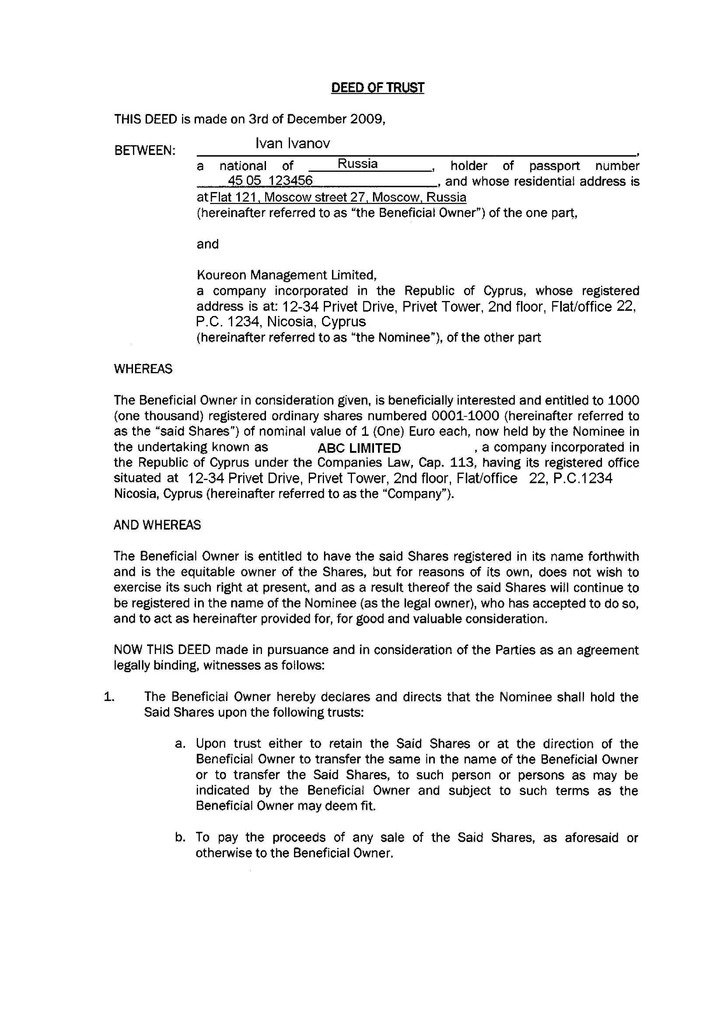
Deed of Trust
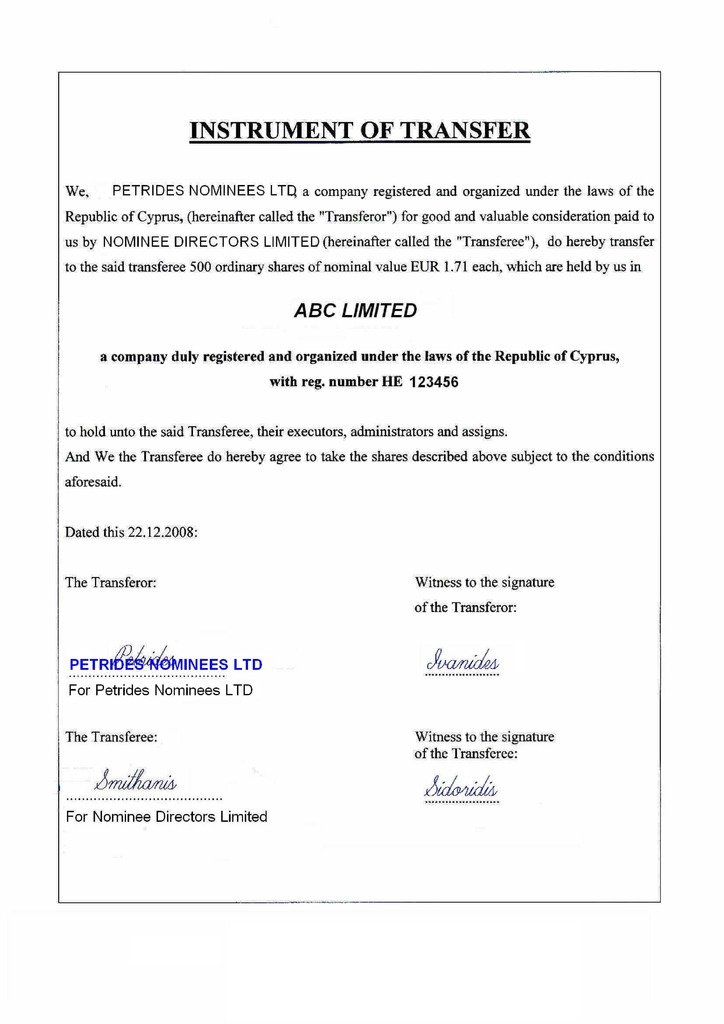
Instrument of Transfer
Payable in cases of: company registration, company renewal, company liquidation, transfer to a new agent, issuance of a Power of Attorney to a new attorney, change of director / shareholder / beneficial owner (except for changes to a nominee director / shareholder), signing of documents
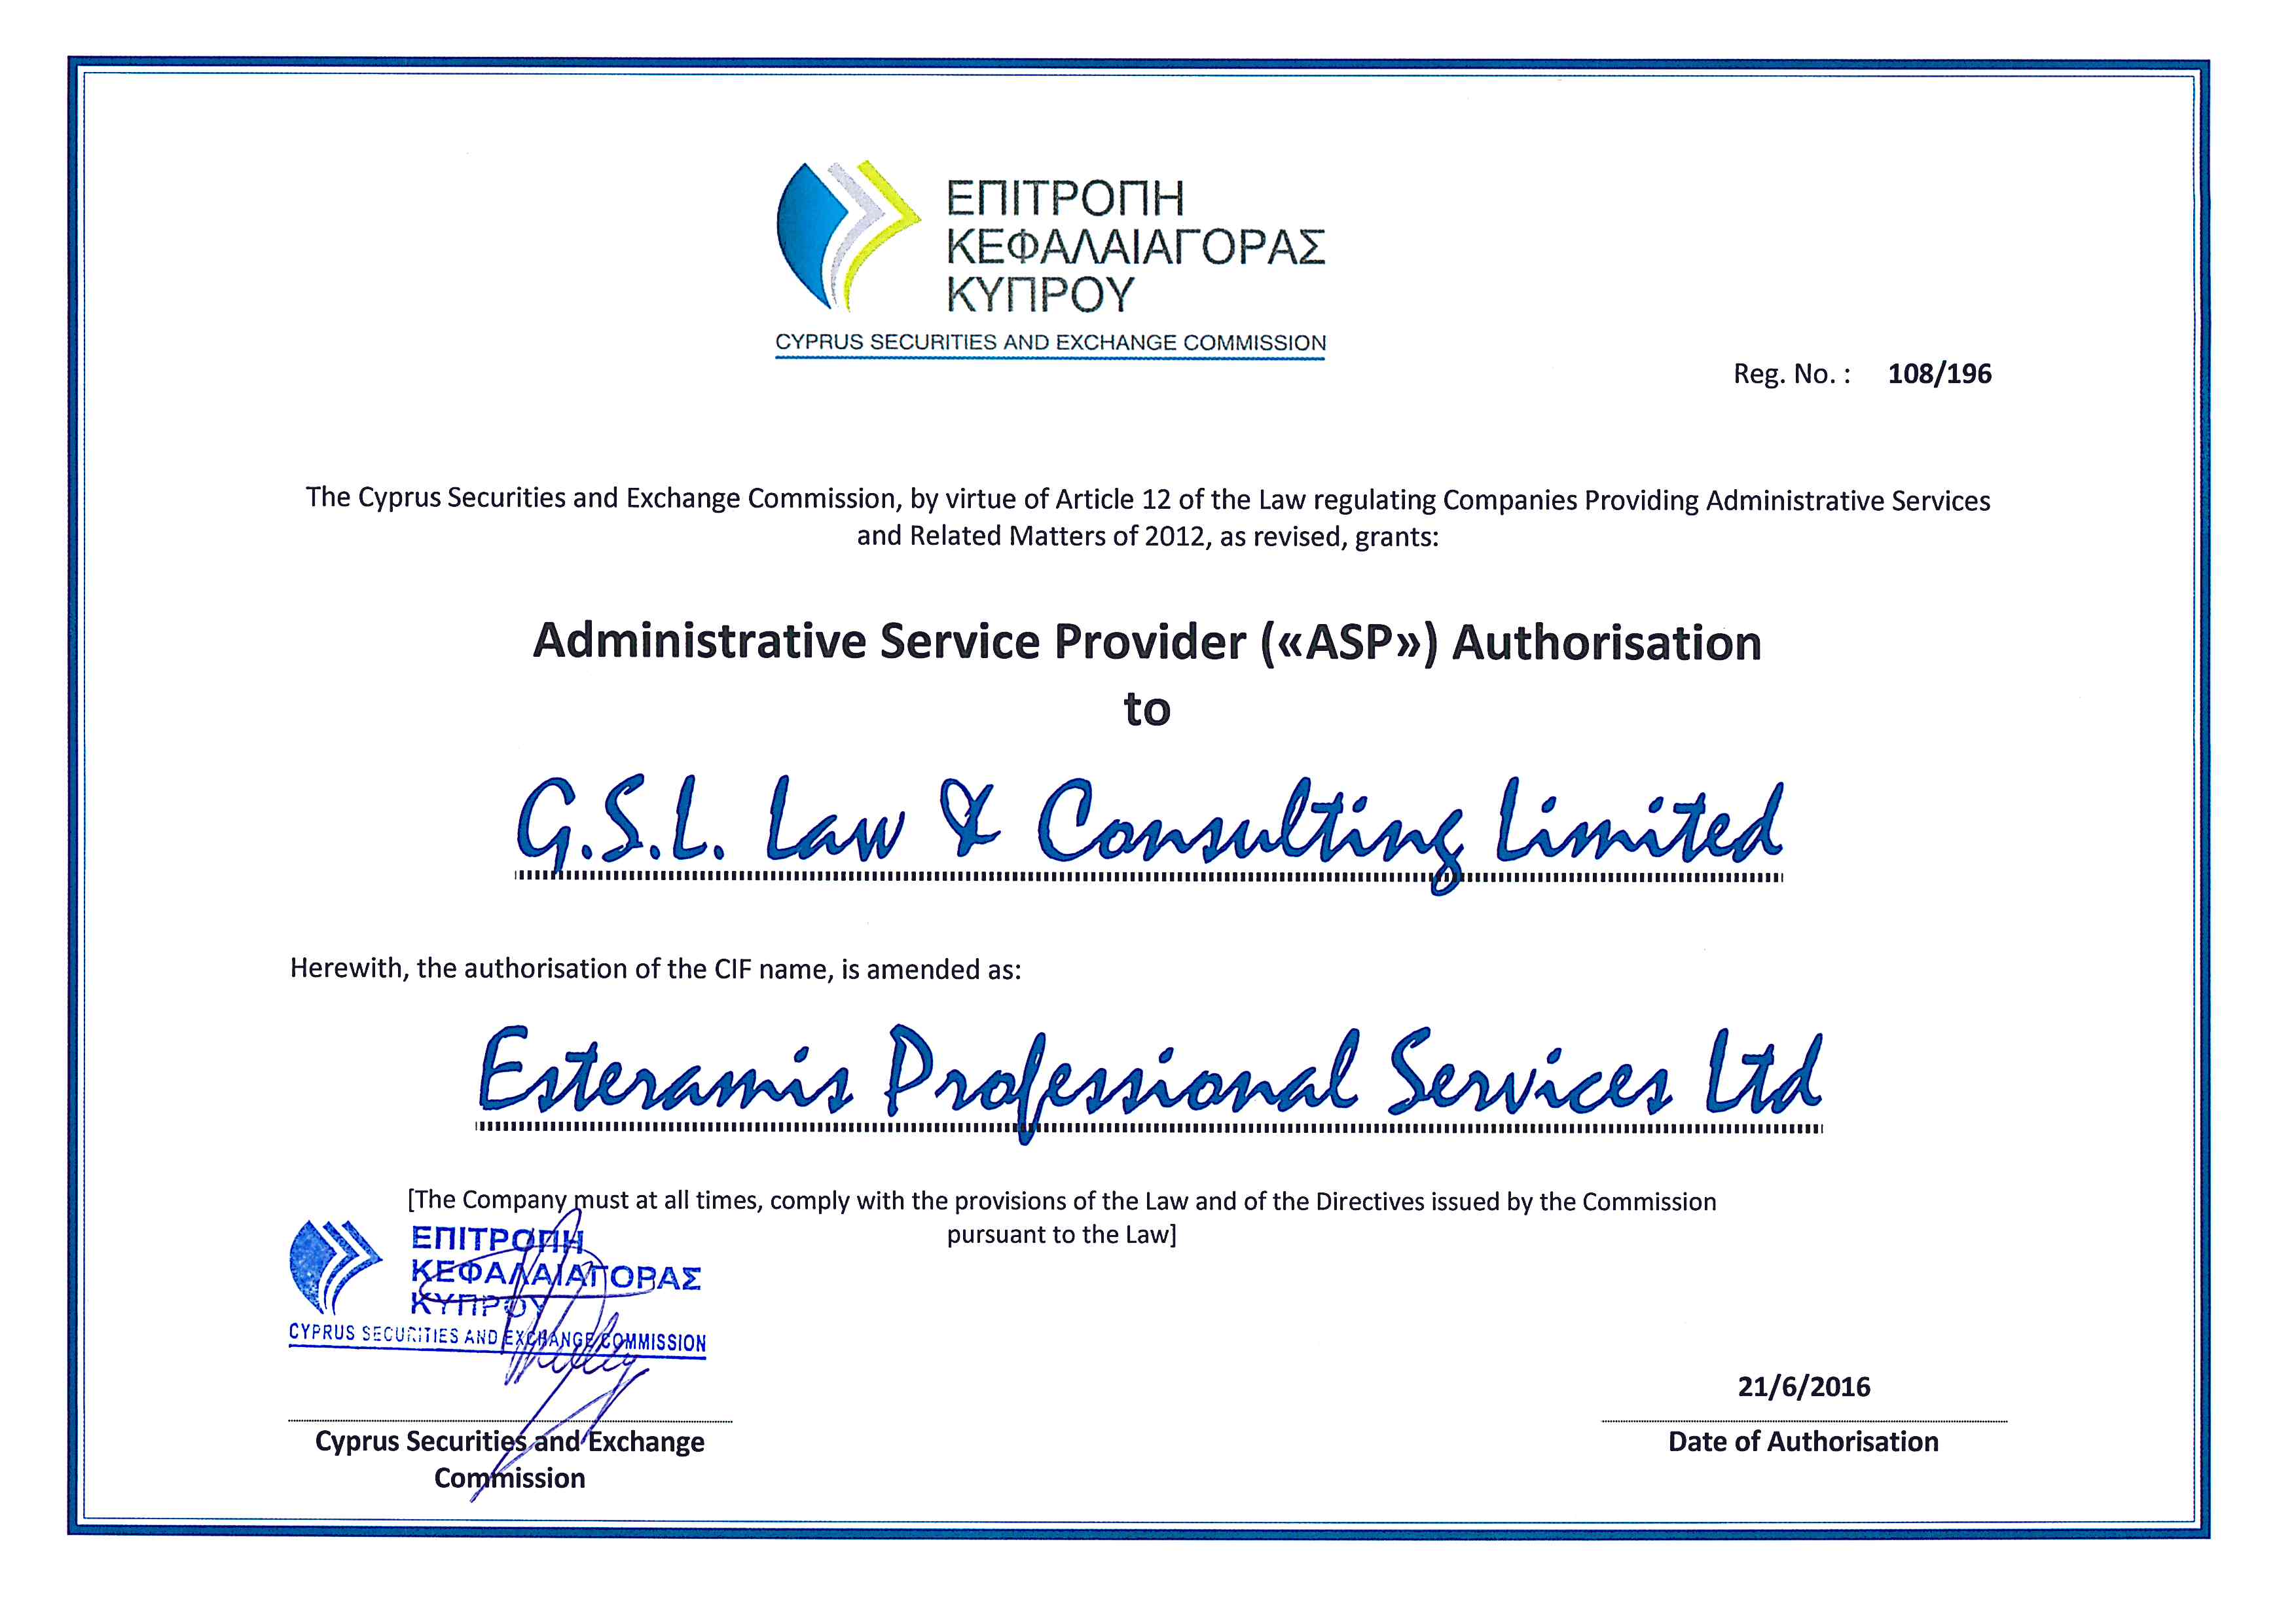
GSL is a licensed Administrative Service Provider (ASP) in Cyprus and operates in compliance with Anti-Money Laundering and Counter-Terrorist Financing (AML/CFT) legislation.
The licence authorises GSL to manage or administer trusts and legal entities (companies, partnerships, etc.), including:
While the law does not mandate that a company appoint a licensed administrative services provider (ASP) to act as its secretary – as this role can be performed by an individual or a non-resident without a licence – in practice, a company secretary should:
For this reason, it is common practice to engage professional ASPs such as legal, audit, or accounting firms that are subject to licensing. This ensures a high standard and quality of service, while minimising the risk of incurring penalties.
Working with us as a licensed ASP means that:
Our licence number is 108/196 — you can always verify our status in the official register.
Although a secretary is not a director, they are considered a key officer of the company and, in certain cases, may bear liability similar to that of directors for ensuring proper corporate governance and compliance with tax legislation.
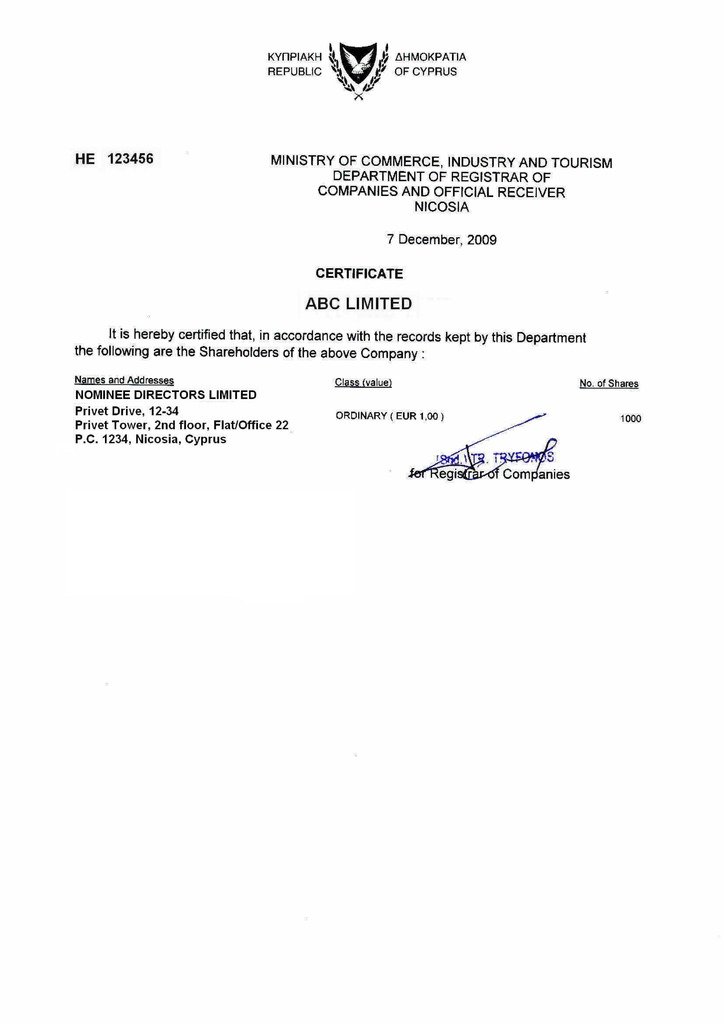
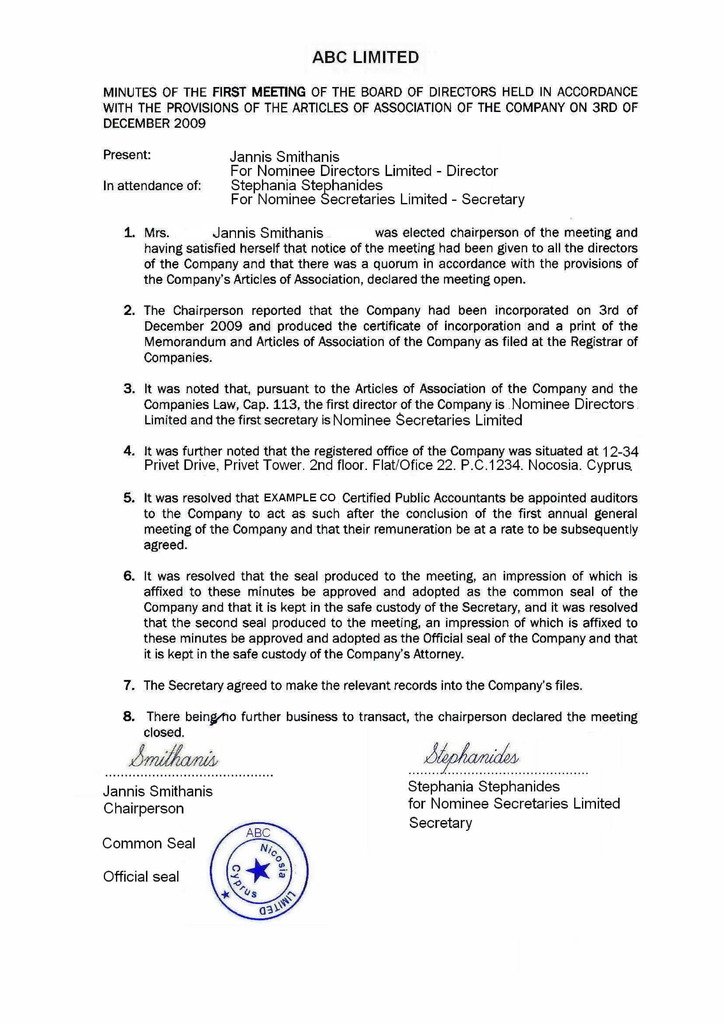
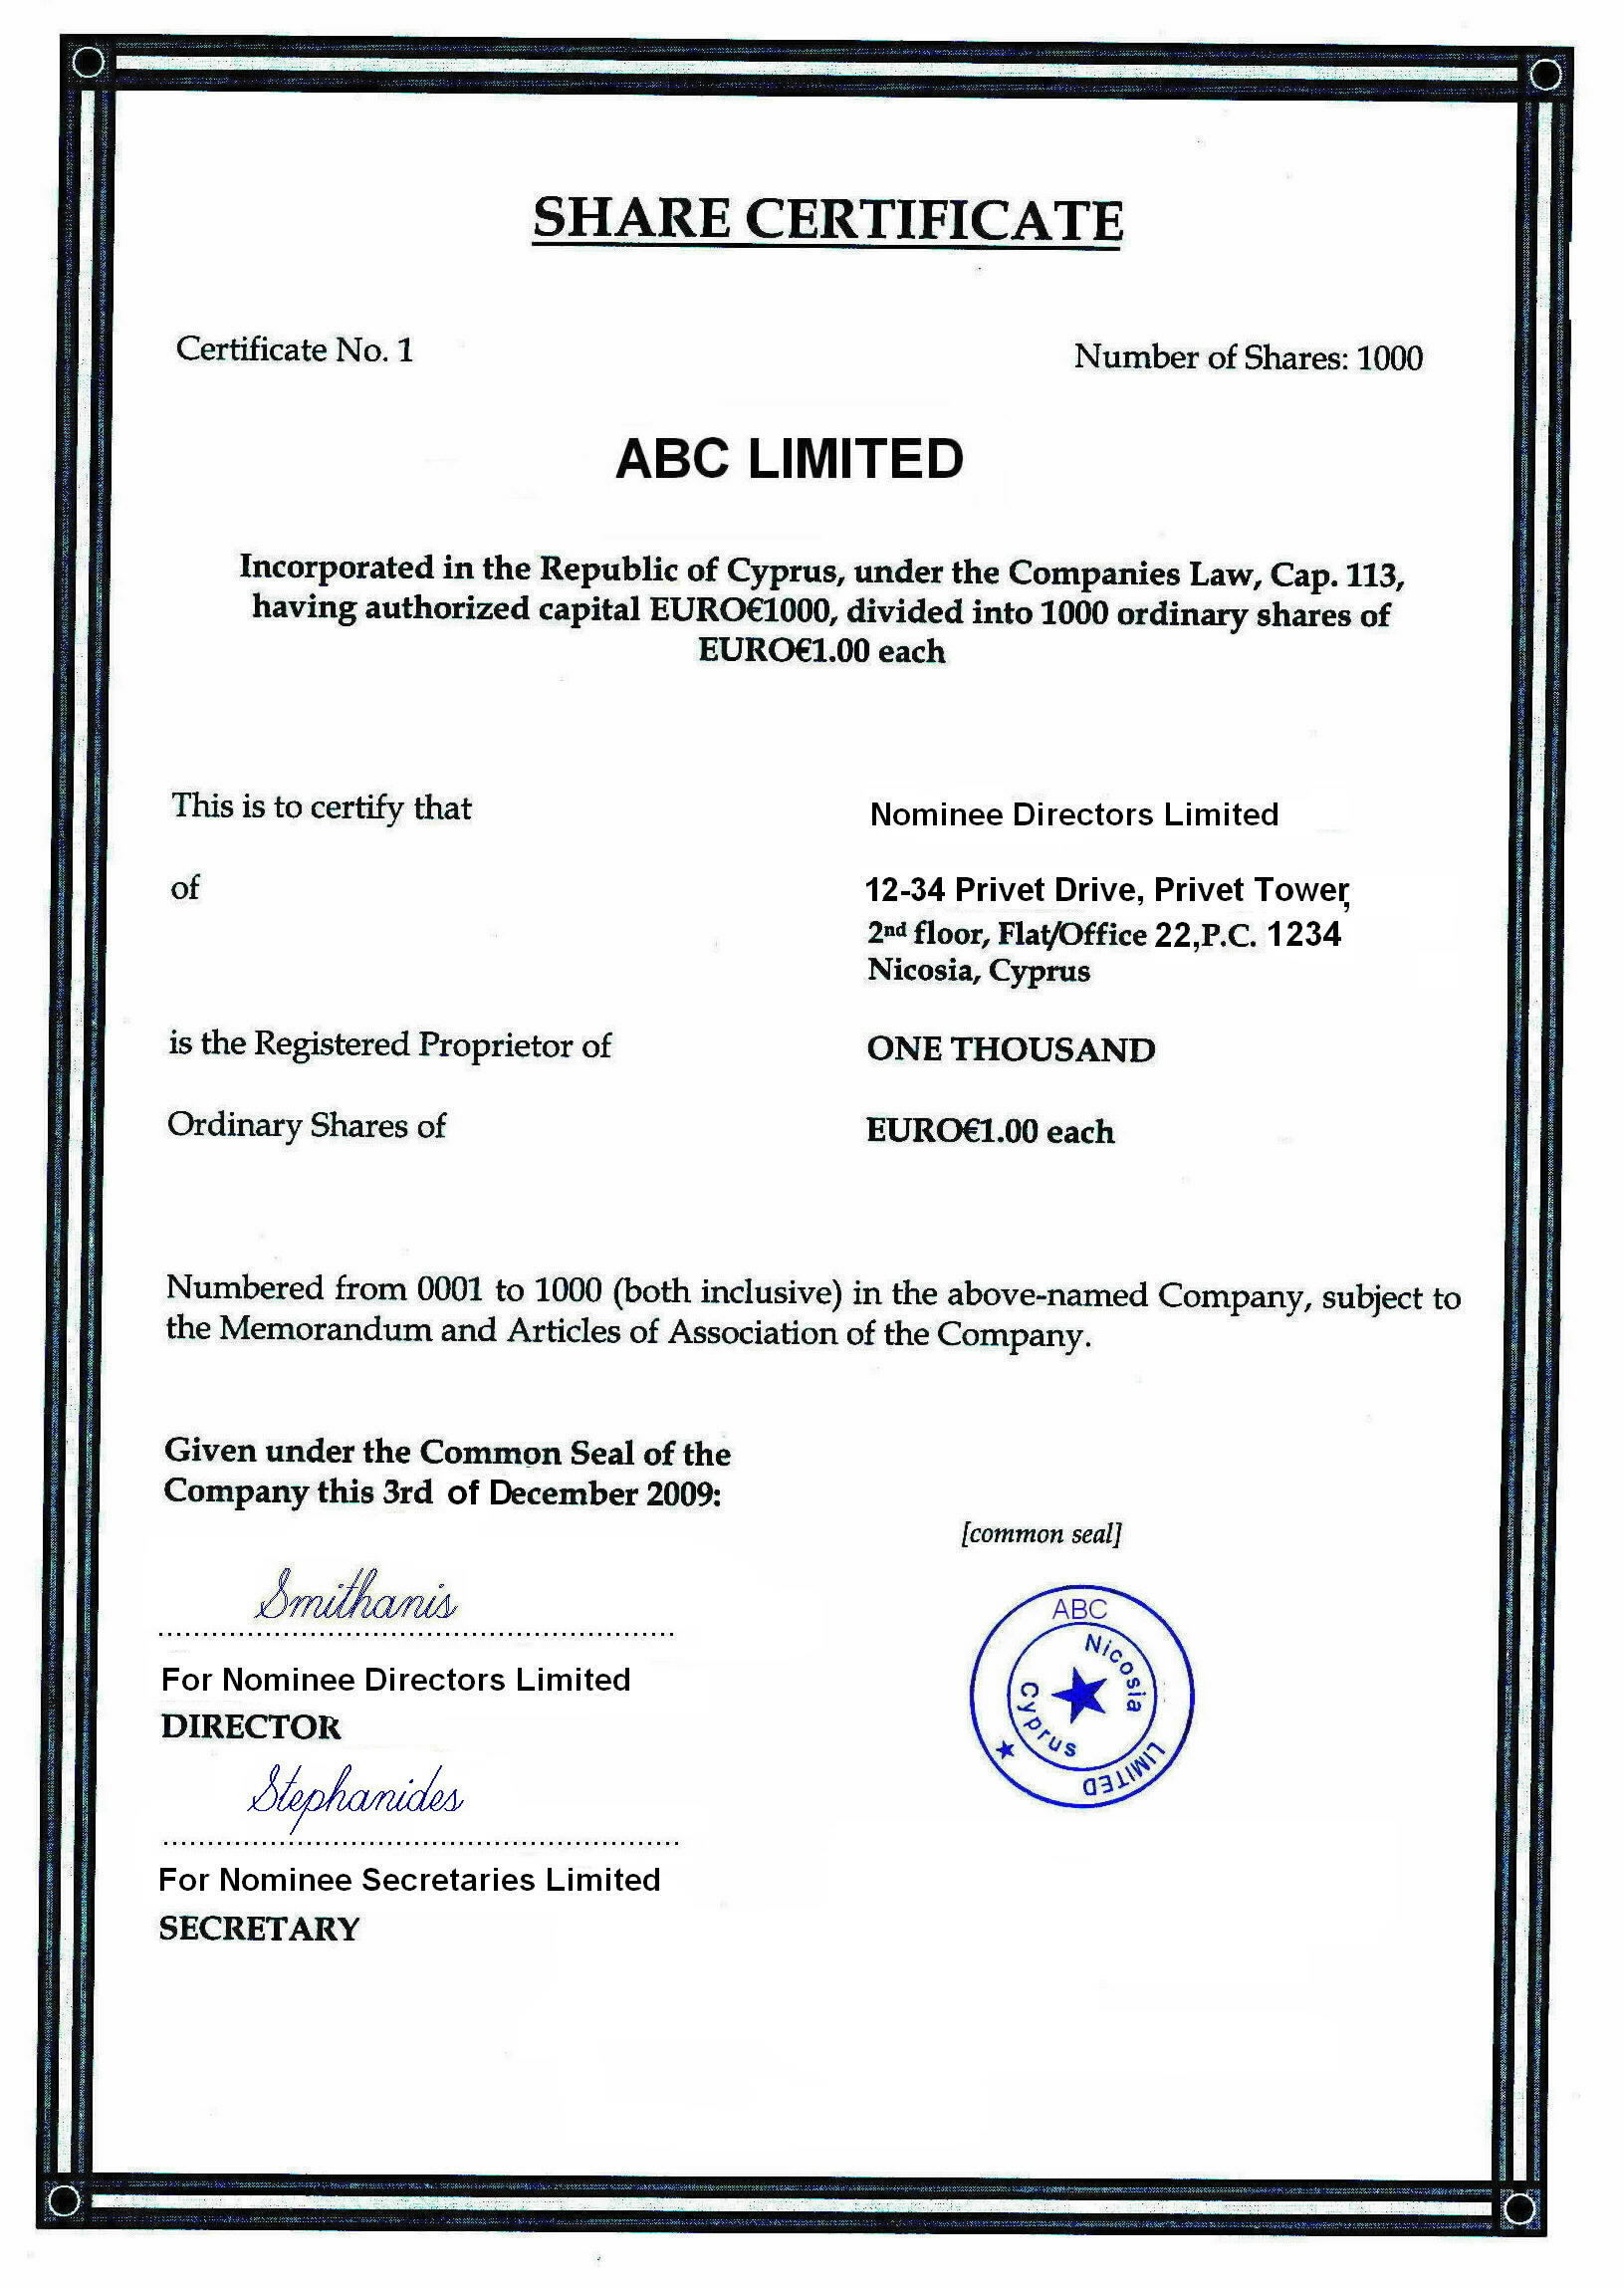
For the international structuring of assets, Cyprus offers a favourable tax environment: a low corporate income tax rate, no capital gains tax on the sale of shares, tax exemptions for dividends, no withholding tax on dividends, interest, and royalties paid to non-residents (subject to certain conditions). Furthermore, Cyprus has an extensive network of double tax treaties, which help reduce the tax burden when repatriating profits. Additional advantages include flexible corporate law, the option for 100% foreign ownership, minimal capital requirements, and a relatively straightforward process for establishing economic substance (such as an office and employees) compared to many other EU countries.
Cyprus is popular among IT and fintech companies due to a combination of tax advantages (described above, plus ‘IP Box’ – a preferential regime for income from intellectual property) and regulatory benefits. The regulatory framework is aligned with European standards while remaining relatively predictable and pragmatic.
The jurisdiction is a popular choice for establishing financial and investment structures, including investment funds (AIFs, RAIFs), investment firms (CIFs), and management companies. Modern regulations governing collective investments, aligned with EU standards, enable the structuring of funds to serve both European and international investors. The industry is supervised by the Cyprus Securities and Exchange Commission (CySEC), which ensures a balance of clear requirements, transparency, and EU-wide recognition.
An ideal location for establishing trade and logistics hubs, situated at the crossroads of maritime and air routes connecting Europe, the Middle East, and Asia. EU membership, well-developed port and transport infrastructure, and a competitive tax system enable the efficient structuring of supply chains, distribution, and the re-export of goods through a Cyprus company.
Cyprus is an attractive jurisdiction for vessel registration and the structuring of international shipping businesses, offering competitive tax regimes (such as a tonnage tax, which is based on a vessel’s capacity and replaces standard corporate income tax) as well as flexible regulations and well-developed port and service infrastructure.
Activity: An investment fund that raises capital from private or professional investors for investment in various assets.
Regulator: Cyprus Securities and Exchange Commission (CySEC).
Operational obligations: Adherence to an approved investment policy and risk/liquidity management procedures; monitoring and record-keeping of transactions; regular reporting to CySEC and investors; valuation of assets and monitoring of leverage; compliance with GDPR, sanctions, and CRS/FATCA regulations.
Consequences of non-compliance: Fines, suspension or revocation of registration, and potential criminal liability.
Key challenges of opening a Cyprus account:
Cyprus banks attract clients by their advanced online banking, low banking fees, and reasonable requirements regarding minimum account balances and initial deposits. However, they enforce strict compliance procedures, particularly for individuals who are resident outside the EU.
EMIs are often more flexible when it comes to client onboarding, making the account opening experience quicker and easier. However, compared to banks, they offer a limited range of products.
The client secured investors to expand their premium alcohol production business.
The investors contribute funds to the project, while the client contributes registered alcohol trademarks. The investors provide a loan to the client’s Russian company (which holds the trademarks), and that company transfers the trademarks to a new Cyprus entity comprising both the client and the investors. To protect the investors’ capital and maintain the client’s control over the business, GSL drafted a shareholders’ agreement, and the Cyprus company’s share capital was divided into ordinary shares (carrying voting rights) and redeemable preference shares (entitling holders to dividends and liquidation proceeds). The client receives a block of ordinary shares that secures a qualified majority and retains management control, although key matters, such as capital increase or trademark-related transactions, require unanimous approval. Meanwhile, the investor receives 99% of the preference shares, paying for them in-kind by contributing their loan receivable against the Russian company.
A Cyprus company was established to hold the investment and became the legal owner of the alcohol trademarks. Choosing Cyprus offered the client several advantages: no withholding tax on dividends, ability to quickly make a transparent shareholders’ agreement under English law, and a streamlined, cost-effective procedure for share redemption and settlements with a withdrawing shareholder, avoiding the need for special financial reporting or stamp duty payment.
A client is considering a trust as a means to preserve assets derived from his primary business in software development, and to transfer them to family members.
The client intended to put into a trust significant funds obtained from the liquidation of his foreign IT development company. The trust was designed not only to preserve these assets but also to provide for the client’s family members by growing the initial capital through investments in stocks and bonds. To achieve this, a financial advisor was integrated into the trust structure to oversee investment decisions, and accounts were opened at two European banks to facilitate the actual investment activities. GSL specialists drafted the trust deed, provided a professional licensed trustee, registered the trust with CySEC, and managed the coordination with the banks.
A trust was established for the client as a vehicle for capital growth and distribution within the family. The trust deed stipulates that the trustee must coordinate all asset-related transactions with the financial advisor; this ensures professional asset management while minimising operational and legal risks. The opening of bank accounts provided the trust with the necessary infrastructure for investing and holding funds.
A client required a legal opinion regarding a share purchase agreement for a Cyprus company shares.
GSL specialists reviewed the provided document. It was structured as an agency agreement, under which the client as the ‘Investor’ instructed an ‘Agent’ to acquire shares in a Cyprus company on the Agent’s own behalf, utilising the Agent’s pre-emptive subscription rights. In this arrangement, the Agent would hold the shares as the legal owner, effectively acting as a nominee shareholder or trustee. Such services require a licence from the Cyprus Securities and Exchange Commission (CySEC). As the Agent held no such licence, the proposed transaction was unlawful. Furthermore, even if the resulting legal relationship were to be classified as an ‘implied trust’, there remained a high risk of unpredictable consequences and litigation, for instance, should the arrangement infringe upon the rights of other shareholders who hold pre-emptive purchase rights.
Although all parties to the agreement were Cyprus companies, the agreement was governed by English law. Consequently, GSL analysed it under both Cyprus and English legal frameworks. Legal experts in both jurisdictions concluded that the agreement posed a significant risk to the client (the Investor) and jeopardised their interests.
The client intends to obtain a residence permit in Cyprus via investment.
To secure the residence permit, the client opted to invest in residential real estate, specifically a property from the primary market, as required by the programme. GSL specialists assisted the client in selecting qualifying properties from a reliable developer. Through our partners, we conducted a legal due diligence of the properties, amended the developer’s standard purchase agreement to safeguard the client’s interests, and registered the finalised contract with the Land Registry. Subsequently, GSL lawyers prepared and submitted the residence permit application for the client and his spouse, and liaised with the immigration authorities until the application was approved.
GSL successfully facilitated the purchase of a property that met all programme requirements and secured a Cyprus residence permit for the client. This immigration permit grants the right, but not the obligation, to reside on the island (a visit once every two years is sufficient). It offers the reputational benefits of a European residence permit without requiring the holder to be tied to the country. Furthermore, the investment in a liquid real estate asset provides the flexibility to exit the programme quickly should the client’s plans or circumstances change.
Establishing in Cyprus a place of business of a foreign company is governed by Sections 347–353 of the Companies Law, Cap. 113. Setting up a permanent place of business in Cyprus does not require the creation of a new legal entity; rather, it enables a legal entity registered outside Cyprus to operate as a branch within this jurisdiction.
Name and Address
The branch’s name may be identical to that of the foreign parent company. However, the branch will always have a separate registration number containing the prefix ‘AE’ (as opposed to ‘HE’, which is assigned to Cyprus companies).
The branch must have a physical address (not a P.O. Box) in Cyprus. This address serves as the destination for notices and communications, including those from government authorities, and is the location where registers and other documents must be kept under Cyprus law.
Registration
Although the branch is not a separate legal entity, the registration procedure is similar to that of a company.
Within 1 month of establishing a place of business in Cyprus, an application in the prescribed form must be prepared and submitted to the Registrar of Companies. The application must specify the name, registered office, business activities, and share capital of both the foreign company and the branch, as well as the list of directors and secretaries for both.
Subsequently, within 60 days of registration, the foreign company’s branch must register with the Cyprus tax authorities. If the branch employs staff, it must also register with the Social Insurance Service.
Appointment of an Authorised Representative
In addition to a director and a secretary, a branch must appoint an authorised representative to receive legal documents and notices in Cyprus, and to represent the company and the branch before courts and government authorities. The details of this representative must be submitted to the Registrar of Companies.
Financial Statements
Every foreign company with a branch in Cyprus must, for each financial year, submit to the Registrar of Companies the financial statements presented by the company at its most recent general meeting (including an auditor’s report and confirmation of publication, if required by the legislation of the country of incorporation). Furthermore, a parent company must maintain accounting records and prepare financial statements specifically for the branch itself; the first set of financial statements for the branch must be submitted not later than 18 months after its establishment, with subsequent submissions required on an annual basis.
Continuation in Cyprus
The Companies Law allows a foreign company to change its jurisdiction of incorporation and continue its operations as a Cyprus company. This procedure known as ‘redomiciliation’ does not require the liquidation of the existing entity or the creation of a new structure; the company retains its legal personality. Furthermore, redomiciliation neither terminates nor limits pre-existing obligations, nor does it disrupt the continuity of business operations – the company continues to exist as the same legal entity.
Redomiciliation Procedure
The specific documentation required will depend on the exit jurisdiction, but generally includes: a resolution to redomicile the company, its current registration and constitutional documents, registers of directors and shareholders, a Certificate of Good Standing, a Certificate of Incumbency, a special certificate issued by the local Registrar confirming that the company is permitted to continue outside its home country, and a legal opinion from a local legal practitioner confirming that such redomiciliation is permitted under the applicable law.
Additionally, the change of jurisdiction may require the publication of a notice of the intended redomiciliation, in order to protect the interests of creditors.
Continuation outside Cyprus
Cyprus legislation allows for the transfer of a company to a foreign jurisdiction without liquidation, provided that this does not contradict its memorandum and articles of association. The decision to redomicile is made by the company’s directors or shareholders and is carried out in accordance with the legal requirements of the entry jurisdiction.
To initiate the redomiciliation process, the company must confirm that it is in good standing, not subject to any regulatory restrictions, and has met all the requirements of the foreign jurisdiction’s laws for the transfer.
Redomiciliation Procedure
From the date the Certificate of Discontinuance is issued, the company is no longer considered registered in Cyprus and continues in a new jurisdiction.
Redomiciliation is a change of jurisdiction, not a termination of the company’s operations, therefore, the company takes all its obligations to a new country.
A Cyprus limited liability company can be closed in one of two ways: through liquidation or by being struck off the register.
A company can be liquidated by a court order. The grounds for such a liquidation are typically insolvency – the company’s inability to pay off its debts. A Cyprus company is considered insolvent if its debt exceeds EUR 5,000 and the company has failed to pay it or reach an agreement with its creditors within 3 weeks of receiving a written demand from them.
The voluntary liquidation of a Cyprus company can be initiated either by its shareholders or its creditors. Voluntary liquidation begins with passing a special resolution to that effect; a copy of this resolution must be submitted to the Registrar of Companies within 15 days of its making. The Registrar is required to publish the resolution in the Official Gazette of the Republic. The date on which the resolution to liquidate is adopted is deemed the commencement date of the liquidation.
A shareholders’ voluntary liquidation is possible only if the Cyprus company is expected to be able to settle its debts in full within 12 months of the commencement of the liquidation.
To initiate the liquidation process, a meeting of directors is held where the directors resolve to convene an extraordinary general meeting of shareholders to approve the company’s winding up and appoint a liquidator. The directors also make a statutory Declaration of Solvency (i.e., a declaration regarding the company’s ability to pay all its debts within a period not exceeding 1 year from the date liquidation commences). The Declaration of Solvency must be accompanied by a statement of assets and liabilities, prepared based on the company’s latest financial statements. The declaration must be drawn up and filed with the Registrar of Companies within 5 weeks preceding the date of the winding up resolution.
Next, an extraordinary general meeting of shareholders is held, at which a decision is made to wind up the company and appoint a liquidator. The liquidator is typically a lawyer or a professional accountant. They publish a notice in the Official Gazette regarding the commencement of liquidation and their appointment, and also file with the Registrar a special Form C.41 containing this information.
Subsequently, the company settles all obligations and closes its bank accounts; the liquidator gathers documentation on the company’s activities from the end of the last accounting period up to the date the bank accounts were closed, and a liquidation balance sheet is prepared based on this information. The liquidator also applies to the Tax Department for a Tax Clearance Certificate confirming that the company has no outstanding tax liabilities.
After all the company’s affairs are finalised, the liquidator holds a final meeting of shareholders (they are required to publish a notice convening the meeting in the Official Gazette 30 days in advance). At the meeting, the liquidator provides a report on the liquidation process and presents the liquidation balance sheet to the shareholders for approval. A copy of this report, along with a notice of the meeting, is submitted to the Registrar no later than 1 week after the meeting takes place. Three months after receiving these documents, the Registrar issues a Certificate of Dissolution.
Creditors’ voluntary liquidation. If the directors of a Cyprus company believe that it is unable to pay its debts, a voluntary liquidation initiated by creditors may be initiated. Shortly after the meeting at which the decision for voluntary liquidation is made, a meeting of creditors must be convened. Notice of this meeting must be published in the Official Gazette and in at least two local newspapers circulating in the area where the company’s registered office or principal place of business is located. The directors must present a full picture of the company’s affairs, along with a list of creditors and the estimated value of their claims. The creditors then appoint a liquidator and may also appoint an inspection committee to act alongside the liquidator. The liquidation procedure in this scenario is similar to a shareholders’ liquidation.
The liquidation process takes approximately 1 year, and once a Cyprus company has been liquidated, it cannot be restored.
A simpler and faster option for closing private companies that have ceased their operations is striking them off the register. Like liquidation, this process can be either voluntary, or compulsory.
Voluntary Striking Off
For a private company that has ceased operations but remains solvent, an alternative to liquidation is to have the company struck off (removed from) the register. This involves submitting a formal application to the Registrar of Companies. To ensure that the process is not halted due to objections from third parties, the following requirements must be met:
Strike-off is a relatively simple, inexpensive, and quick procedure for closing down private companies that have ceased operations; the procedure includes the following steps.
The company’s shareholders pass a resolution to cease business activities. All outstanding company obligations are settled, and bank accounts are closed. A liquidation balance sheet is then prepared, and the director requests confirmation from the Tax Department that the company has no outstanding tax liabilities (Tax Clearance Certificate). Following this, the director submits an application to the Registrar to initiate the formal striking the company off the register.
Once the Registrar is satisfied that all relevant legal requirements have been met, the application is registered, and a notice is published in the Official Gazette stating that the company will be struck off the register 3 months from the date of publication. After this 3-month period has elapsed, a notice of the strike-off is published in the Official Gazette, and the company’s status in the register is updated accordingly.
Since this concerns a voluntary removal from the register, the company has the option to withdraw its application within 3 months of the publication date and halt the striking off. To do so, it must submit Form HE61 to the Registrar of Companies.
Compulsory Striking Off
The Registrar may strike a company off the register for failure to comply with the Companies Law (such as failure to submit any statutory document, for instance, financial statements, or failure to pay the annual levy), or if the Registrar has reasonable grounds to believe that the company is not carrying on business.
If a Cyprus company’s operations are terminated via strike-off, it may be restored to the register within 20 years from the date of striking off.
A struck-off Cyprus company can be restored either through an administrative procedure or by court order.
A company may apply for administrative restoration if it was struck off by the Registrar of Companies for one of the following reasons:
An application for administrative restoration (Form HE64) may be submitted to the Registrar by a director or another officer of the company within 24 months from the strike-off date.
A company that has been struck off the register, whether voluntarily or compulsorily, may be restored if any interested party (such as a director, shareholder, creditor, or a person who suffered loss or damage prior to the strike-off) files an application with the court. The application must be submitted within 20 years from the strike-off date.
Having satisfied itself that the company was carrying on business or was otherwise active at the time it was struck off, or that restoring the company to the register is just, the court will issue an order for the company’s restoration. The court may also order the submission of all documents necessary to update the register and the payment of any outstanding fees to the Registrar of Companies.
An official copy of the court order must be submitted to the Registrar by the interested party. Once the Registrar is satisfied that all relevant legal requirements have been met, they will restore the company, update the register, and publish the information in the Official Gazette.
A key feature of the restoration procedure is that, once the company’s name is restored to the register, the company is deemed to have continued in existence without interruption, as if it had never been struck off.
Instead of tax, it would be more accurate to call it a licence fee levied by Cyprus municipalities on legal entities that have their registered office within municipal boundaries or conduct business within their territory.
The fee is governed by the Municipalities Law (Law 111/1985) and was introduced all the way back in 1985 to fund the operations and development of municipal services. However, for a very long time, many municipalities failed to enforce it strictly or consistently across all legal entities – a fact brought to light by an investigation by the Audit Office in 2015, which subsequently led to tighter control.
In December 2019, the Limassol Municipality announced that it would begin collecting an annual professional licence fee from companies registered within its jurisdiction. Following this, on 13 October 2020, the Union of Cyprus Municipalities adopted a unified policy for the collection of an annual fee from legal entities engaged in any commercial, trade, or professional activity within the boundaries of any given municipality. This policy standardised the fee across all municipalities, effective from 2021.
Company Categories and Fee Amount
For the purpose of charging the fee, all companies are classified into the following categories:
The fee is currently set at the following rates:
| Company category | Licence fee |
| Active companies that are not part of a group | EUR 250 |
| Active companies that are part of a group | EUR 150 |
| Dormant companies | No fee |
Exemptions and Reduced Rates
Payment Deadlines and Penalties
The municipality sends an annual invoice to the company’s registered office address, specifying the fee amount, payment methods, and the due date. Failure to pay by the deadline will result in a 10% penalty; an invoice detailing the penalties will be issued by the municipality separately.
All Cyprus companies are required to annually submit to the Registrar of Companies their audited financial statements prepared in accordance with International Financial Reporting Standards (IFRS). These statements must be filed alongside the company’s Annual Return (Form HE32).
The requirement to prepare and audit financial statements applies regardless of whether the company has conducted any business activities. If a company stayed dormant (with no bank transactions, contracts, or invoices), it must prepare and submit dormant financial statements.
Furthermore, based on its financial statements, a Cyprus company is required to annually file a tax return (Form IR4) with the Tax Department. This return must be filed regardless of whether the company has been active; if the company has generated no income, it must submit a nil tax return.
A company can choose any accounting period; however, the end date of the accounting period is normally aligned with the end of the calendar year (to simplify accounting for corporate income tax, for which the accounting period is the calendar year). The accounting period must not exceed 12 months, with the exception of the first period which can be up to 18 months long.
In practice, this is generally handled as follows:
Financial statements must be submitted for approval at the annual general meeting of shareholders and filed with the Registrar, together with the Annual Return (Form HE32), within 28 days of the annual general meeting.
The accounting period for corporate income tax is the calendar year.
The filing of a corporate tax return consists of two stages:
By 31 July of every financial year, Cyprus companies are required to estimate their projected profit for the current year. This estimate is used to calculate the amount of advance corporate income tax payable. Companies must also submit a provisional tax return reflecting this calculated advance payment amount.
The tax return must be filed with the Tax Department within 12 months of the end of the accounting period, i.e. by 31 December of the year following the accounting period. If filed electronically, this deadline is extended to 15 months. The tax return must be certified by the company’s auditor (who, in practice, also prepares it).
Effective 1 January 2026, amendments to the tax legislation establish a new deadline for companies to file tax returns and pay taxes: by 31 January of the second year following the tax year, i.e. 13 months after the end of the accounting period.
Contents of Financial Statements:
Cyprus companies that have subsidiaries (in which they hold more than 50% interest) are required to prepare consolidated financial statements for the group. An exception is made for small and medium-sized groups that meet at least two of the following three criteria in the accounting period:
Two general conditions must also be met for this exception to apply:
Financial statements must accompany the Annual Return; therefore, a late filing penalty is charged specifically due to the late submission of this form. The penalty consists of a base amount of up to 50 EUR, plus an additional 1 EUR for each day of delay, up to a maximum total of EUR 150.
Besides, without financial statements a company cannot file a tax return. Failure to submit a tax return on time results in a fixed penalty of EUR 100 or 200. Additionally, late payment of taxes incurs a penalty of 5% of the unpaid tax amount, with an extra 5% penalty if payment is made more than 2 months after the due date. Interest is also charged at a statutory rate (which varies from year to year).
Changes to transfer pricing (TP) regulations and adjustments to the transaction-volume thresholds for preparing TP documentation introduced a new reporting requirement for Cyprus companies, effective for tax periods beginning on or after 1 January 2022.
The Summary Information Table (SIT) — is an annual tax filing for companies that have transactions with related parties. It must be submitted by taxpayers for all transactions with related parties, regardless of the transaction value. Companies involved in intra-group transactions are required to file the SIT alongside their annual corporate income tax return.
The document is completed electronically in a tabular format and submitted via the Tax For All (TFA) portal. It includes details regarding the taxpayer, their related counterparties (including their tax residency), the categories of transactions (e.g., sales, services, financing), and the total value for each category, to ensure compliance with the arm’s-length principle.
The deadline for submitting the SIT to the tax authorities generally coincides with the deadline for filing the corporate income tax return.
Failure to submit the document on time will result in an administrative penalty of EUR 500.
Cyprus taxes its residents on their worldwide income, while still remaining one of the most competitive jurisdictions in the EU with a 15% corporate income tax rate. Cyprus imposes no capital gains tax on the sale of shares (except in cases involving Cyprus real estate), levies no withholding tax on dividends or interest paid to non-residents, and offers a preferential tax regime for intellectual property income (the “IP Box” regime) as well as a Participation Exemption system for dividends. Cyprus combines a low tax burden with specific regimes and incentives designed for international holding, financial, IT, and investment structures.
A progressive scale ranging from 0% (for income up to EUR 22,000) to 35% (for income exceeding EUR 72,000)
Tax base: wages, pensions, and remuneration
Tax relief: deductions for children, donations to registered charitable organisations, life insurance, social security, and pensions (contributions to non-state pension funds)
19%
Tax base: sale of goods and services
Tax relief: reduced rates of 9%, 5%, and 3%, as well as a zero rate and VAT exemptions (for medical, financial, and insurance services, education, and services in the fields of culture and the arts)
20%
Tax base: transactions involving Cyprus real estate and unlisted shares in companies that own such real estate
Dividends – 5% (effective 1 January 2026; previously 17%)
Interest – 17%
Rental income – None (fully abolished)
Tax base: passive income received by Cyprus tax residents
Tax relief: 3% rate for interest on Cyprus government bonds and exchange-traded bonds
Dividends – no*
Interest – no**
Royalties – no (if IP rights are not used within Cyprus) and 10% (if they are)
Tax base: passive income paid from Cyprus to non-residents
* 17% rate applies to dividends paid to сompanies in EU non-cooperative (blacklisted) jurisdictions, 5% – to affiliated companies in low-tax jurisdictions
**17% rate applies to interest paid to сompanies in EU non-cooperative (blacklisted) jurisdictions
Completely abolished as of 1 January 2026
The benefits of having a Cyprus company include: 1) a low corporate income tax rate of 15%, 2) EU membership and access to the European market, 3) an extensive network of tax treaties with other countries, 4) a stable and well-developed legal and regulatory framework, and 5) a high standard of professional services.
Cyprus is sometimes referred to as an offshore financial centre, though its status in this regard is not as clear-cut as that of certain other countries. Cyprus boasts a well-developed financial services sector and offers a range of advantages to companies, such as a low corporate income tax rate, a highly skilled workforce, and a favourable business environment. At the same time, the country has faced criticism regarding its tax practices and has been the subject of international investigations into tax evasion. In recent years, the Cyprus government has taken steps to enhance the transparency and integrity of its financial sector, while also working to improve its alignment with international standards. These efforts have helped dispel some of the negative perceptions previously associated with the country’s offshore status, making it a more attractive destination for legitimate business activities. Nevertheless, individuals and companies considering doing business in Cyprus should remain mindful of the country’s tax and regulatory landscape and ensure that their operations comply with all applicable laws and regulations.
The cost of establishing a firm in Cyprus depends on the type of company and the nature of the business activities you intend to engage in. A basic service package starts at EUR 2,500 and includes: turnkey company registration, a registered office and secretarial services for one year, payment of all required fees and levies, and apostilled corporate documents.
Yes, a non-resident can set up a company in Cyprus. Moreover, Cyprus has a well-developed system for attracting foreign investors and offers a number of advantages to non-resident companies, including a favourable tax regime, straightforward registration procedures, and access to a highly educated and multilingual workforce. Non-resident firms can be formed as private limited liability companies (LLCs) or public limited companies (PLCs) and can be wholly owned by foreign individuals or legal entities. However, it is important to note that there may be certain requirements that non-resident firms must meet, such as appointing a local registered agent or maintaining a minimum number of employees in Cyprus. It is advisable to seek professional advice to ensure compliance with local laws and regulations.
In Cyprus, the standard corporate income tax rate is 15%. This is one of the lowest corporate tax rates in Europe, which has made the country attractive to international companies looking to reduce their tax liabilities. However, it is important to note that other taxes, such as value added tax (VAT), may also apply.
A company name must be approved by the Registrar. Before submitting a formal application, it is advisable to independently check your chosen name(s) using the online search system for legal entities, as well as the register of trademarks, to make sure that no identical or similar company name or brand already exists. The proposed name must not be misleading, objectionable, or too similar to an existing one; while it may still be possible to use a name that resembles that of an existing company, this requires the latter’s written consent.
Once you have completed your own preliminary check, you may submit an application for name approval to the Registrar of Companies. The application must be accompanied by proof of payment of the required fee – EUR 10 for each proposed name (with an additional EUR 20 for expedited processing) – and authorisation from the relevant competent authority if the name includes any ‘restricted’ words.
The Registrar then conducts its own check which is not limited solely to commercial entities based in Cyprus. Consequently, the Registrar may, for instance, reject a name to protect the reputation of an international organisation, even if that organisation is not registered in Cyprus.
Once a name has been approved by the Registrar, it is reserved for a period of 6 months, meaning that the company registration must be completed before this period expires.
This is a name that:
The use of the following words and phrases in the name of a legal entity is regulated by the respective authorities listed below:
| Words and phrases | ||
| English | Greek | |
| Central Bank | ||
| bank | τραπεζα | |
| savings bank | ταμιευτήριο | |
| credit institution | πιστωτικό ίδρυμα | |
| cooperative credit institution | συνεργατικό κρεδόφόφό ίδρυμα | |
| Payment Institution | Ίδρυμα Πληρωμών | |
| Electronic Money Institution
e-money |
Ίδρυμα Ηλεκτρονικού Χρήματος | |
| Bureau de Change
Exchange |
Ανταλλακτήριο Συναλλάγματος | |
| CySec | ||
| Fixed Capital Investment Company / F.C.I.C. | εταιρεία επενδύσεων σταθερού κεφαλαίου / Ε.Ε.Σ.Κ. | |
| Variable Capital Investment Company / V.C.I.C. | εταιρεία επενδύσεων μεταβλητού κεφαλαίου / Ε.Ε.Μ.Κ. | |
| Alternative Investment Fund / AIF | οργανισμός εναλλακτικών επενδύσεων / ΟΕΕ | |
| Alternative Investment Fund with Limited Number of Persons / AIF with Limited Number of Persons / AIFLNP | οργανισμός εναλλακτικών επενδύσεων με περιορισμένο αριθμό προσώπων / ΟΕΕ με περιορισμένο αριθμό προσώπων / ΟΕΕΠΑΠ | |
| Registered Alternative Investment Fund / RAIF | Καταχωρισμένος Οργανισμός Εναλλακτικών Επενδύσεων / ΚΟΕΕ | |
| Superintendent of Insurance | ||
| insurance company
reinsurance company |
ασφαλιστική εταιρεία
αντασφαλιστική εταιρεία |
|
| Ministry of Energy, Commerce and Industry | ||
| casino | καζίνο | |
| Ministry of Education and Culture | ||
| university
polytechnic school academy college |
πανεπιστήμιο
πολύτεχνειο σχολή ακαδίμη κολέγιο |
|
| Cyprus Radiotelevision Authority | ||
| radio
television |
ραδιόφωνο
τηλεόραση |
|
| Cyprus Medical Council | ||
| DLC (Doctors’ Limited Company) | I.E.Π.E | |
| Cyprus Dental Council | ||
| DeLC (Dentist Limited Company) | Ο.Ε.Π.Ε | |
| Law Office of the Republic of Cyprus | ||
| LLC (Lawyers’ Limited Company) | Δ.Ε.Π.E | |
Yes, a Cyprus company can omit the word ‘Limited’ from its name if it is established as a non-profit organisation for the purpose of promoting commerce, art, science, religion, charity, or any other public interest. In such cases, the company’s constitutional documents must explicitly state that it is a non-profit entity, that any income (if generated) is to be used solely for its stated objectives, and that the payment of dividends to its members is prohibited. Provided these conditions are met, the Council of Ministers may grant permission for the organisation to be registered as a limited liability company without including ‘Limited’ in its name. This authorisation is granted following the review of an application, which may be submitted either at the time of the company’s initial registration or upon a change of its name, pursuant to a special resolution.
If, at the time of initial registration or upon a change of name, a company (whether by mistake, oversight, or for any other reason) adopts a name that, in the opinion of the Council of Ministers, is too similar to an existing one, the Council may direct the company to change its name. If the company has used the said name for more than 6 months by that point, it must change it within 6 weeks or such other period as the Council may specify; failure to do so will result in a fine.
Following a compulsory name change, the Registrar will not only update the register with the new name but also issue an amended certificate of incorporation. A change of name does not affect the company’s rights and obligations, nor does it impact any legal proceedings initiated by or against the company; all procedural actions, whether ongoing or newly commenced, will reflect the new name.
In 2011, an annual levy of EUR 350 was introduced for all Cyprus companies; this levy was abolished as of 2024. However, this abolition does not affect a company’s obligation to pay the levy for the period from 2011 to 2023, including any applicable penalties.
Every company registered in Cyprus, whether active or dormant, was required to pay this annual levy by 30 June of each year. Failure to pay on time resulted in the following penalties:
The group companies, for which the total combined levy did not exceed EUR 20,000, would divide the sum equally among them in equal parts.
Companies that failed to pay the annual levy were subject to strike-off under Section 327 of the Companies Law. The Registrar could proceed to strike a company off the register if the levy remained unpaid for 1 year beyond the established deadline.
Every company must keep proper accounting books and records which serve as the basis for the preparation of its financial statements. These accounting books and records must provide a true and fair view of the company’s financial affairs and enable its financial position to be determined with reasonable accuracy at any given time. They must also include supporting documentation (such as contracts and invoices) that reflects:
Accounting books and records must be retained for 6 years following the end of the calendar year to which they relate.
They are to be kept at the company’s registered office or at such other place as the directors may decide, and must be available to the directors for inspection at all times. If accounting books and records are kept outside Cyprus, they must be made available in Cyprus at least once every 6 months – to the extent necessary to accurately reflect the company’s financial position – so that the directors are able, at any given time, to prepare a balance sheet, a profit and loss account, and any other documents required by the Companies Law.
The duty to prepare financial statements rests with the company’s directors. They are required to prepare financial statements annually for each accounting period in accordance with International Financial Reporting Standards. If a company is a holding company at the end of the financial year, the directors must prepare consolidated financial statements rather than individual (stand-alone) financial statements, unless specific provisions apply that limit the obligation to consolidate.
The financial statements for the financial year must provide a true and fair view of the company’s financial position at the end of the year, as well as the financial results of its operations for that year.
The Annual Return (Form HE32) is not, in itself, a part of financial statements. It contains registration details and information regarding the company’s corporate structure such as data on all directors and shareholders, the registered office, and the share capital (including any changes thereto). However, financial statements must be attached to this return.
The duties of directors of Cyprus companies are defined by both common law and statute, and fall into several categories:
Fiduciary duties
A director’s fiduciary duties are rooted in loyalty and faithfulness: they must act in good faith, with honesty, and in the best interests of the company and its shareholders (both current and future); they must avoid conflicts between their personal interests and their professional duties, refrain from deriving any undisclosed benefits from their position, comply with the company’s articles and the law, and duly perform their functions to achieve the company’s objectives.
Statutory duties
These duties are primarily established by the Companies Law and tax legislation:
Duty of care and skill
This duty is based on the concept of a ‘reasonably diligent person’: a director is expected to demonstrate the level of professionalism, prudence, knowledge, and experience that would be anticipated from an individual in a similar position with comparable qualifications. If a director acts honestly and in the best interests of the company, they are not held liable for any resulting damage. This standard is objective in nature, relying on the ‘benchmark’ test of a reasonable person, and if a director possesses specialised skills or qualifications, they are required to apply those as well, in addition to meeting the baseline standard.
There is no specific, separate document issued upon the annual renewal of a company. However, a company may request a Certificate of Good Standing (CGS), an official document issued by the Registrar of Companies. It confirms that, as of the date of issuance, the company is on the Cyprus register of companies and has no outstanding obligations, such as the filing of annual returns or the payment of required fees. A CGS also means that the company is not dissolved or in liquidation. This document may be requested by banks and EMIs where the company holds accounts, as well as by business partners, courts, and other entities.
The CGS includes the company’s name, registration number, date of incorporation, and its status as being in ‘good standing’ – a term that refers to the company’s legal, rather than financial, status. A request for this certificate can be submitted online via the Registrar of Companies’ e-filing system (www.companies.gov.cy).
Every Cyprus company is required to hold an annual general meeting (AGM) of its shareholders. The first such meeting must take place within 18 months of the company’s incorporation date; consequently, it is not mandatory to hold one during the year of incorporation or the following year. Thereafter, an AGM must be held at least once every 15 months, and the notice convening the meeting must specify its nature.
If an AGM is not held, any shareholder may apply to the Council of Ministers, which has the authority to order that a meeting be convened. The Council may also issue specific instructions, which may even deviate from the company’s articles of association, regarding how the meeting is to be called and conducted. By a resolution of the company, such a meeting may be designated as the AGM for the relevant year; in this case, a copy of the resolution must be filed with the Registrar within 15 days of the meeting.
Failure to hold an AGM or to comply with the instructions of the Council of Ministers may result in a fine of up to CYP 250 for the company and its officers, while failure to file the resolution may incur a fine of up to 25 CYP.
Following a ruling by the Court of Justice of the European Union, public access to information held in the register of beneficial owners has been suspended in Cyprus since November 2022. Currently, the following parties have access to information on beneficial owners via the electronic register:
Competent supervisory authorities in Cyprus, the Financial Intelligence Unit (FIU), the Customs Department, the Tax Department, the police, the Treasury, the Audit Office, the Internal Audit Service, the Directorate General for Development (under the Ministry of Finance), as well as the European Commission, the European Court of Auditors, the European Anti-Fraud Office (OLAF), and the European Public Prosecutor’s Office (EPPO), all have prompt and unrestricted access, free of charge and without having to notify the company concerned.
Banks, lawyers, auditors, and other professional entities, in the context of conducting customer due diligence and identification, have access to the following information: name, month and year of birth, nationality, country of residence, and the nature and extent of the beneficial owner’s interest. Access is granted upon payment of a fee of EUR 3.50 per company and approval of the request by the Registrar.